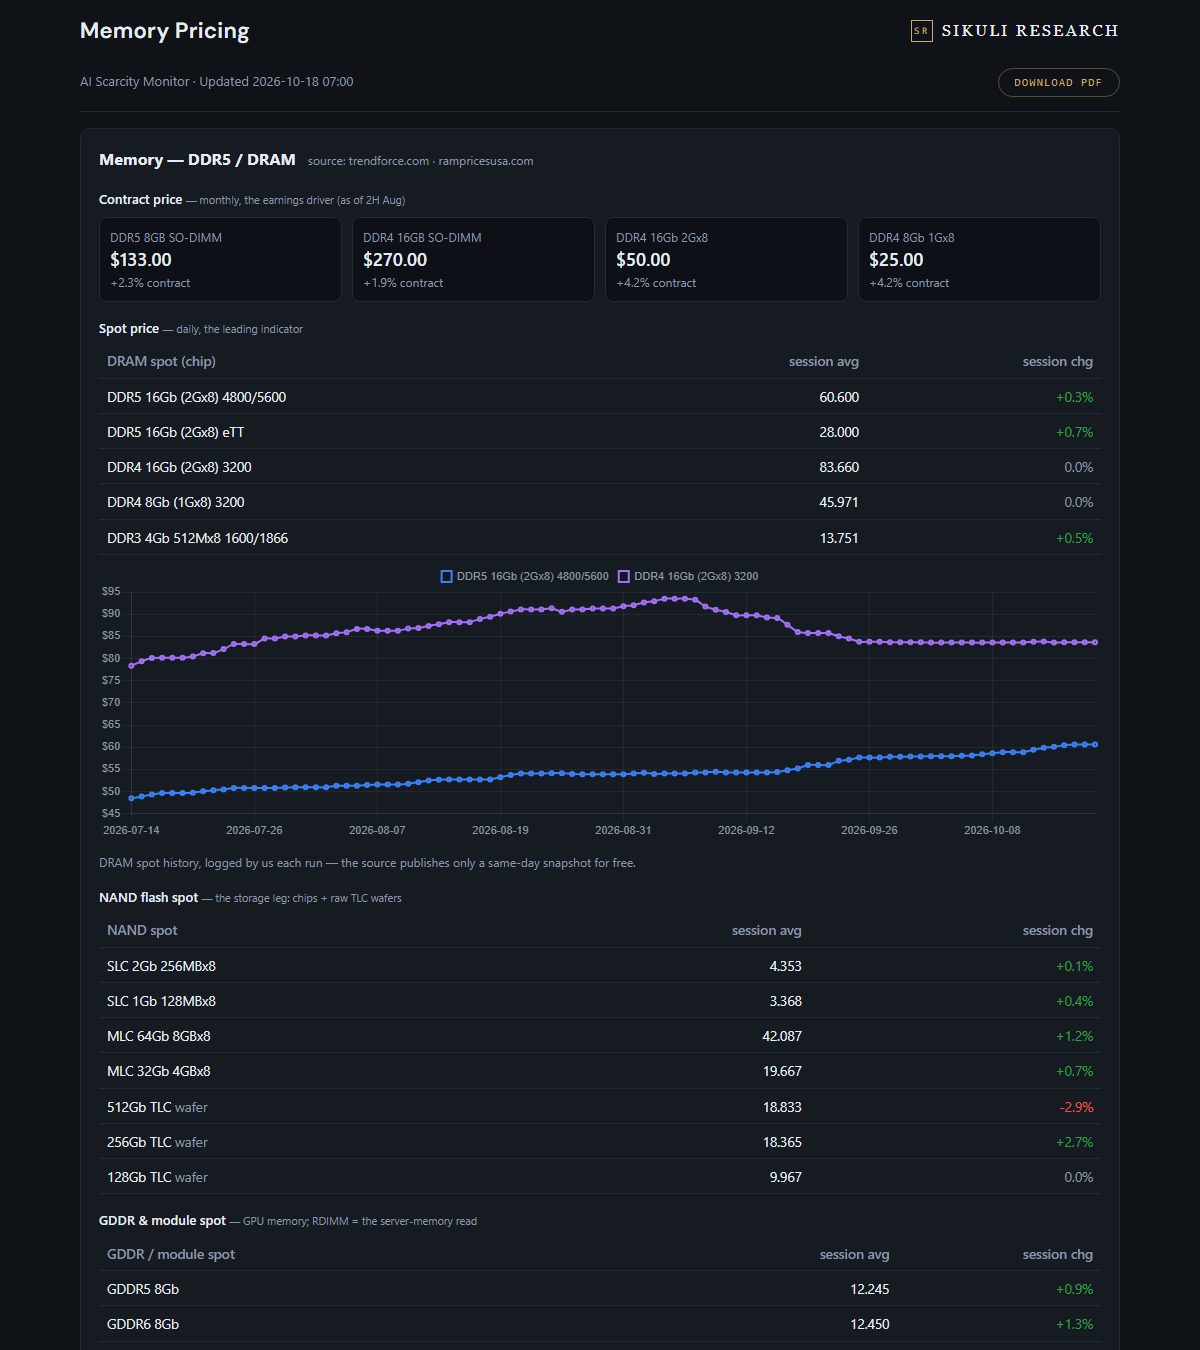
Memory / DRAM Pricing - Oct 18
DDR5 8GB SO-DIMM contract $133.00 (+2.3%, 2H Aug) DDR5 16Gb (2Gx8) 4800/5600 spot $60.60 (+0.3%) DDR4 16Gb 2Gx8 $50.00 (+4.2%) Retail DDR5 $18.62/GB $QQQ #SPX Full report at Sikuli Research (link in bio)
The running archive — 428 posts: Morning and Evening Full Reads, $SPX gamma positioning, earnings desk notes, scarcity data and every research report, newest first. Updated automatically as we post.
DDR5 8GB SO-DIMM contract $133.00 (+2.3%, 2H Aug) DDR5 16Gb (2Gx8) 4800/5600 spot $60.60 (+0.3%) DDR4 16Gb 2Gx8 $50.00 (+4.2%) Retail DDR5 $18.62/GB $QQQ #SPX Full report at Sikuli Research (link in bio)
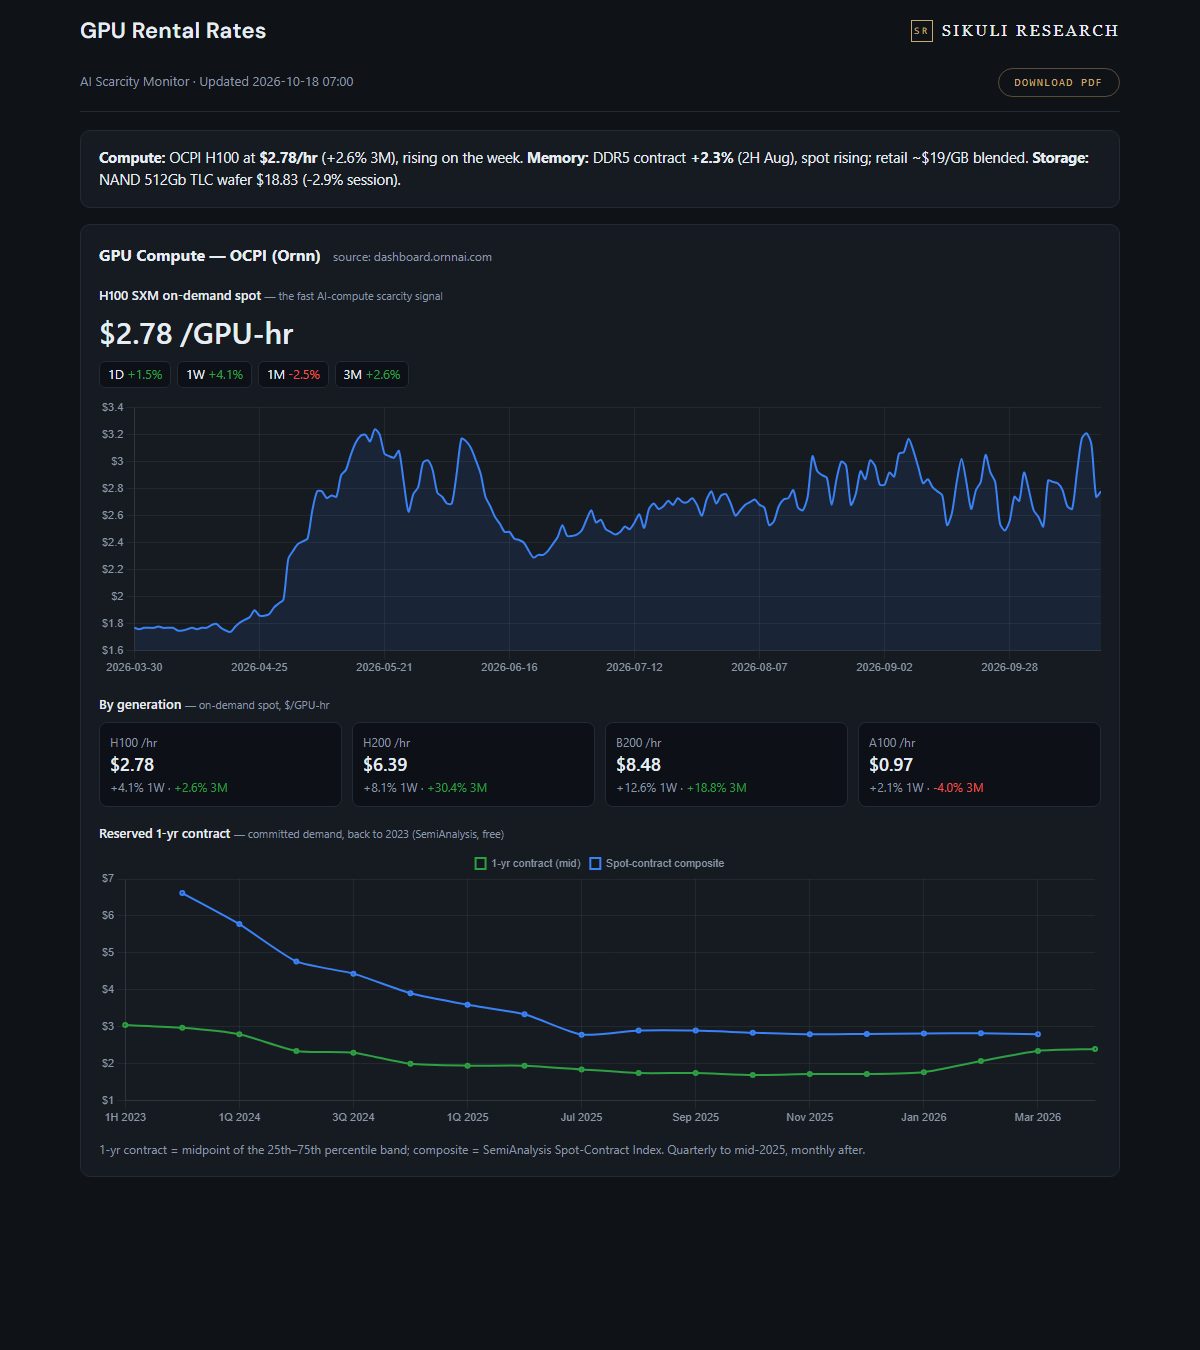
H100 $2.78/hr (1D +1.5% | 1W +4.1% | 1M -2.5% | 3M +2.6%) H200 $6.39 | B200 $8.48 | A100 $0.97 $QQQ #SPX Full report at Sikuli Research (link in bio)
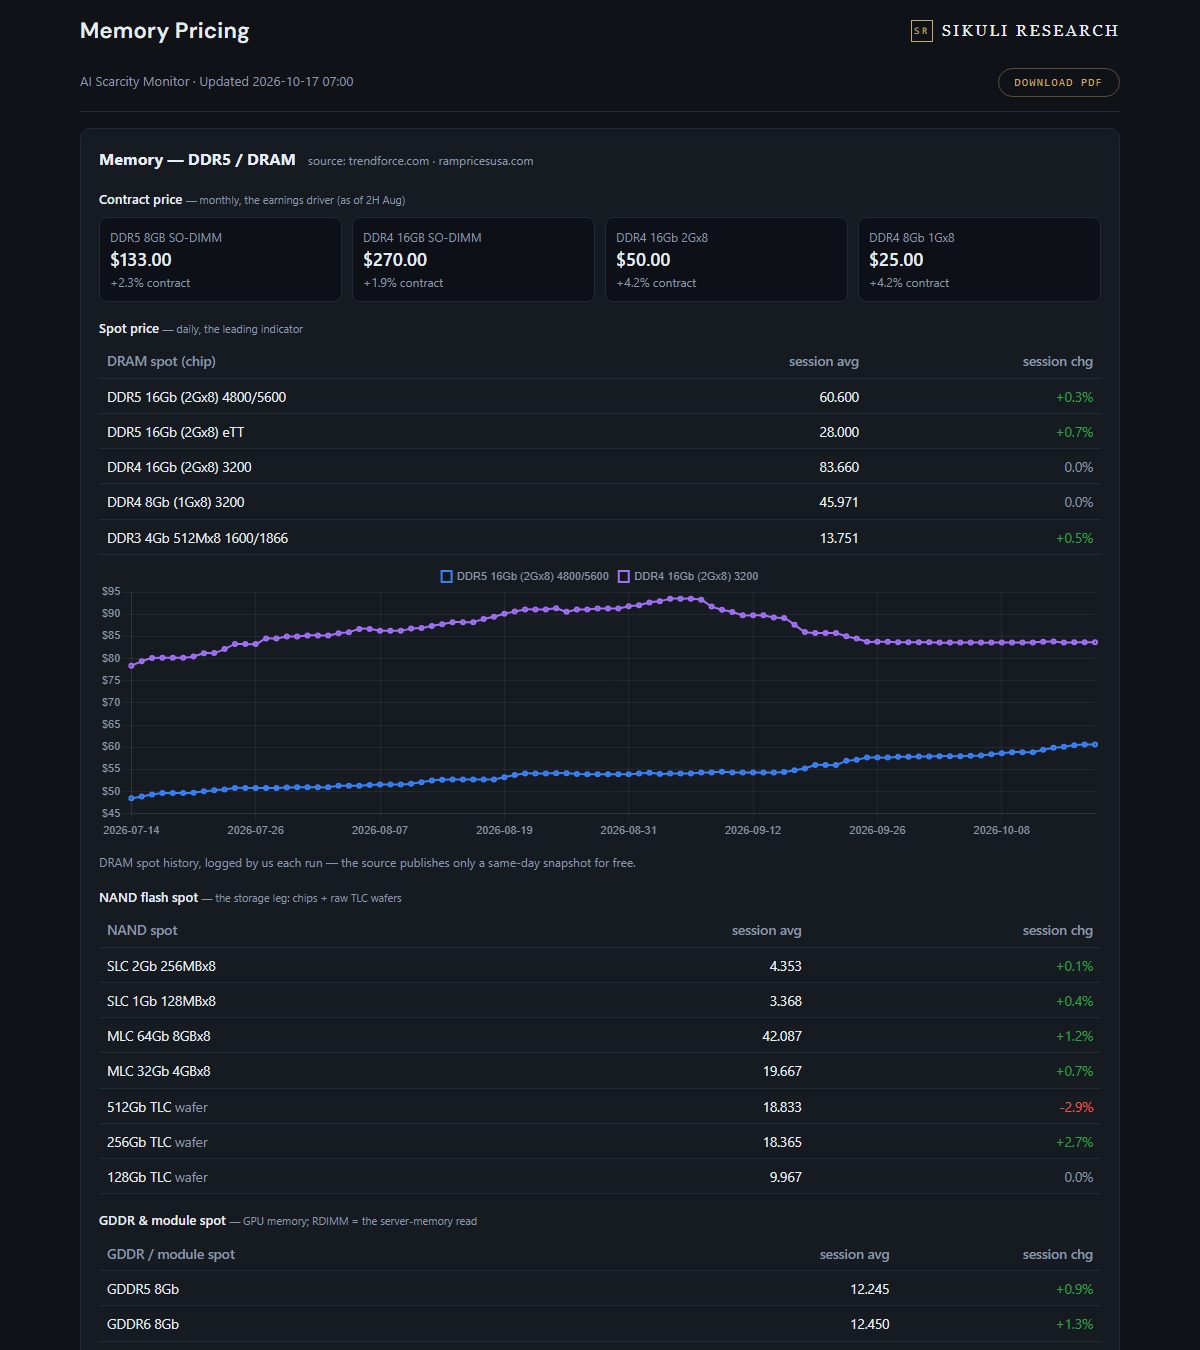
DDR5 8GB SO-DIMM contract $133.00 (+2.3%, 2H Aug) DDR5 16Gb (2Gx8) 4800/5600 spot $60.60 (+0.3%) DDR4 16Gb 2Gx8 $50.00 (+4.2%) Retail DDR5 $18.62/GB $QQQ #SPX Full report at Sikuli Research (link in bio)
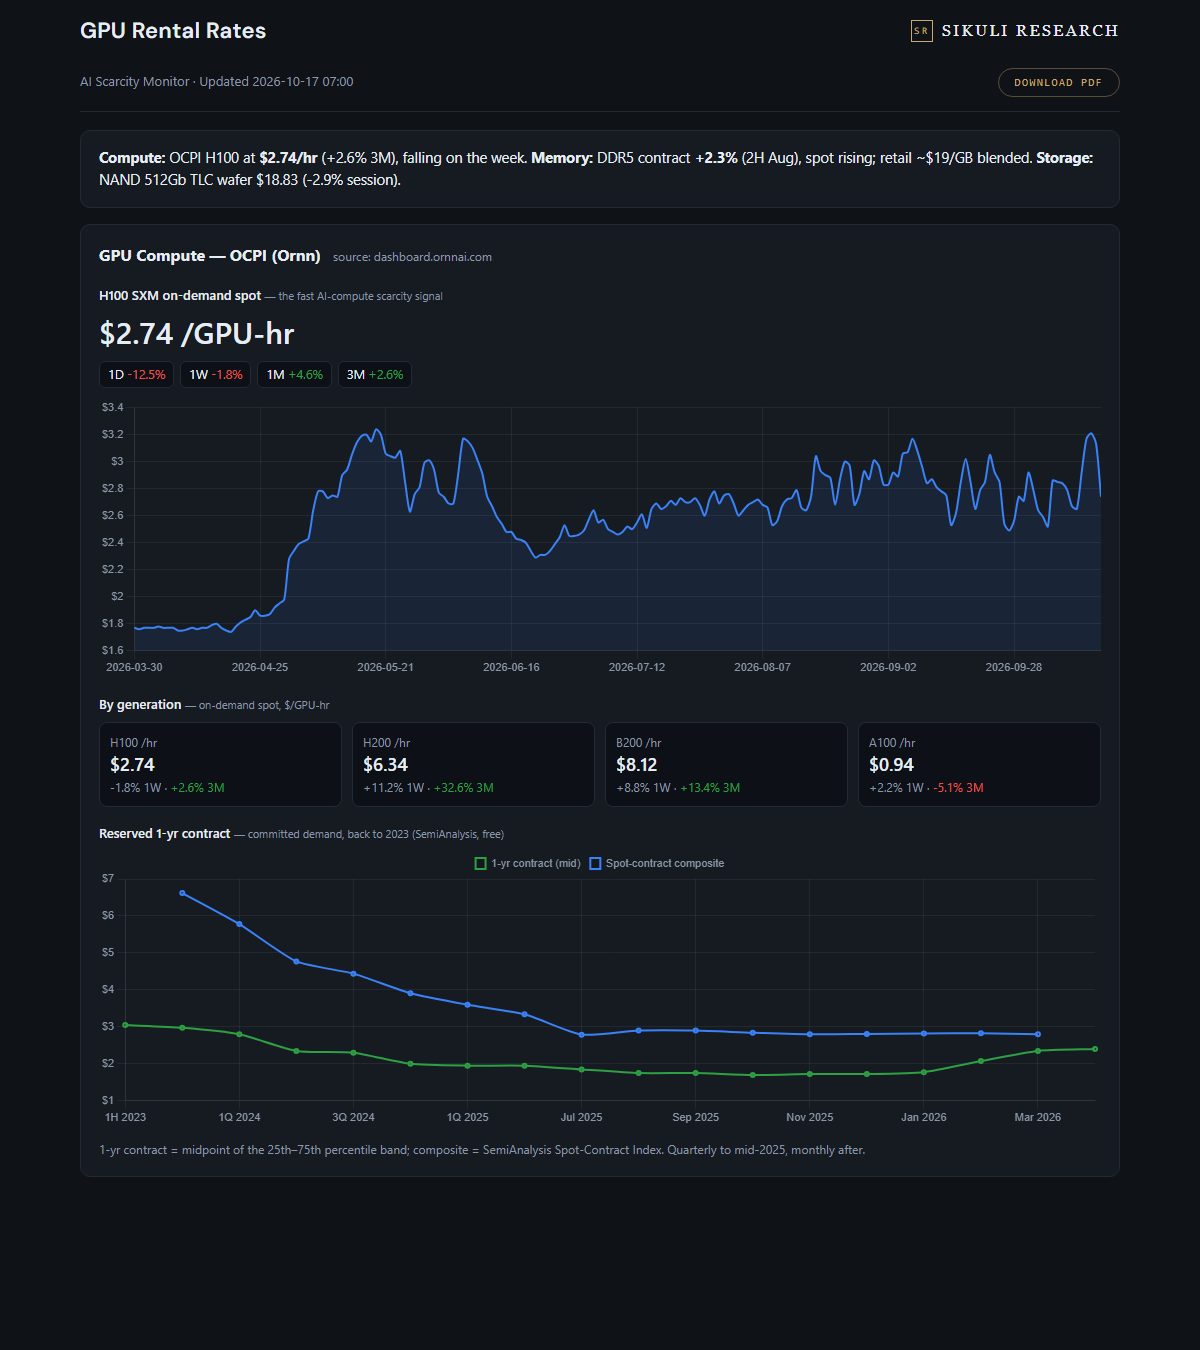
H100 $2.74/hr (1D -12.5% | 1W -1.8% | 1M +4.6% | 3M +2.6%) H200 $6.34 | B200 $8.12 | A100 $0.94 $QQQ #SPX Full report at Sikuli Research (link in bio)
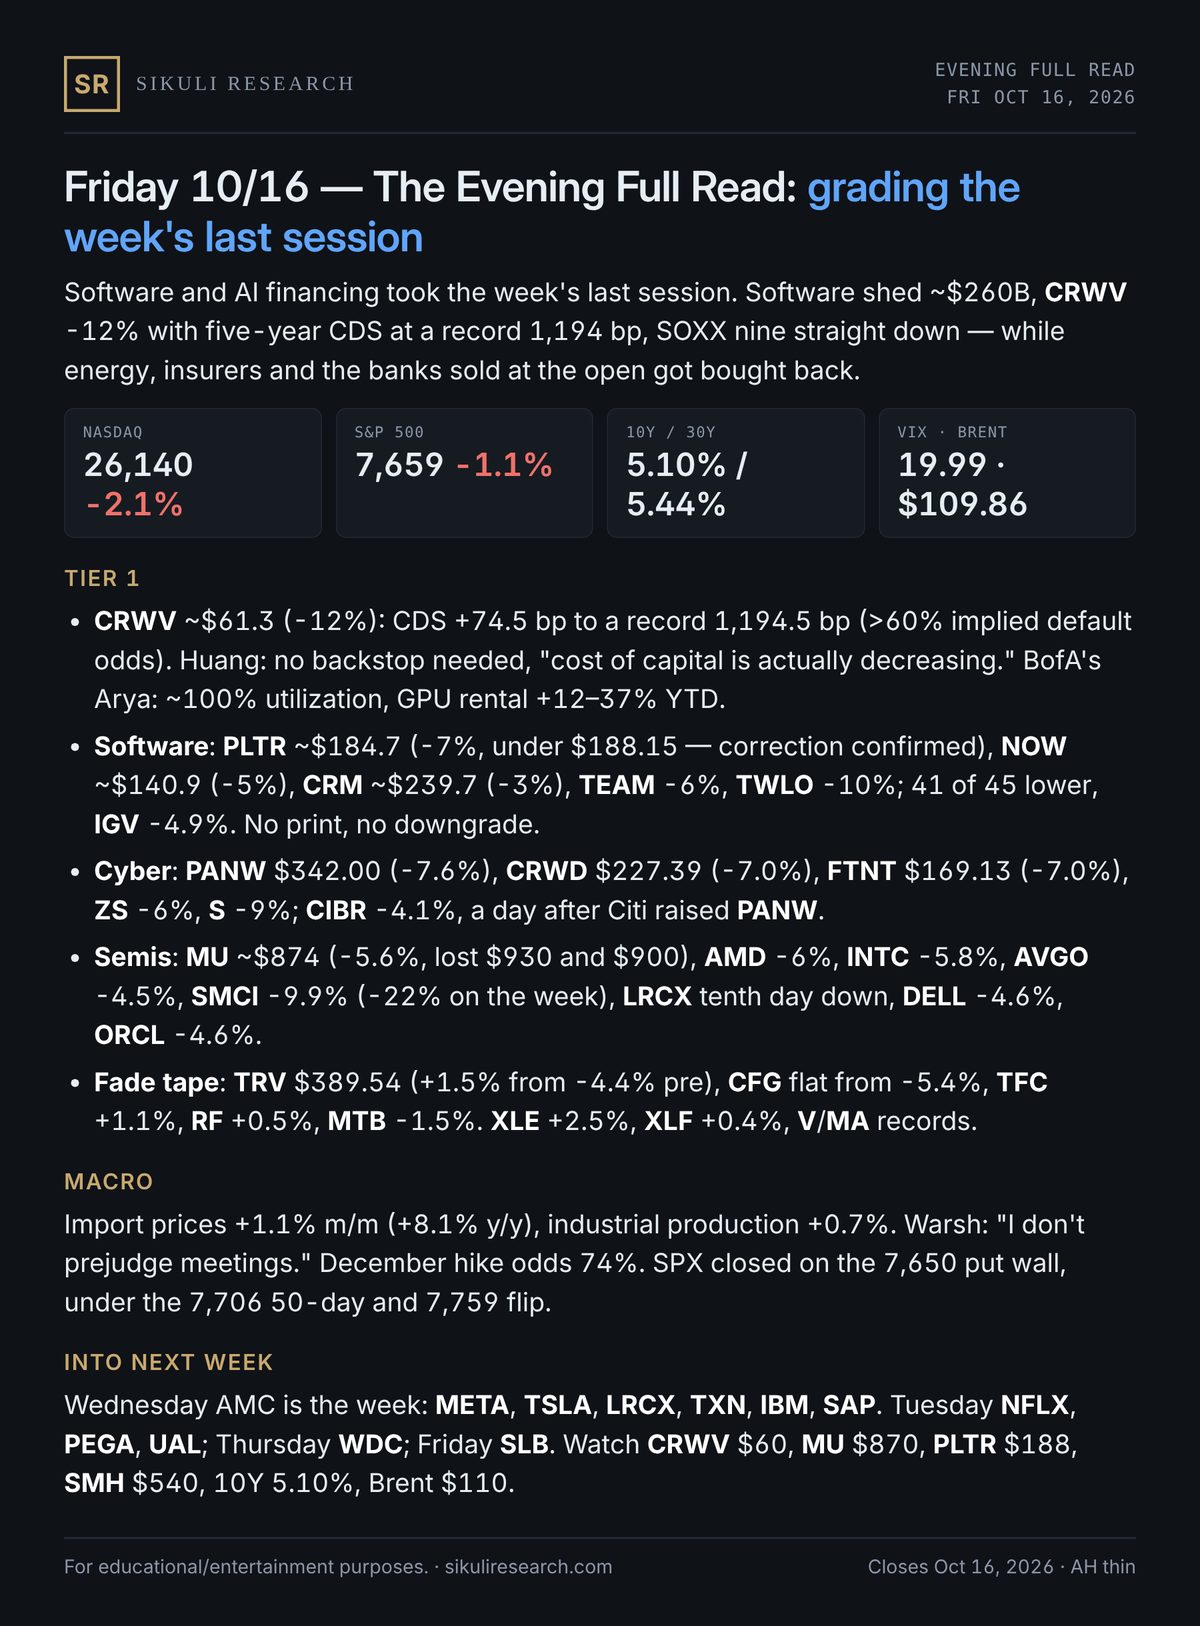
Software shed ~$260B and $CRWV fell 12% with its CDS at a record 1,194 bp; SOXX nine straight down. Energy, insurers and the banks sold at the open got bought back. Nasdaq -2.1%, worst day since June. Full read at Sikuli Research (link in bio)
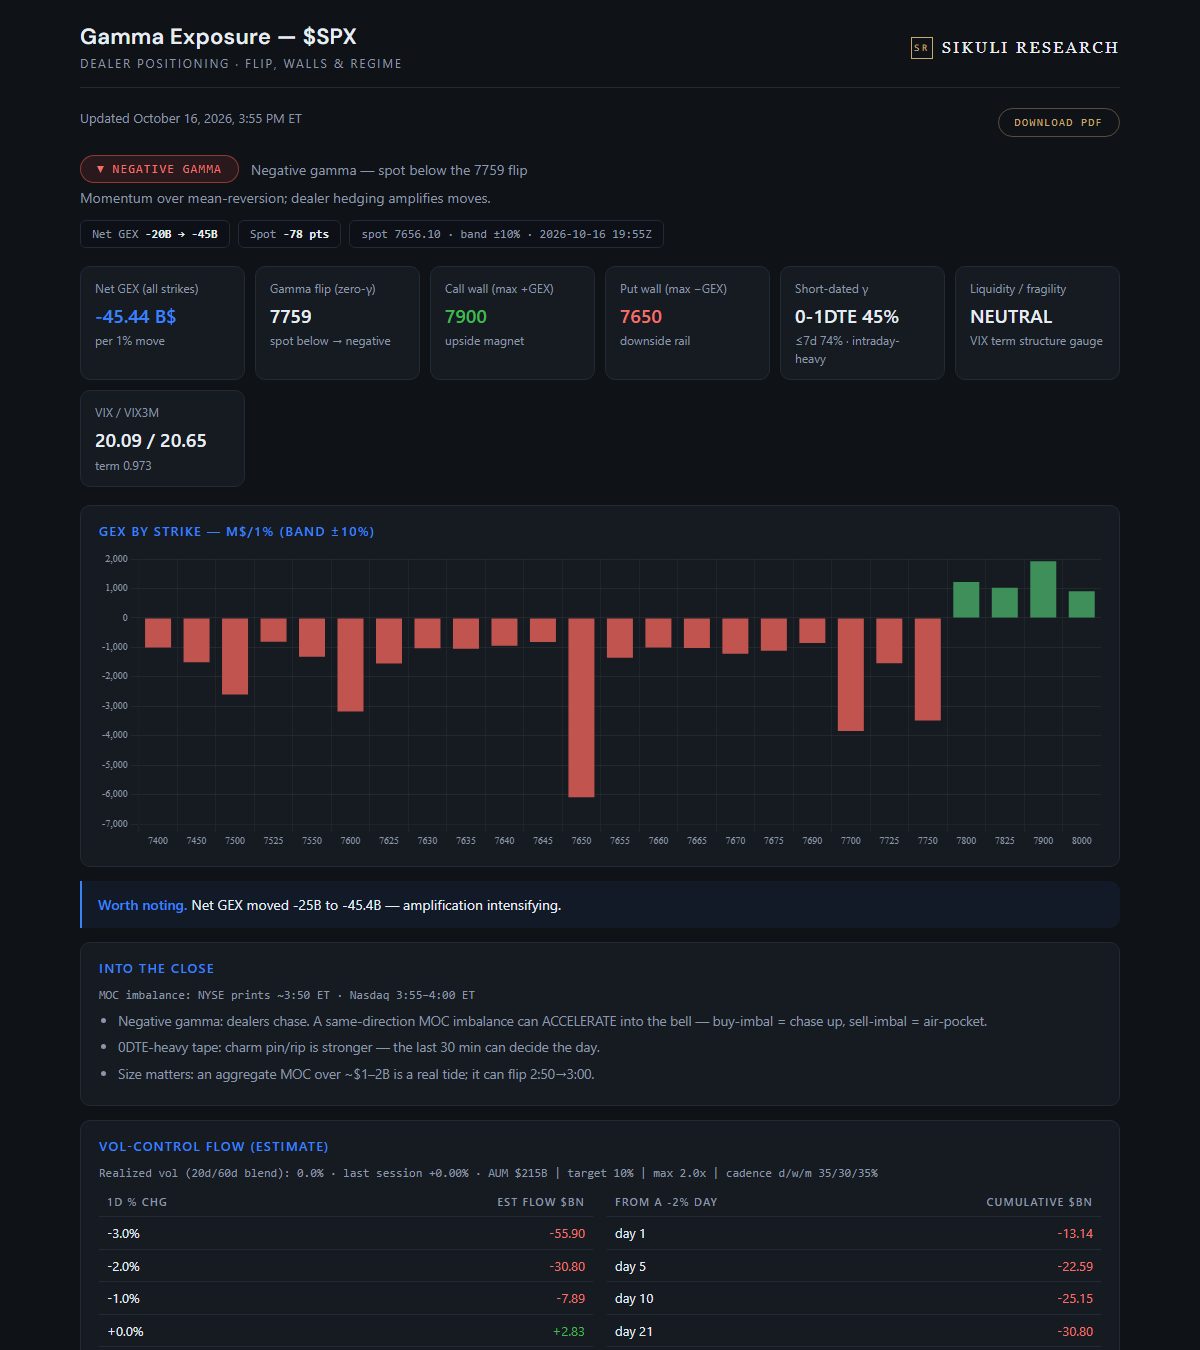
Negative gamma deepened — net GEX down to -45B; amplification intensifying. Spot 7656; walls 7900/7650; net GEX -$45.4B; VIX 20.09. $SPX #QQQ Full report at Sikuli Research (link in bio)
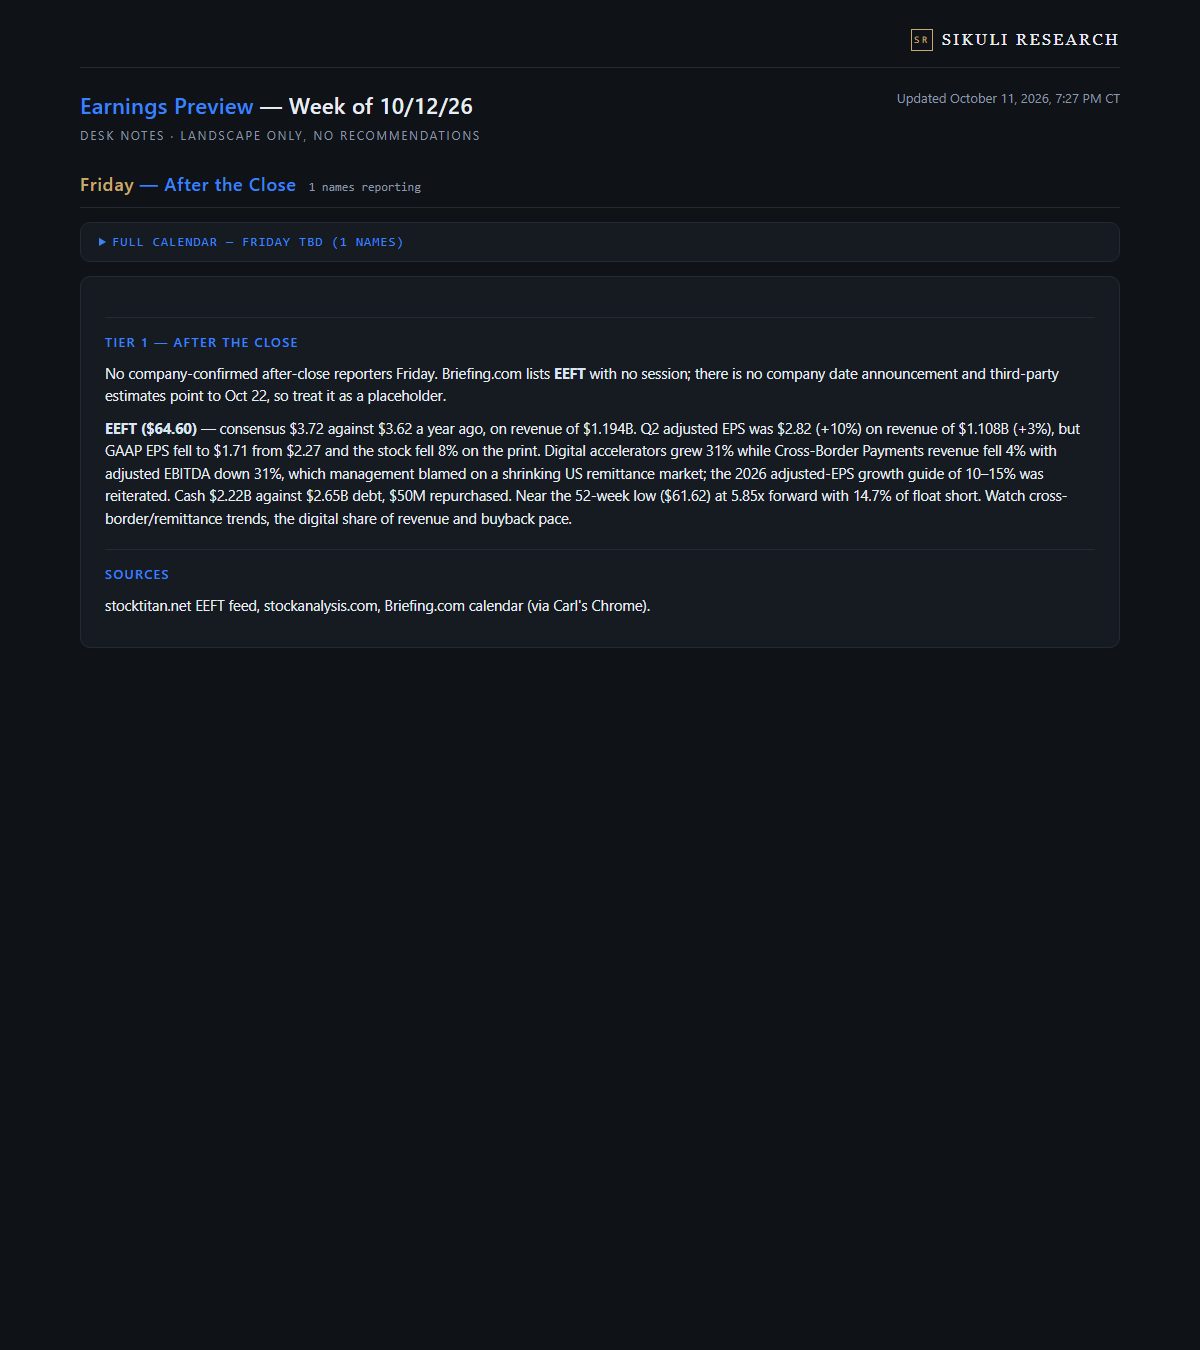
EEFT reporting. Full preview at Sikuli Research (link in bio) $EEFT
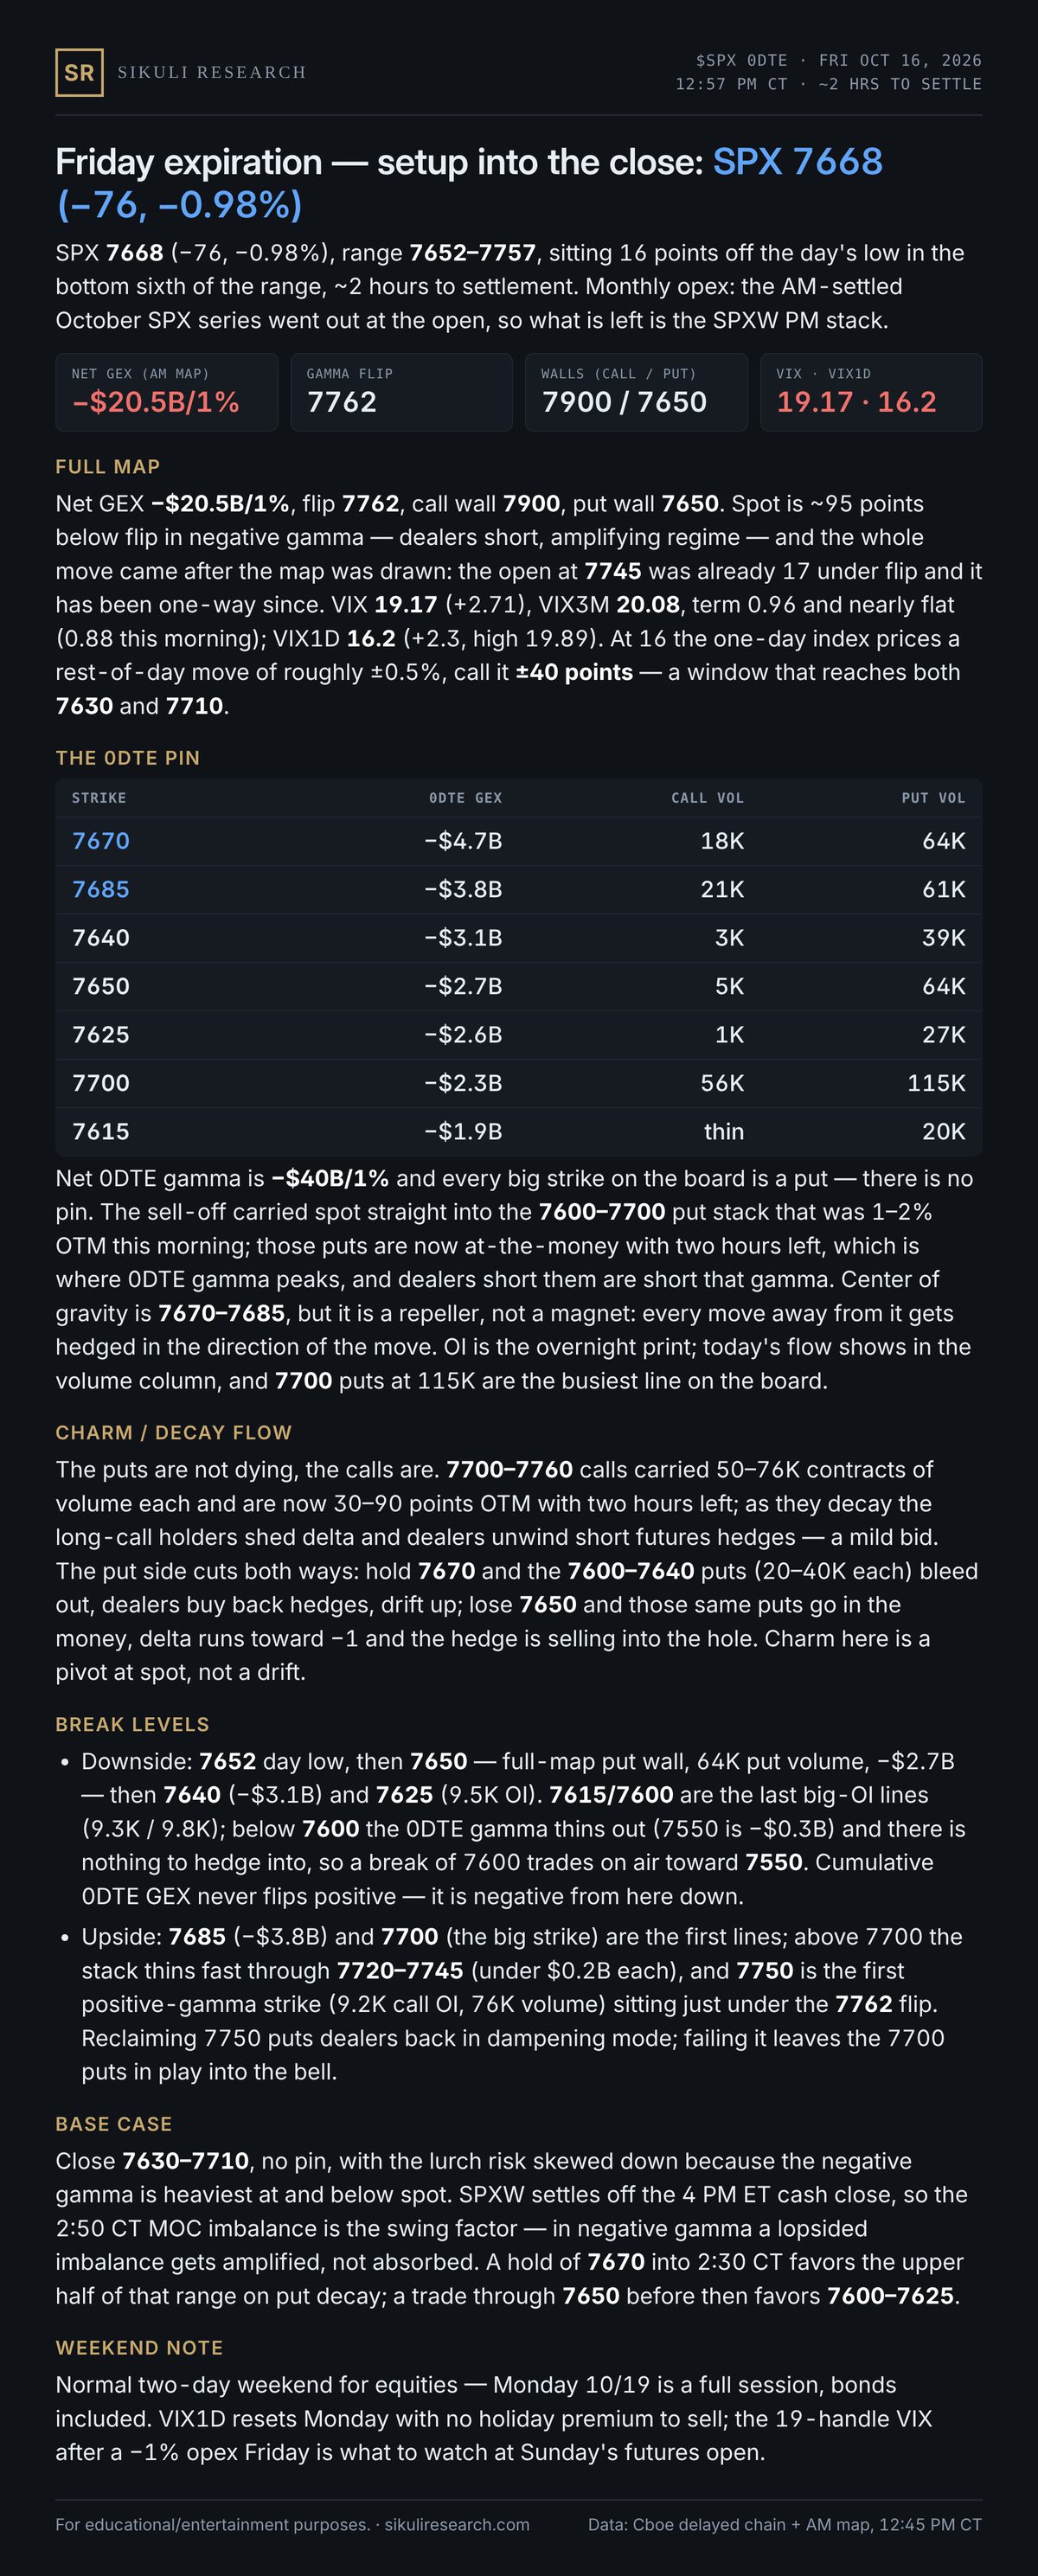
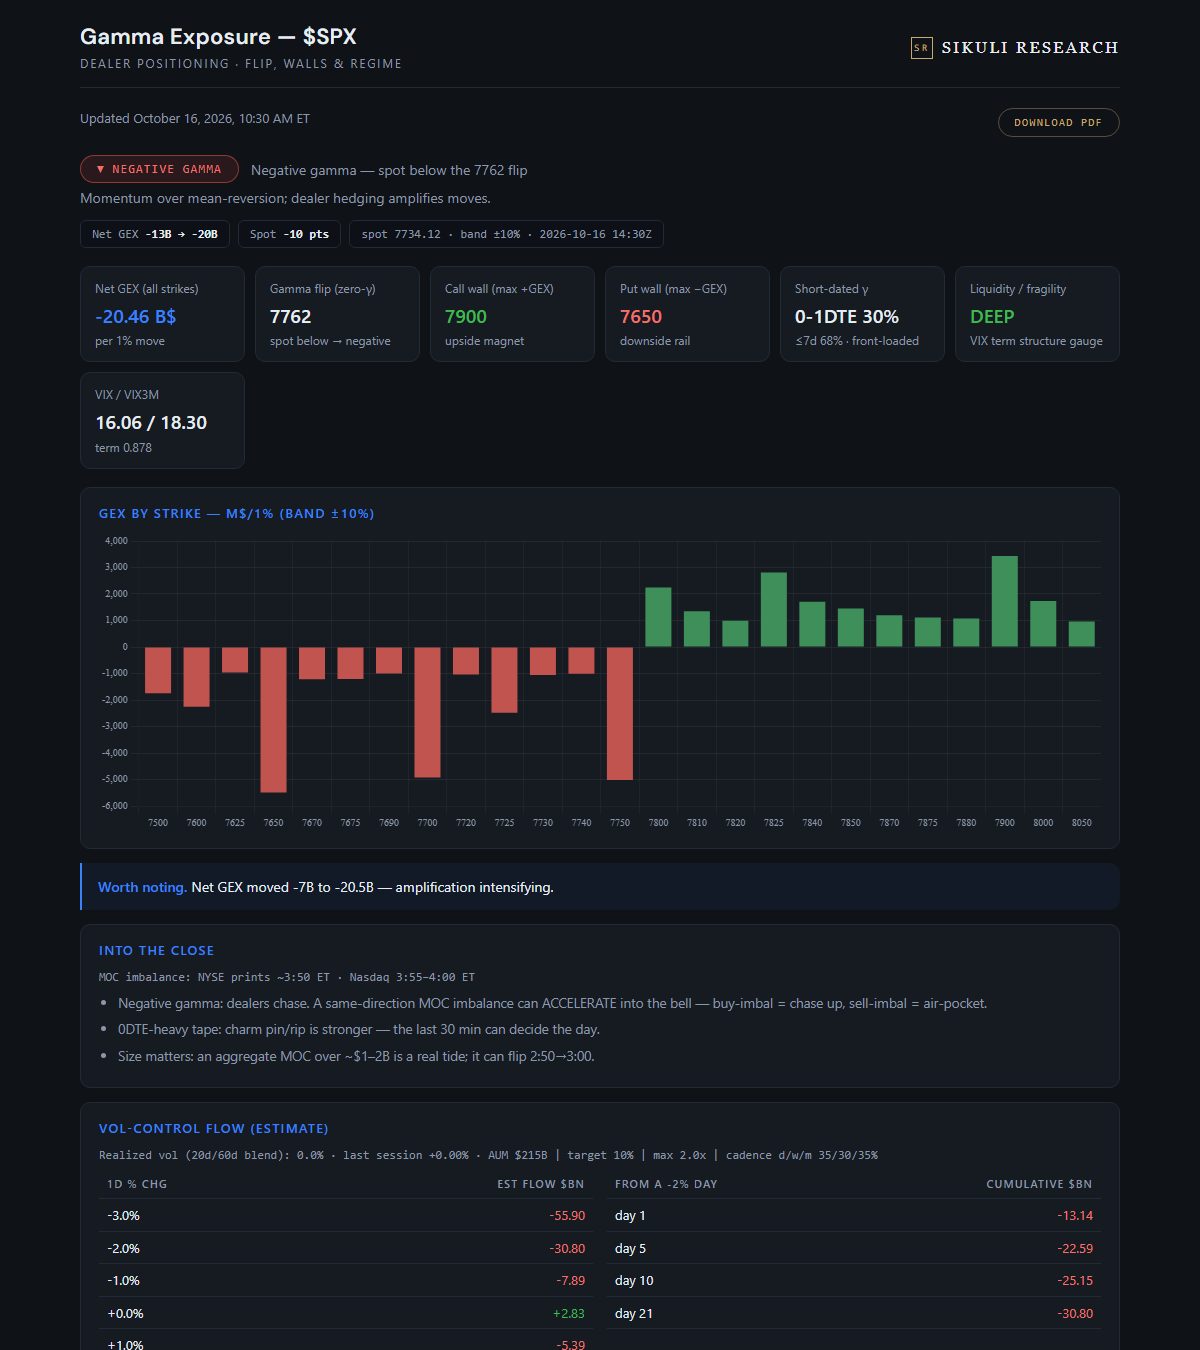
Negative gamma deepened — net GEX down to -20B; amplification intensifying; liquidity is deep, which tends to absorb dips. Spot 7734; walls 7900/7650; net GEX -$20.5B; VIX 16.06. $SPX #QQQ Full report at Sikuli Research (link in bio)
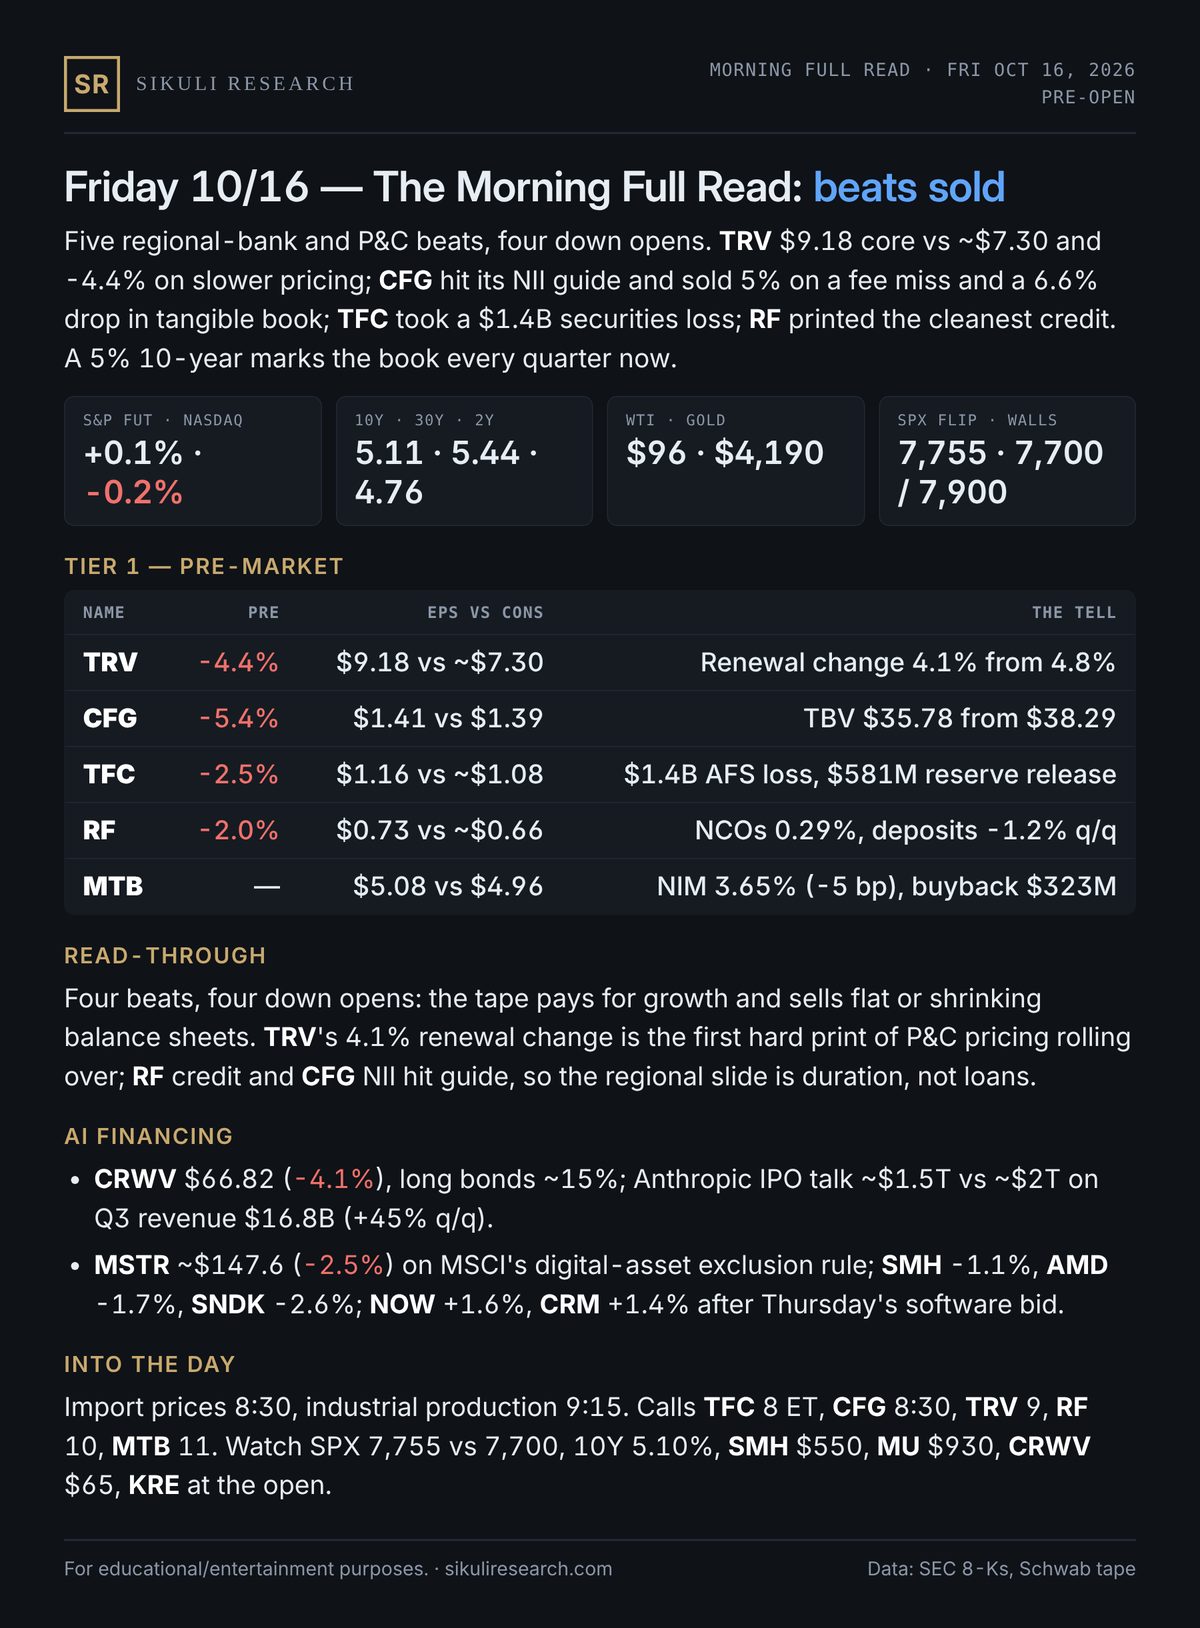
Five bank/P&C beats, four down opens: $TRV $9.18 core sold on slower pricing, CFG fell 5% on tangible book, TFC took a $1.4B securities loss. A 5% 10-year marks the book every quarter now. Full read at Sikuli Research (link in bio)
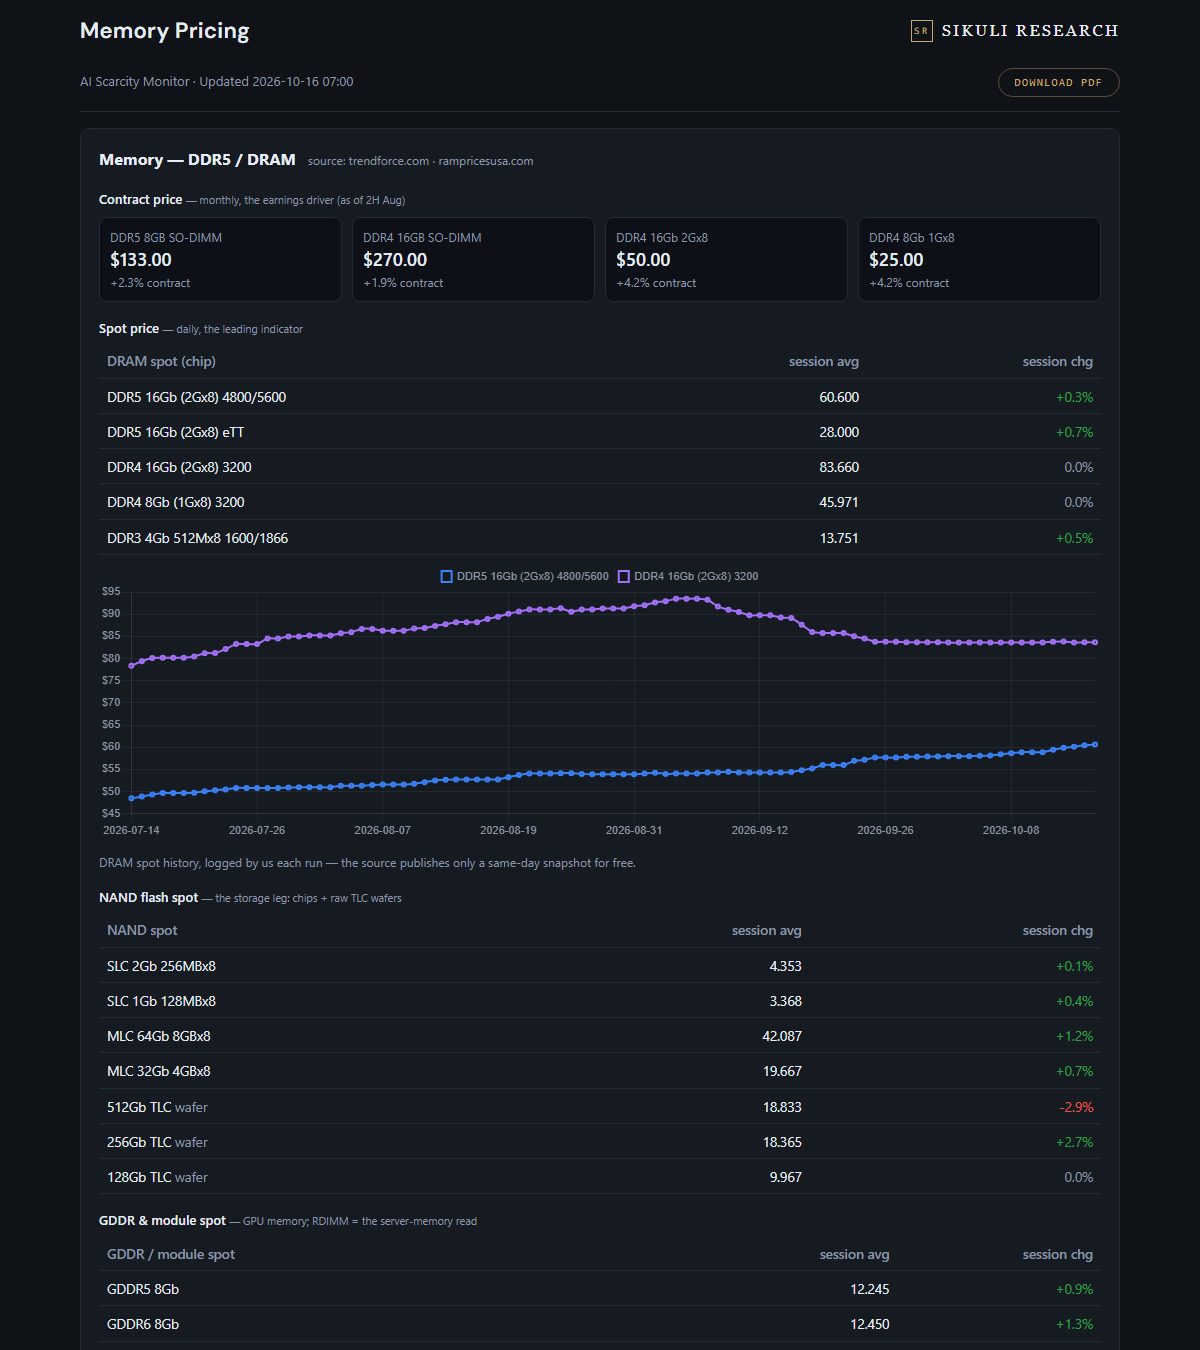
DDR5 8GB SO-DIMM contract $133.00 (+2.3%, 2H Aug) DDR5 16Gb (2Gx8) 4800/5600 spot $60.60 (+0.3%) DDR4 16Gb 2Gx8 $50.00 (+4.2%) Retail DDR5 $18.59/GB $QQQ #SPX Full report at Sikuli Research (link in bio)
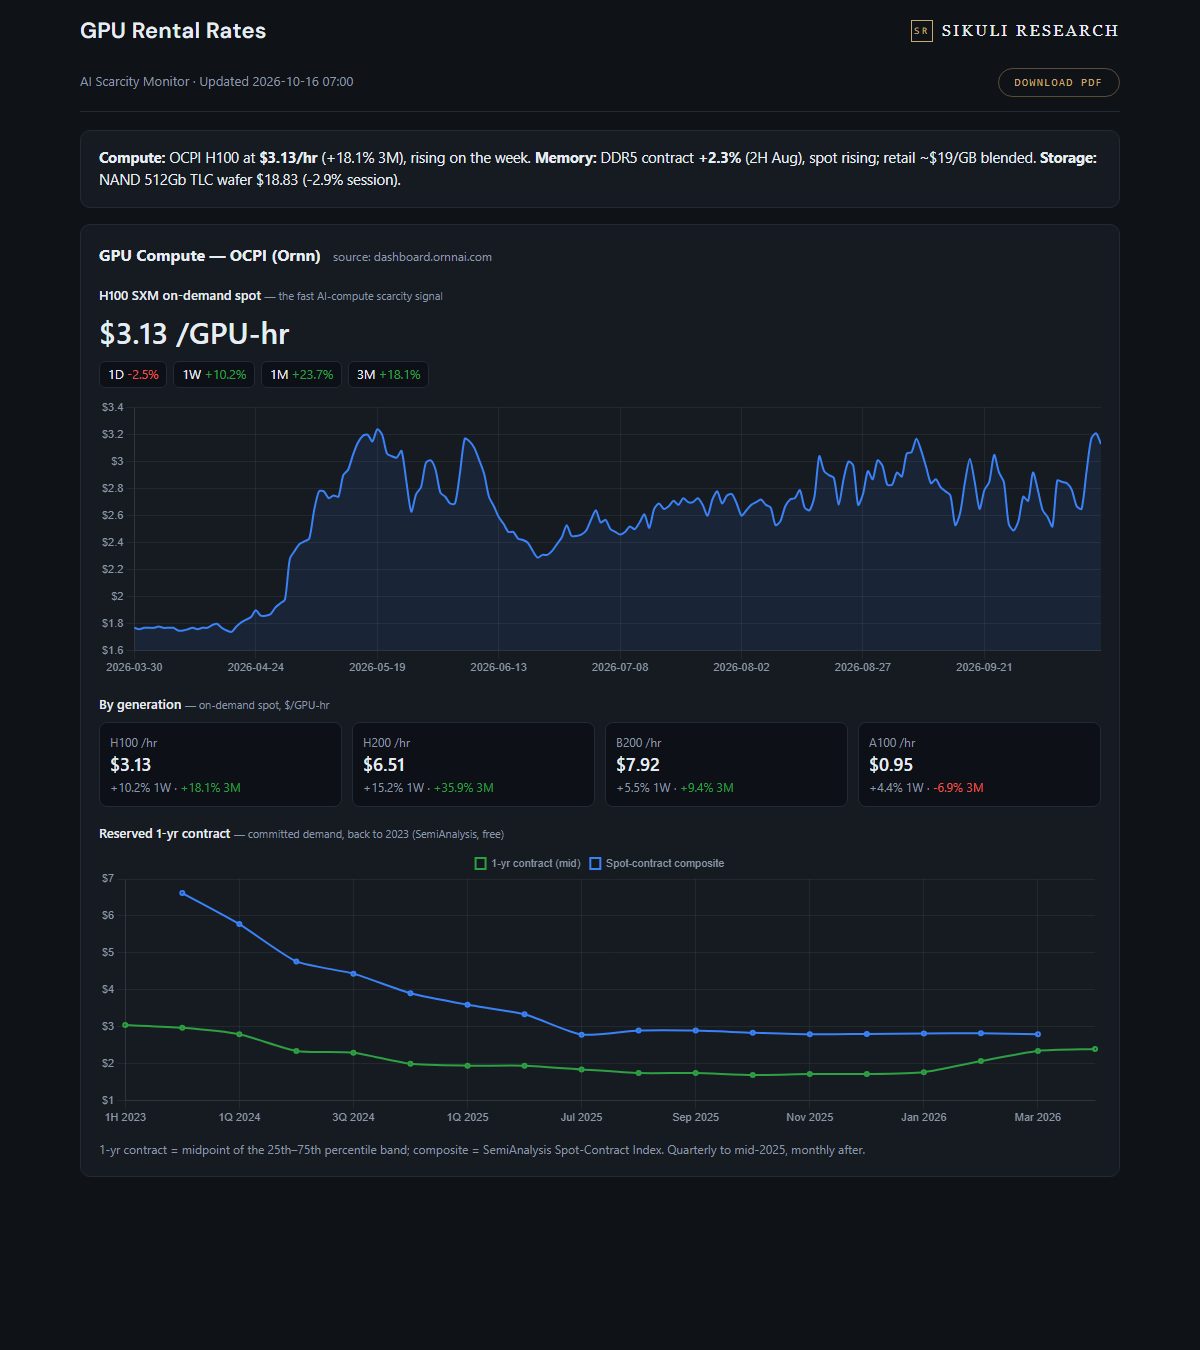
H100 $3.13/hr (1D -2.5% | 1W +10.2% | 1M +23.7% | 3M +18.1%) H200 $6.51 | B200 $7.92 | A100 $0.95 $QQQ #SPX Full report at Sikuli Research (link in bio)
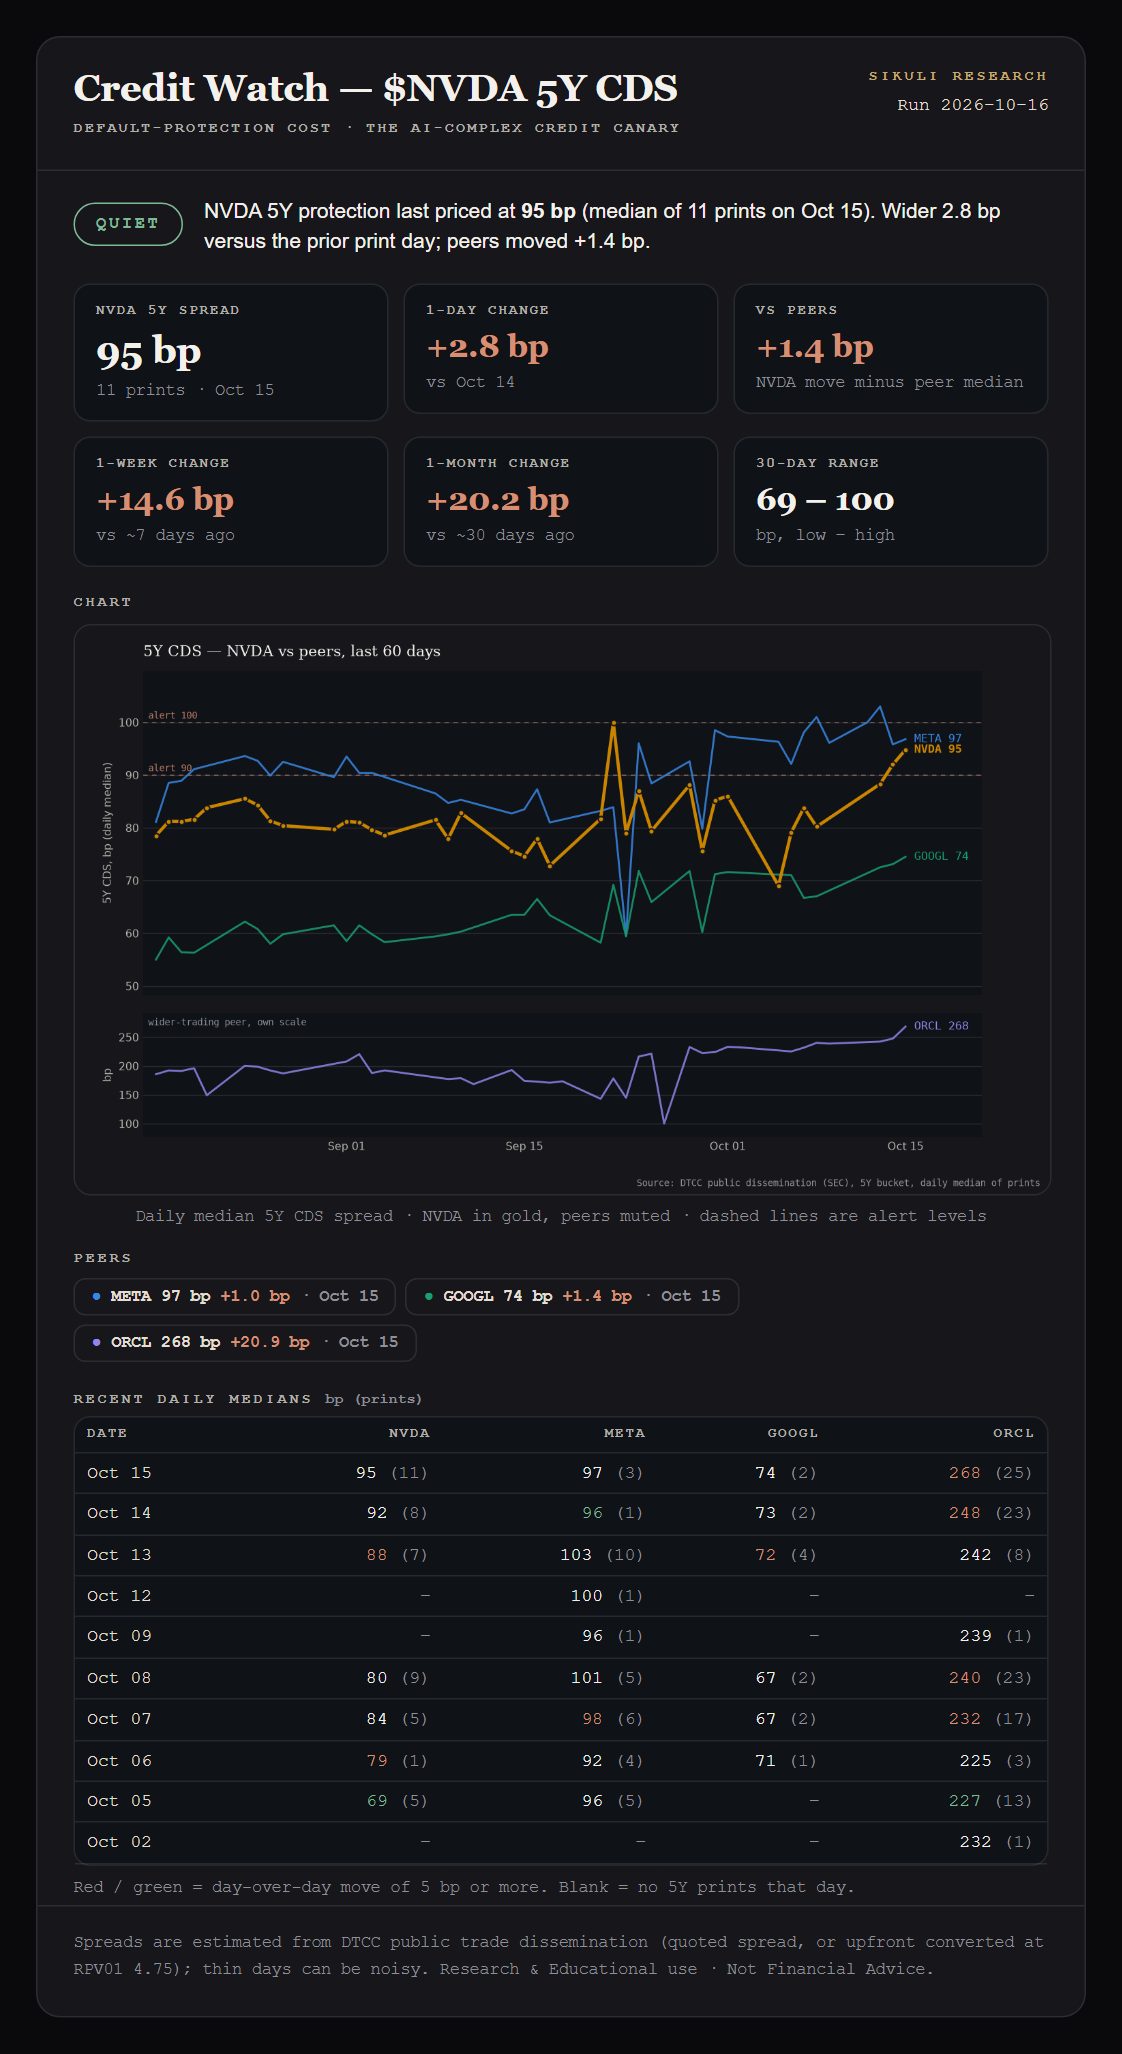
11 prints, Oct 15. Peers: META 97, GOOGL 74, ORCL 268. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
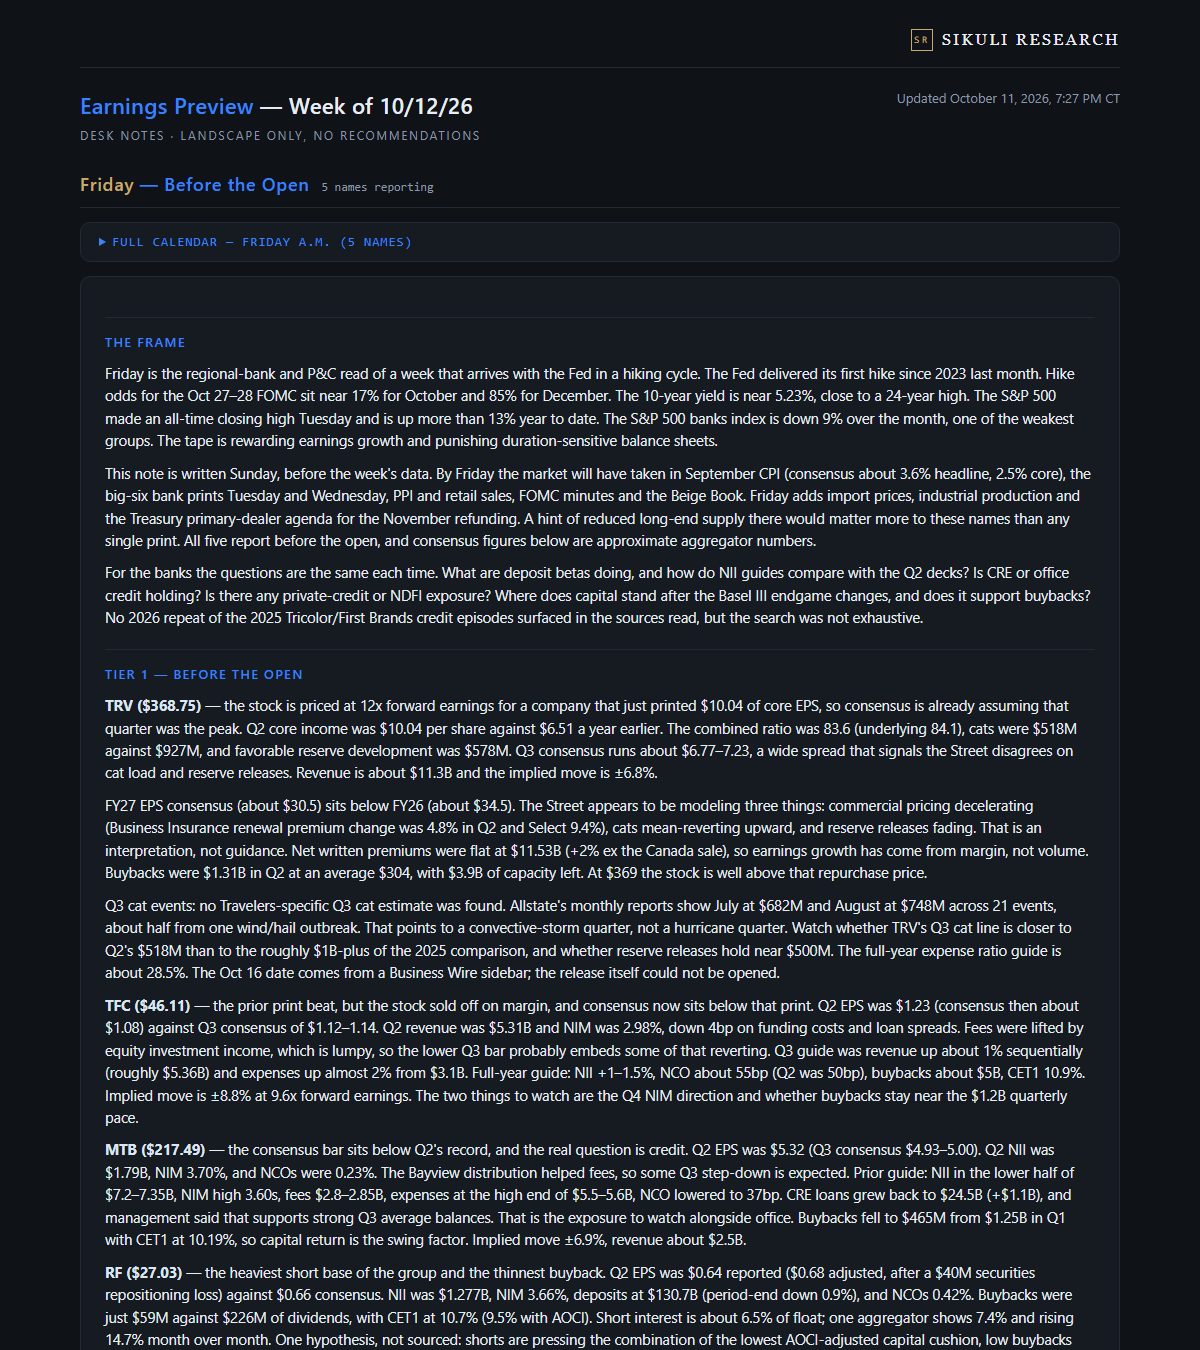
TRV, TFC, MTB, CFG, RF reporting. Full preview at Sikuli Research (link in bio) $TRV
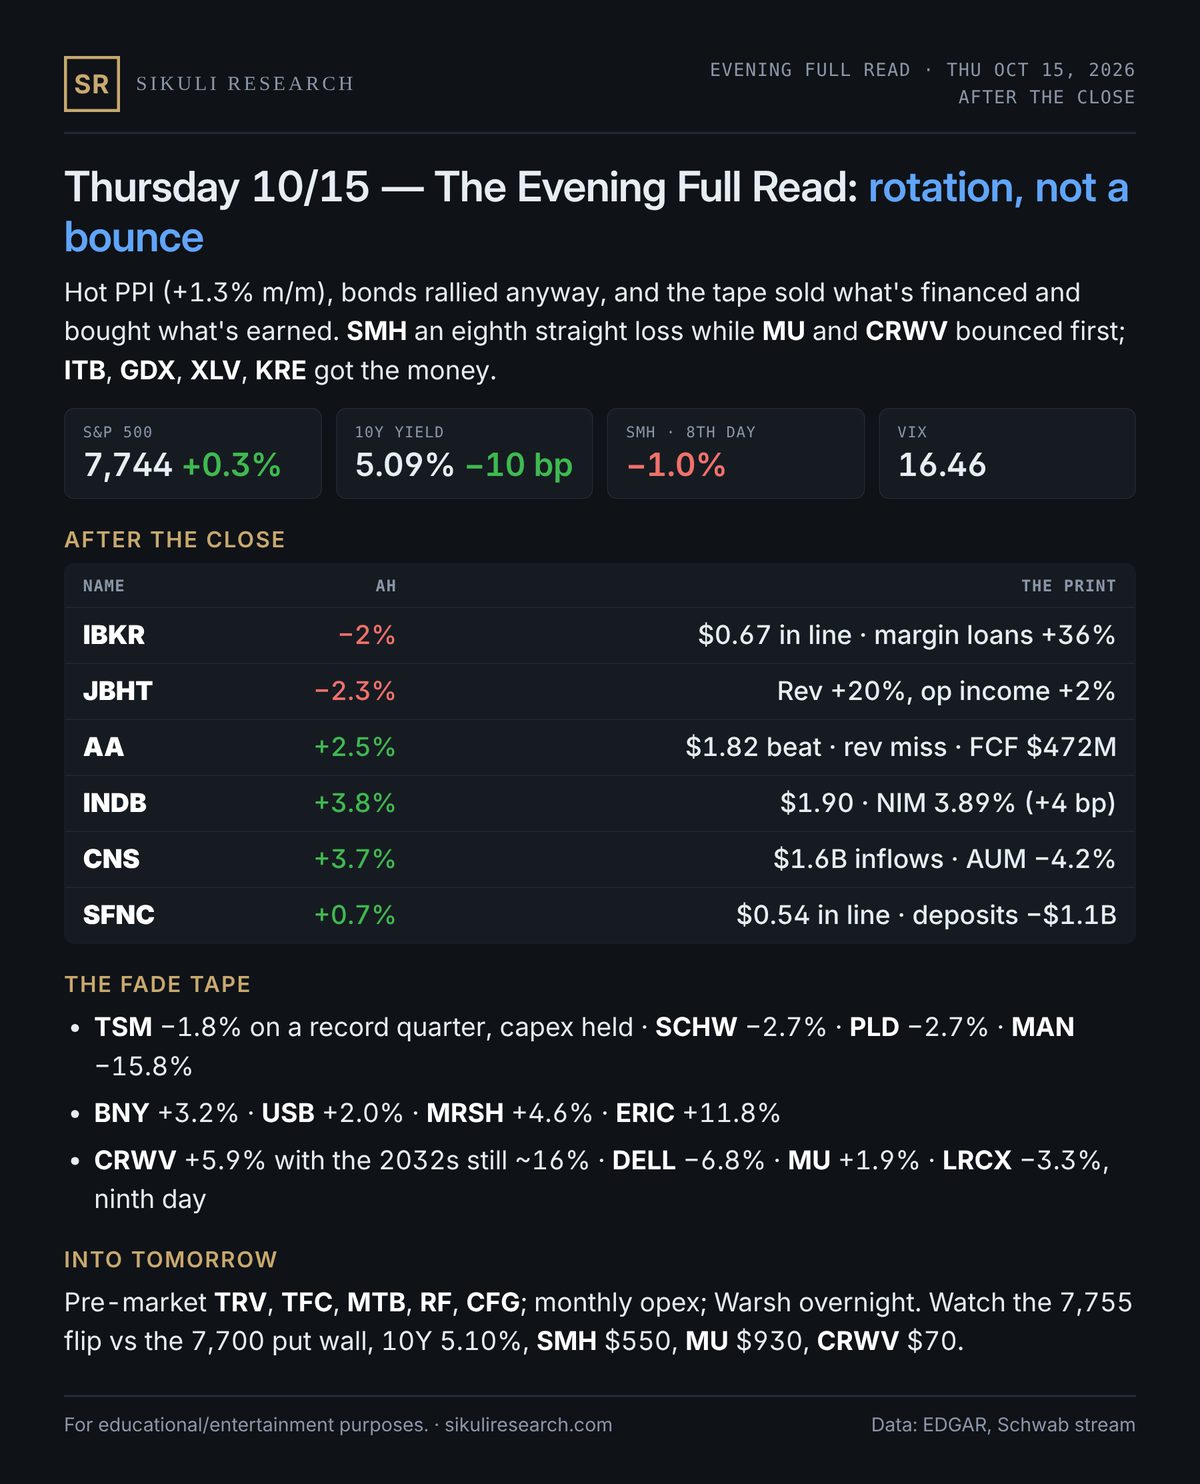
Hot PPI, bonds rallied anyway; the tape sold what's financed and bought what's earned. SMH an eighth straight loss while MU and CoreWeave bounced first. IBKR in line, JBHT margins squeezed, Alcoa beat. Full read at Sikuli Research (link in bio)
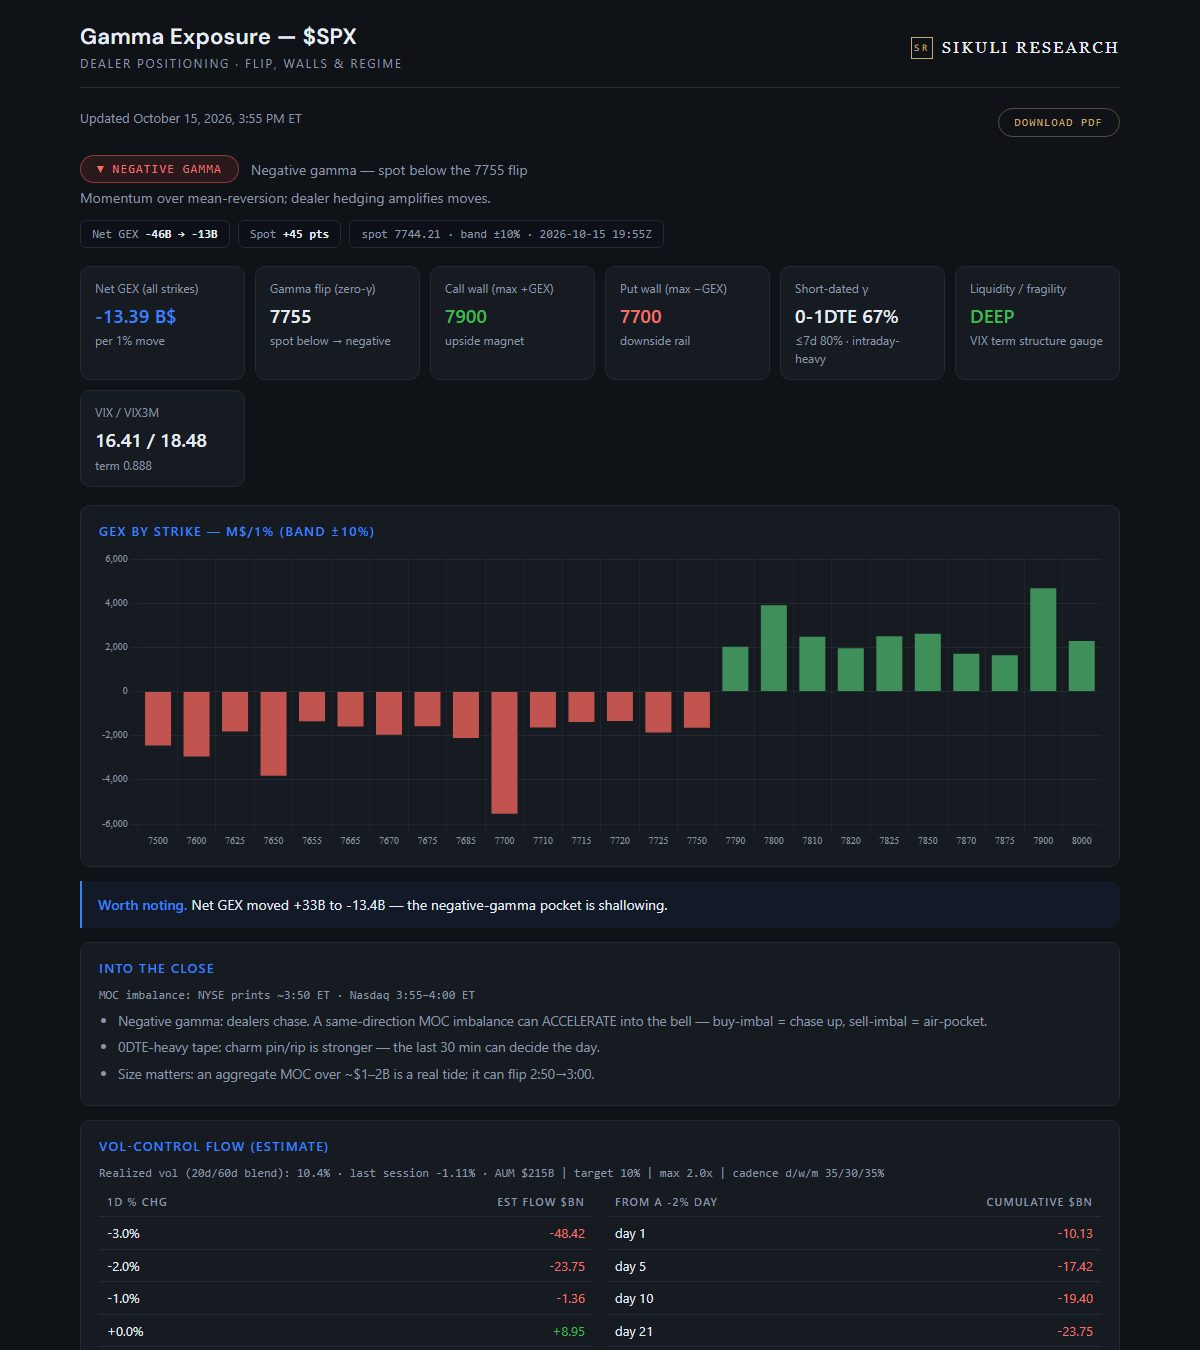
Negative gamma but easing — net GEX less negative; pressure coming off; liquidity is deep, which tends to absorb dips. Spot 7744; walls 7900/7700; net GEX -$13.4B; VIX 16.41. $SPX #QQQ Full report at Sikuli Research (link in bio)
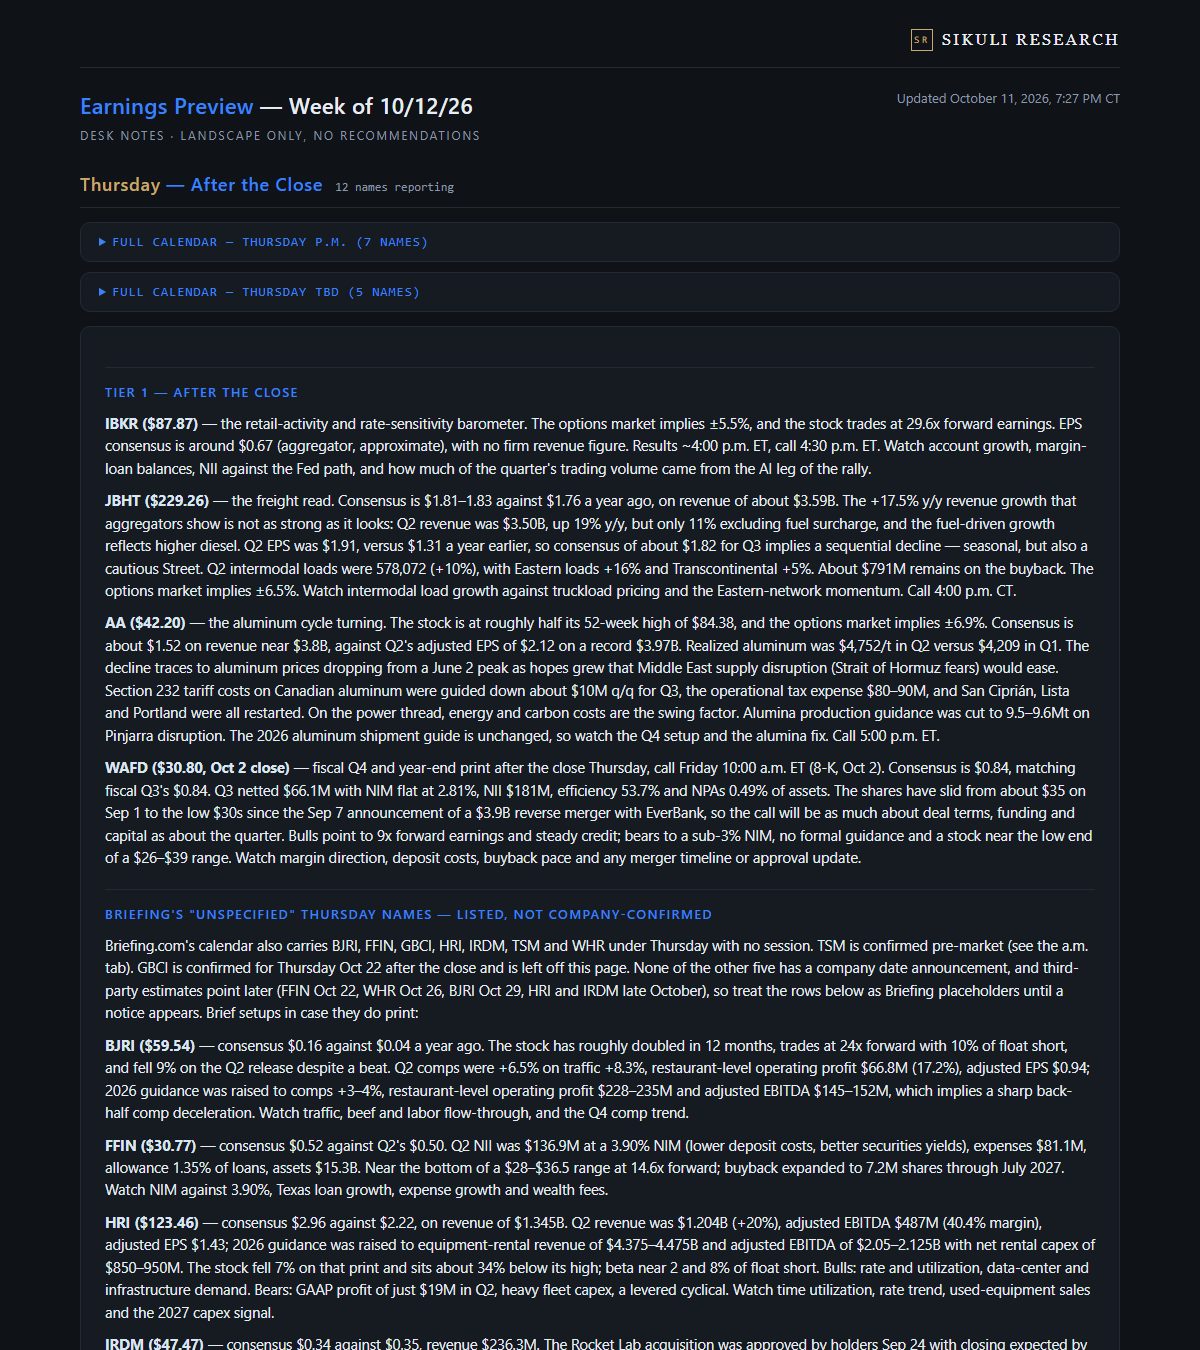
IBKR, JBHT, AA, IRDM, FFIN + 7 more reporting. Full preview at Sikuli Research (link in bio) $IBKR
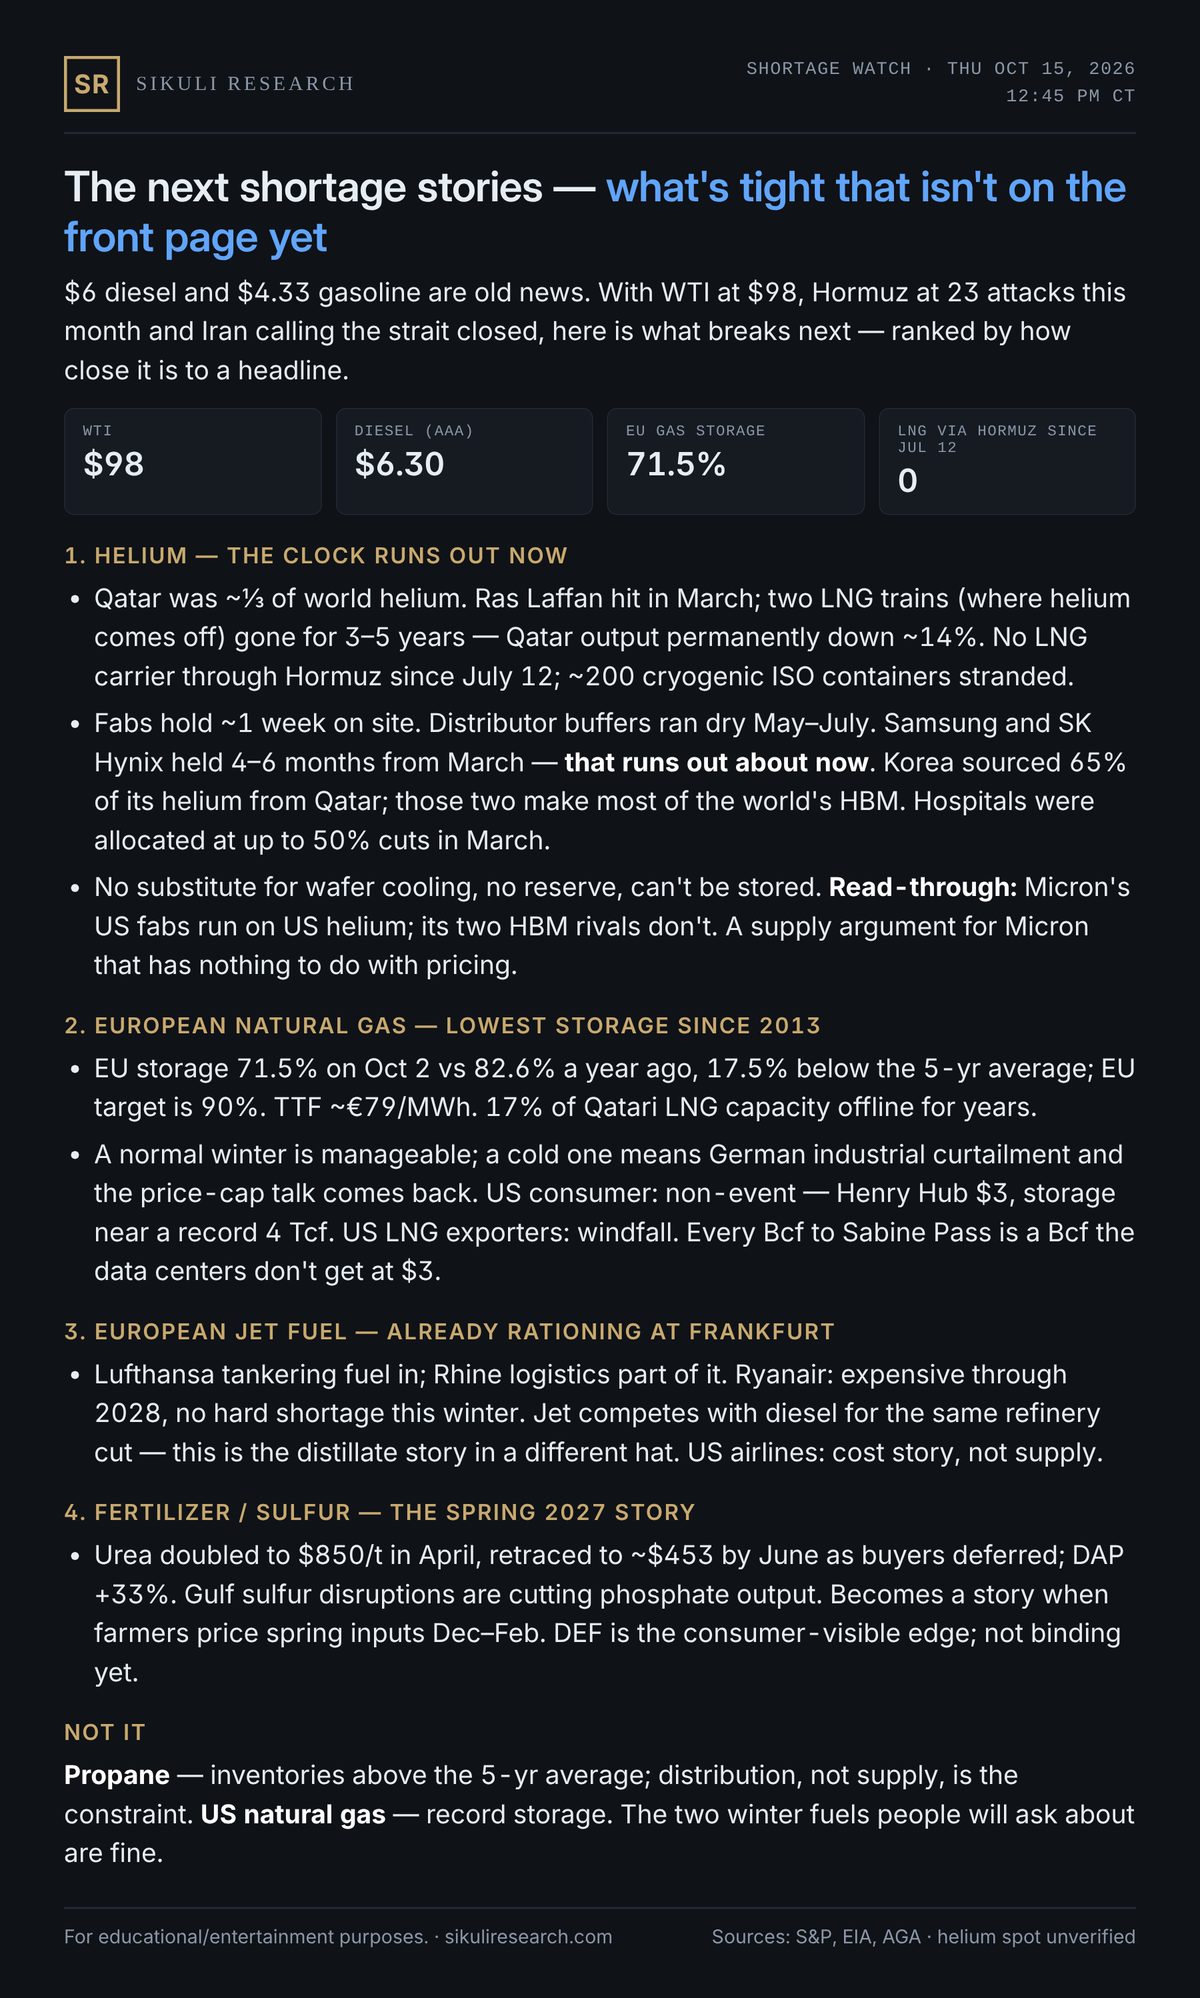
1. Helium: Qatar was ⅓ of supply, nothing through Hormuz since July, Korean fab buffers run out about now. Micron runs on US helium; its HBM rivals don't. 2. EU gas storage. 3. Frankfurt jet fuel. 4. Fertilizer. $MU
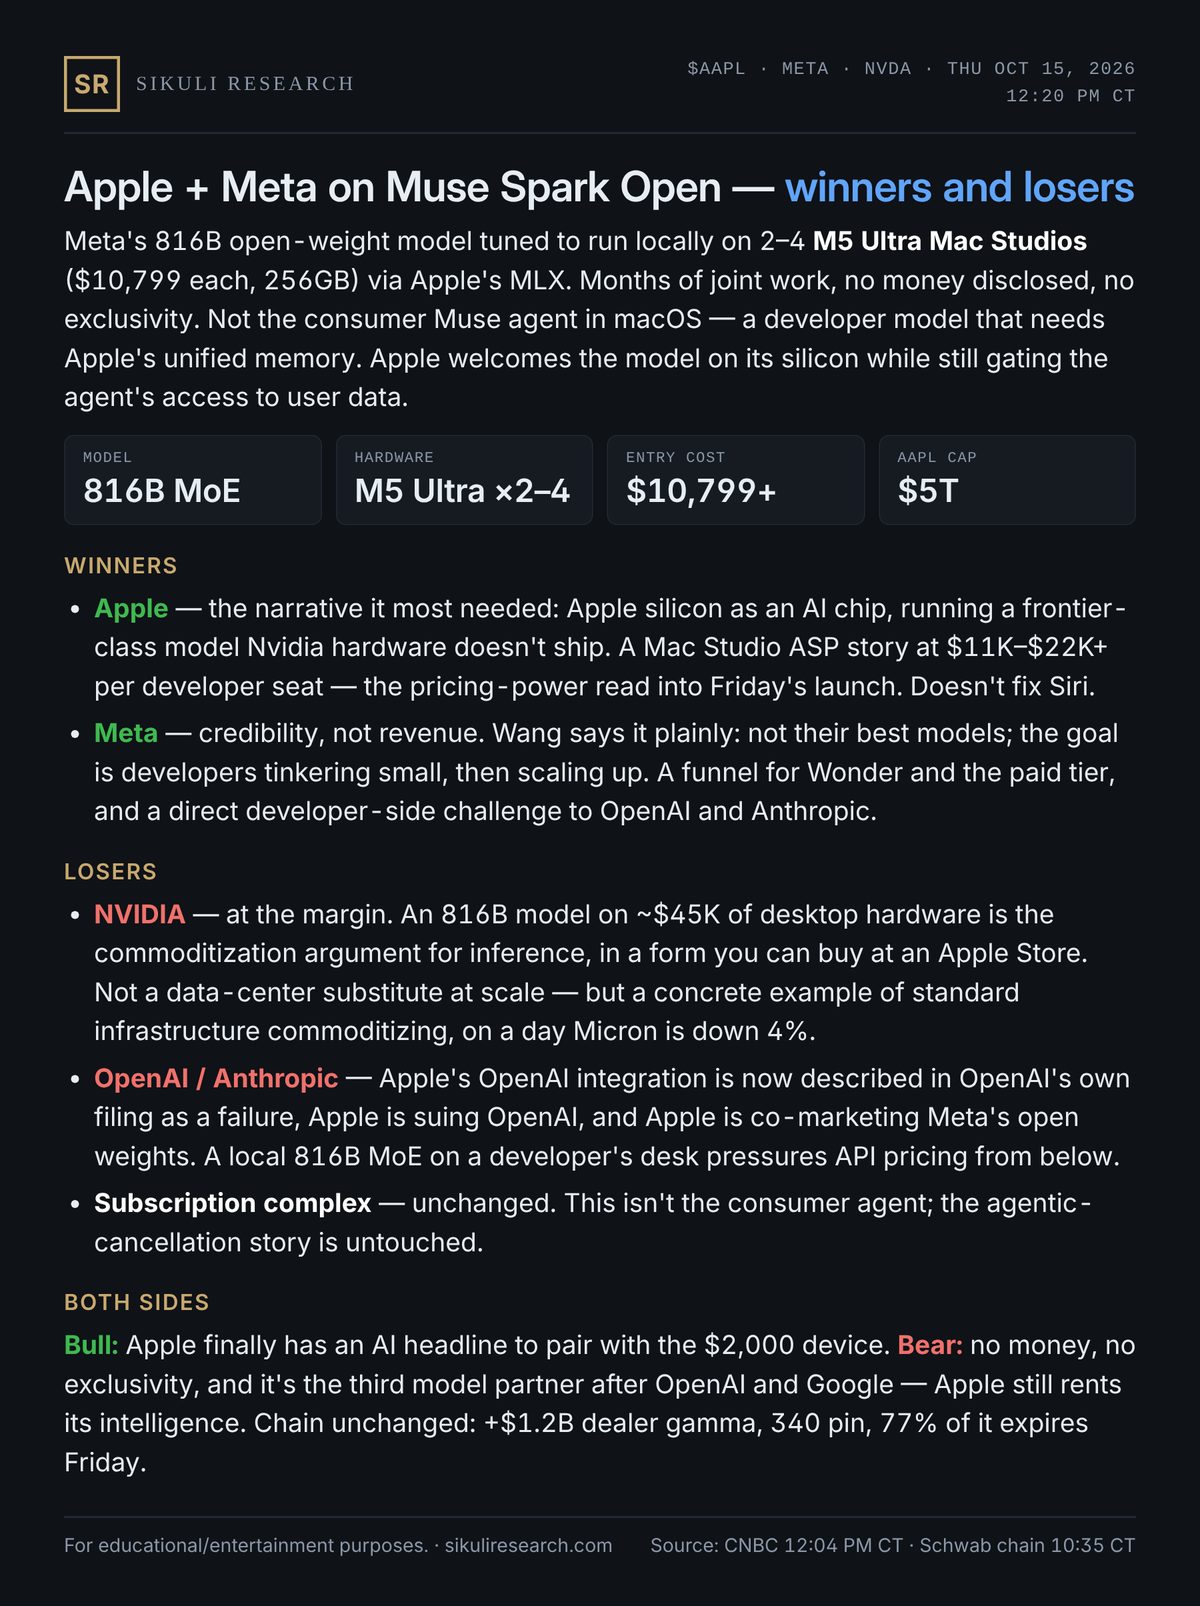
816B open-weight model running locally on 2–4 M5 Ultra Mac Studios. Not the consumer agent — a developer model that needs Apple's memory. Winners: Apple, Meta. Losers at the margin: NVDA, OpenAI/Anthropic. $AAPL
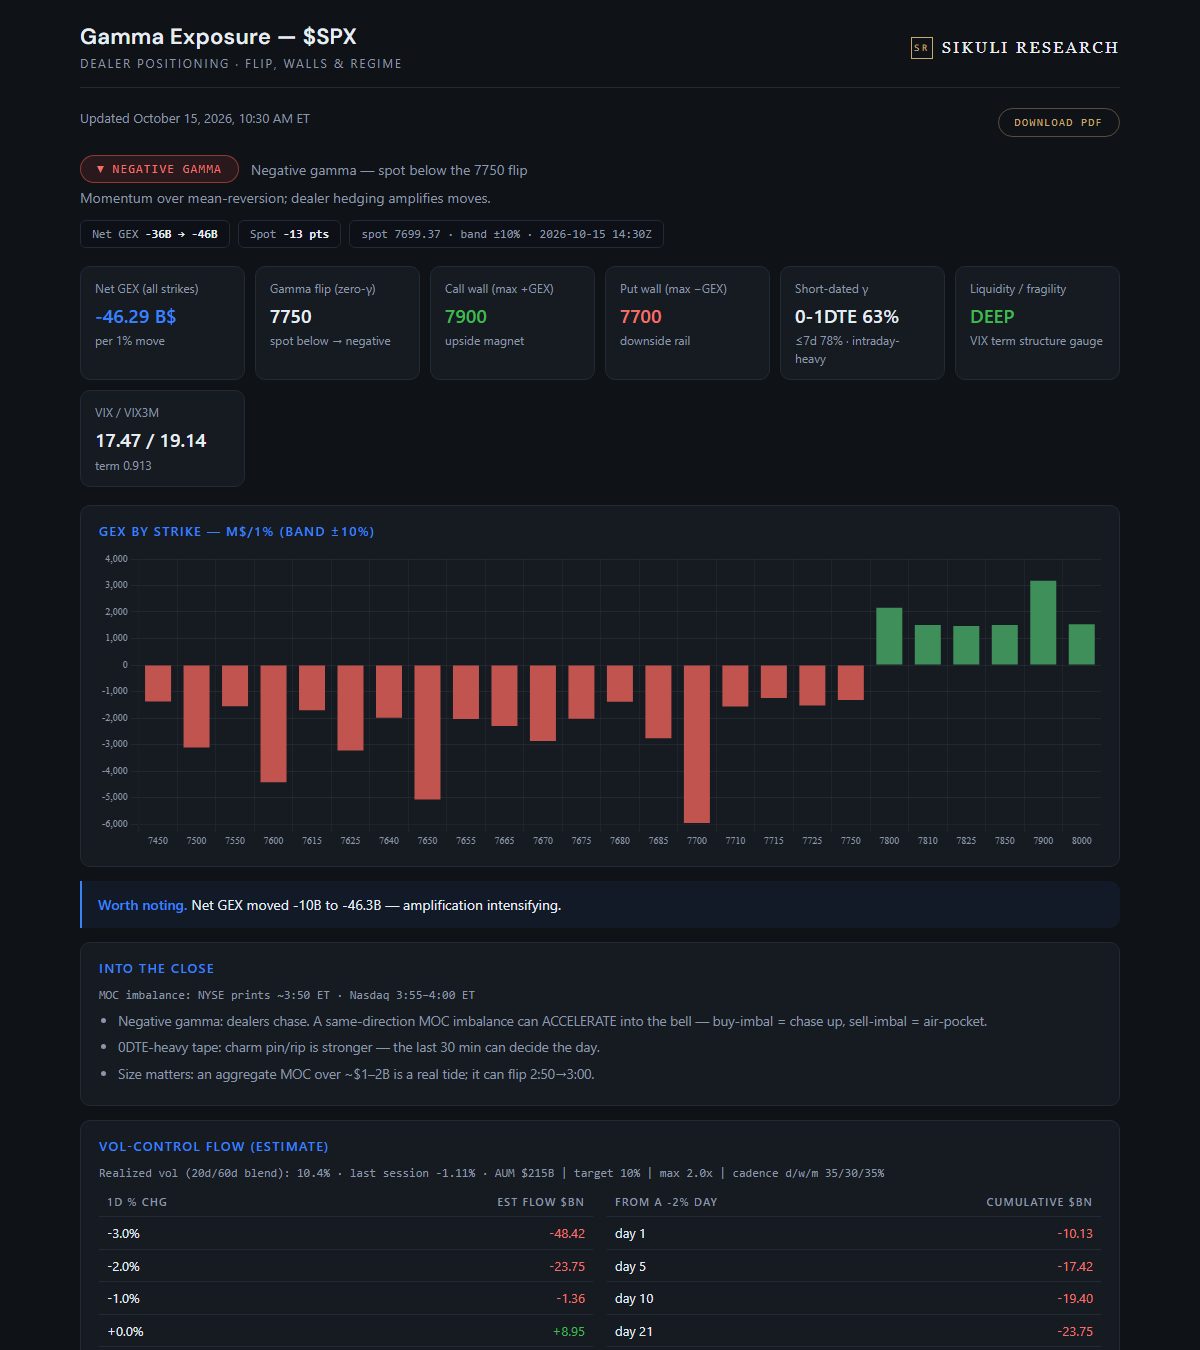
Negative gamma deepened — net GEX down to -46B; amplification intensifying; liquidity is deep, which tends to absorb dips. Spot 7699; walls 7900/7700; net GEX -$46.3B; VIX 17.47. $SPX #QQQ Full report at Sikuli Research (link in bio)
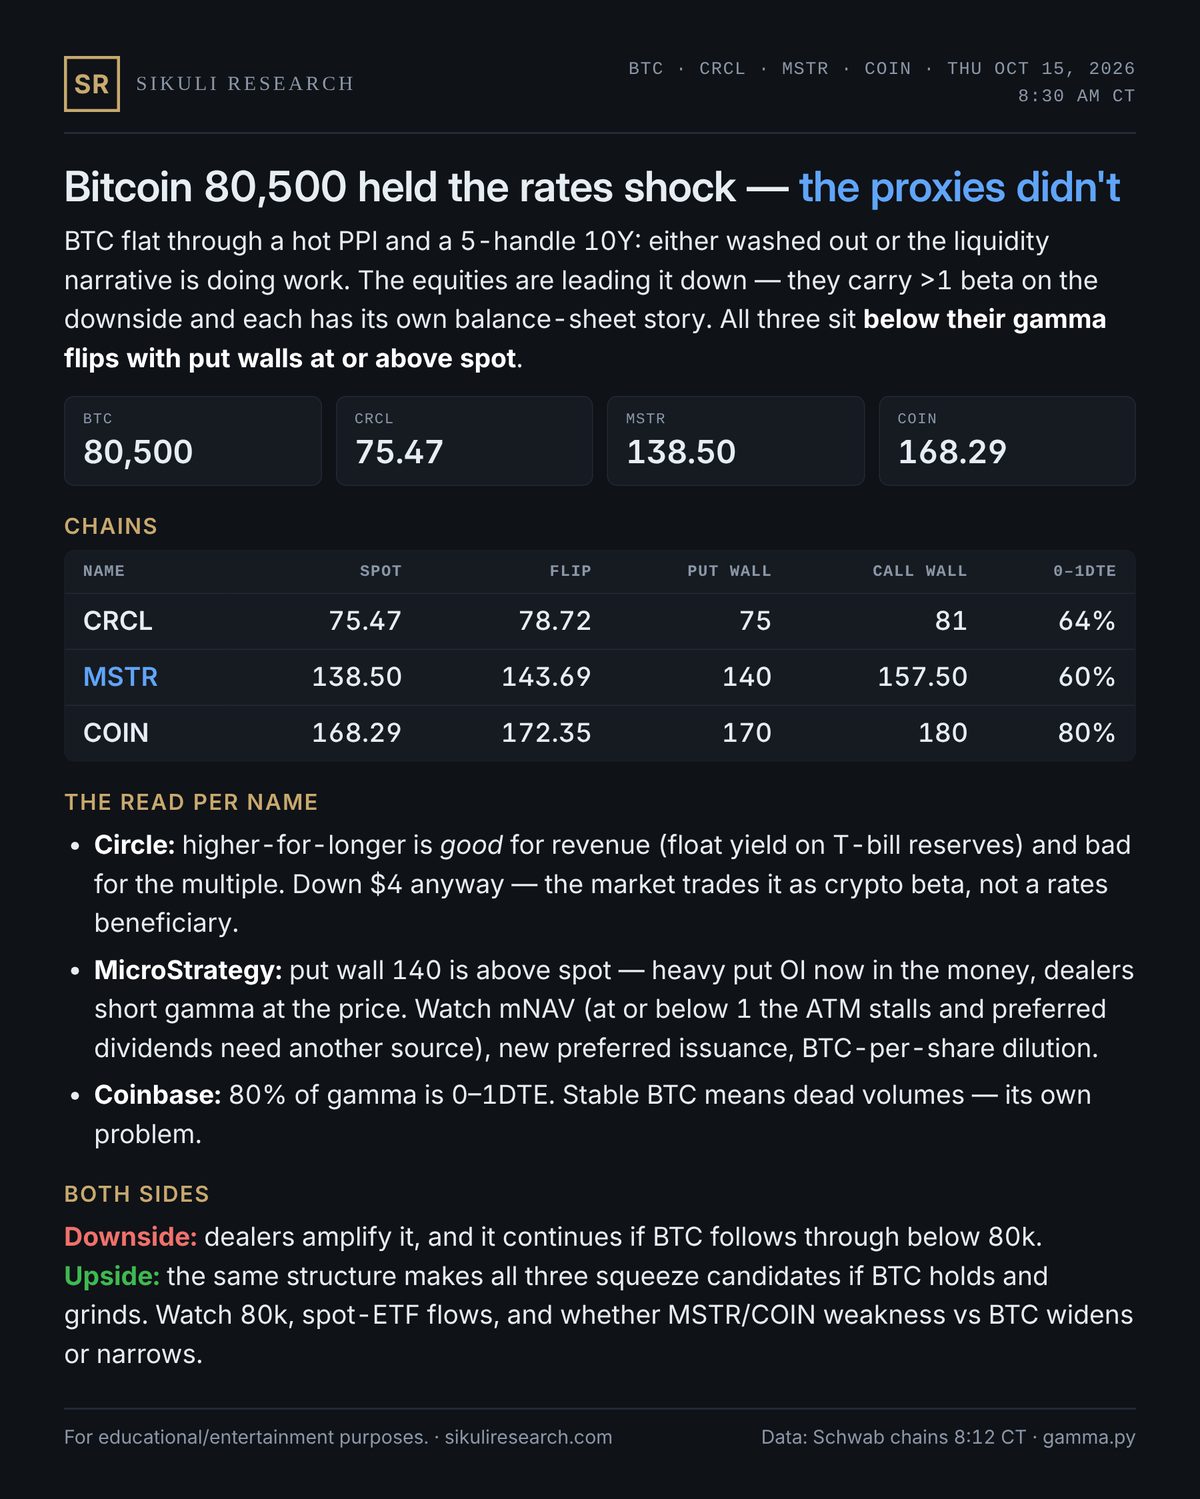
CRCL 75, MSTR 138, COIN 168 — all below their gamma flips, put walls at or above spot. Dealers amplify the downside if BTC loses 80k; if it holds, the same structure squeezes. $MSTR
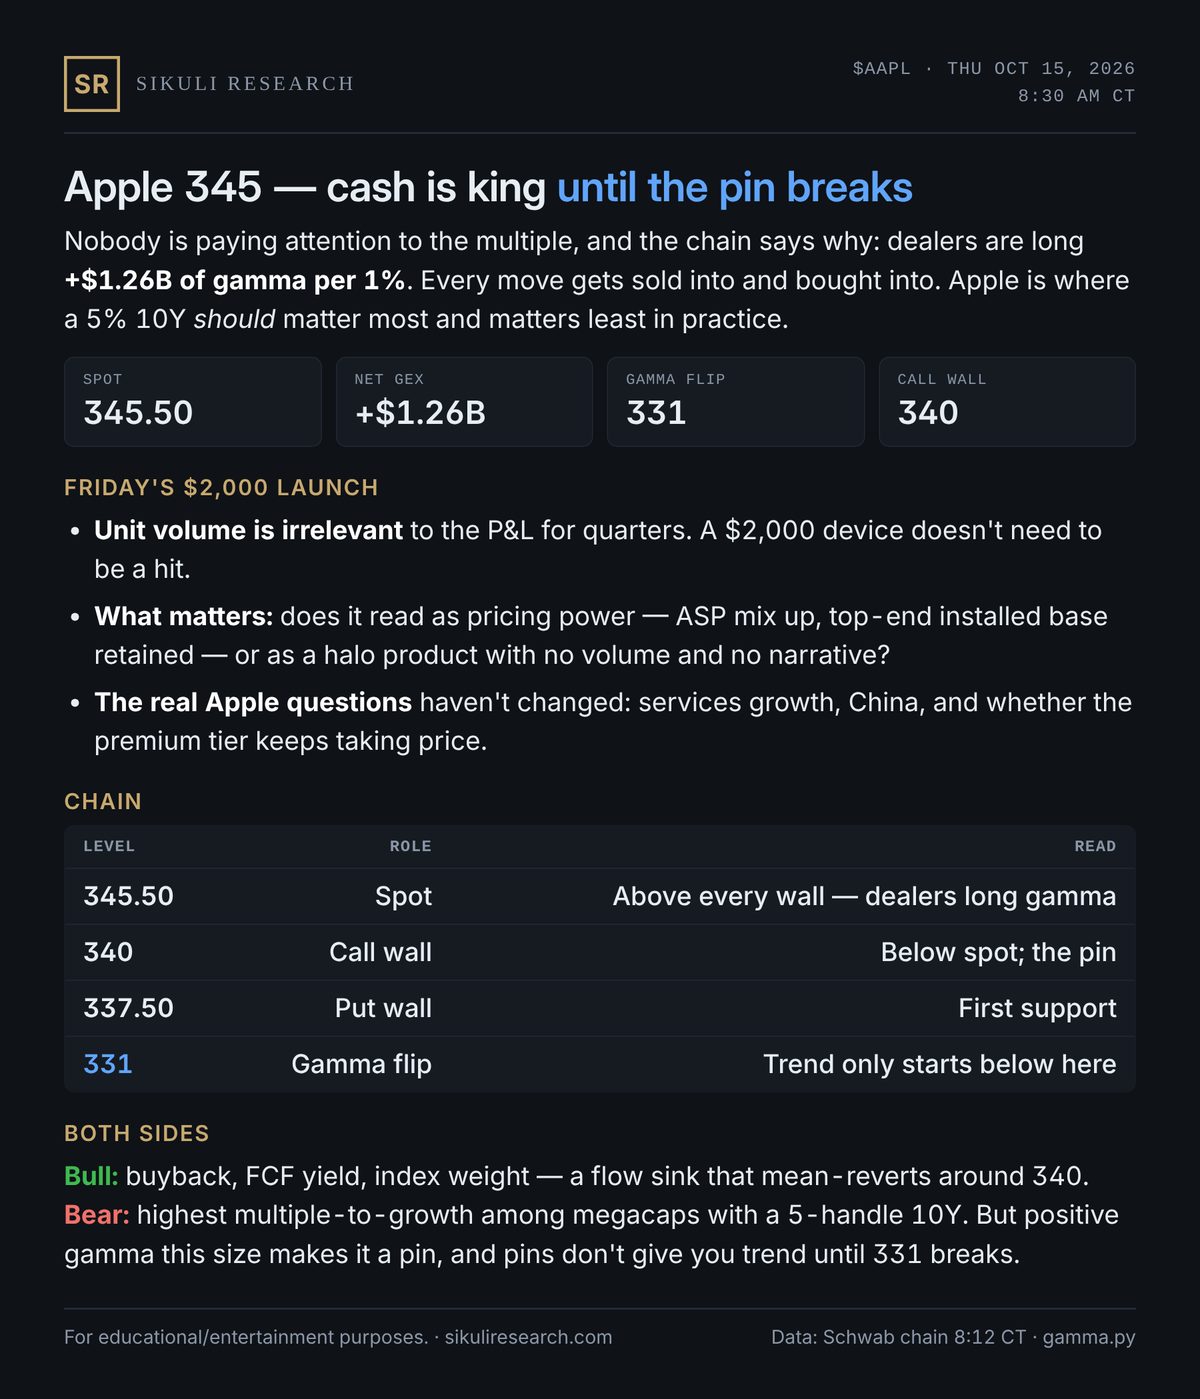
Nobody looks at the multiple; the chain says why: dealers long +$1.26B gamma, every move gets faded. Friday's $2,000 launch doesn't need volume — it needs to read as pricing power, not a halo. Flip 331, call wall 340. $AAPL
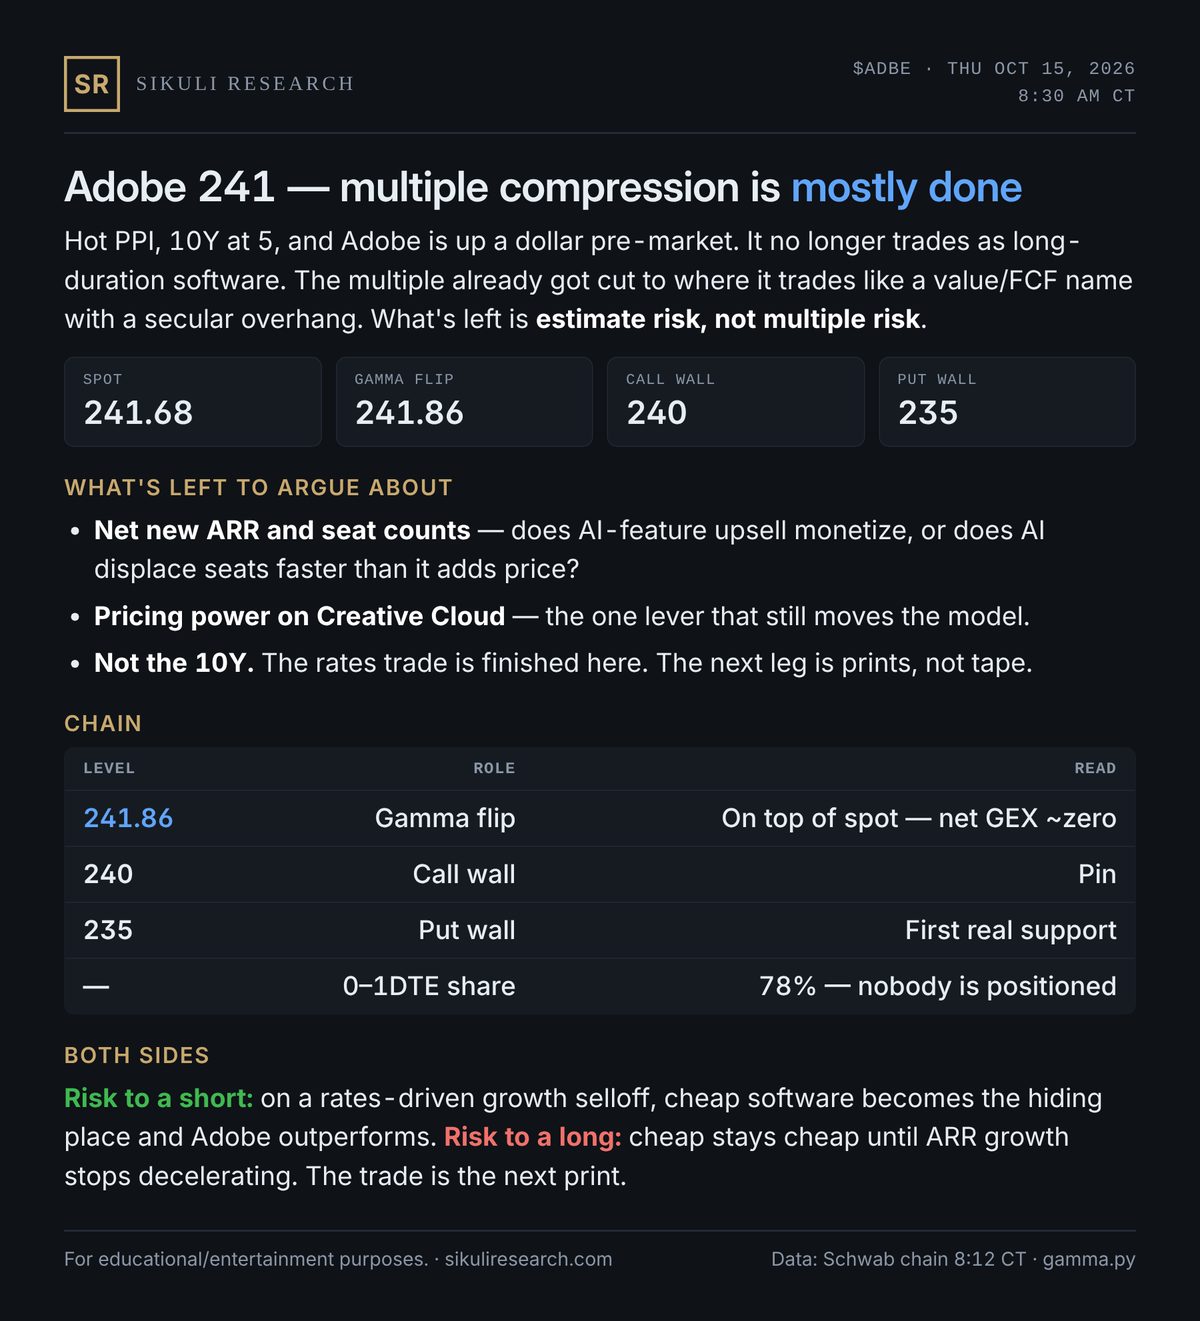
Hot PPI, 10Y at 5, and it's up a dollar pre-market. It no longer trades as long-duration software. What's left is estimate risk: net new ARR, seats, CC pricing. Next leg is prints, not tape. Flip 241.86 on spot, net GEX ~0. $ADBE
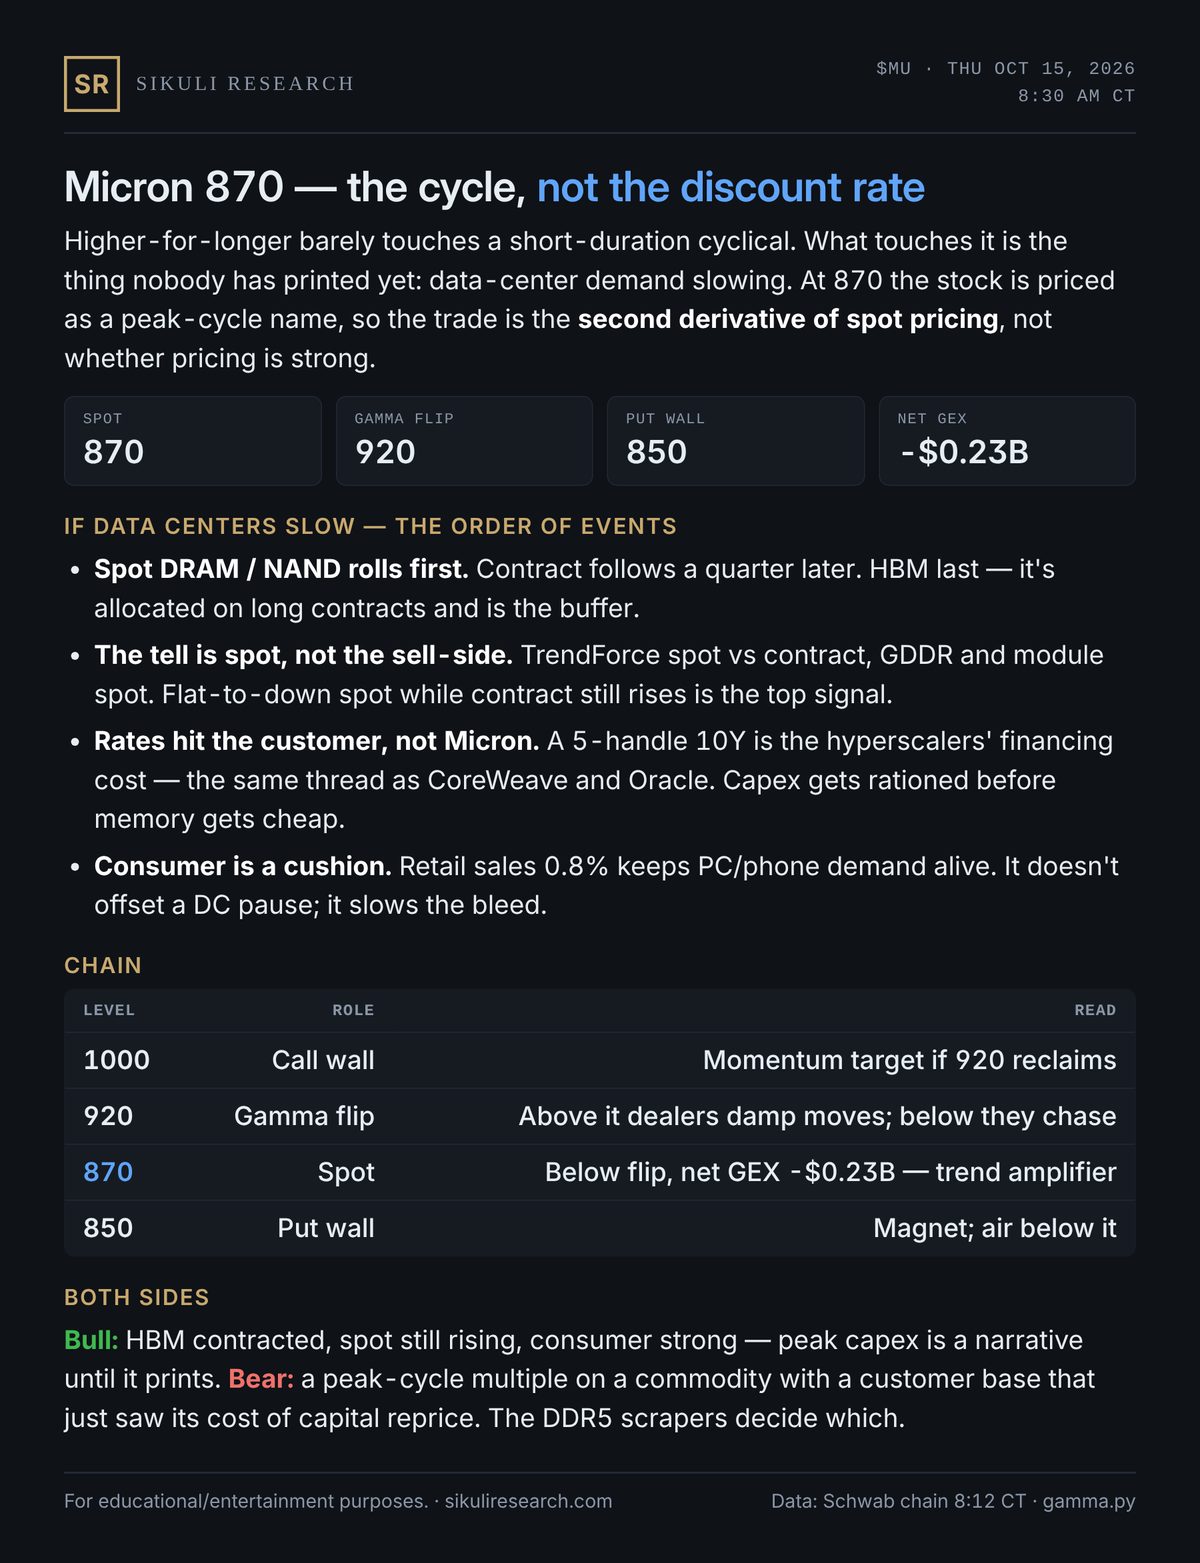
A 5-handle 10Y barely touches a short-duration cyclical. What touches it is DC demand slowing — visible in spot DRAM/NAND first, contract a quarter later, HBM last. Flip 920, put wall 850, net GEX -$0.23B. Spot is the tell. $MU
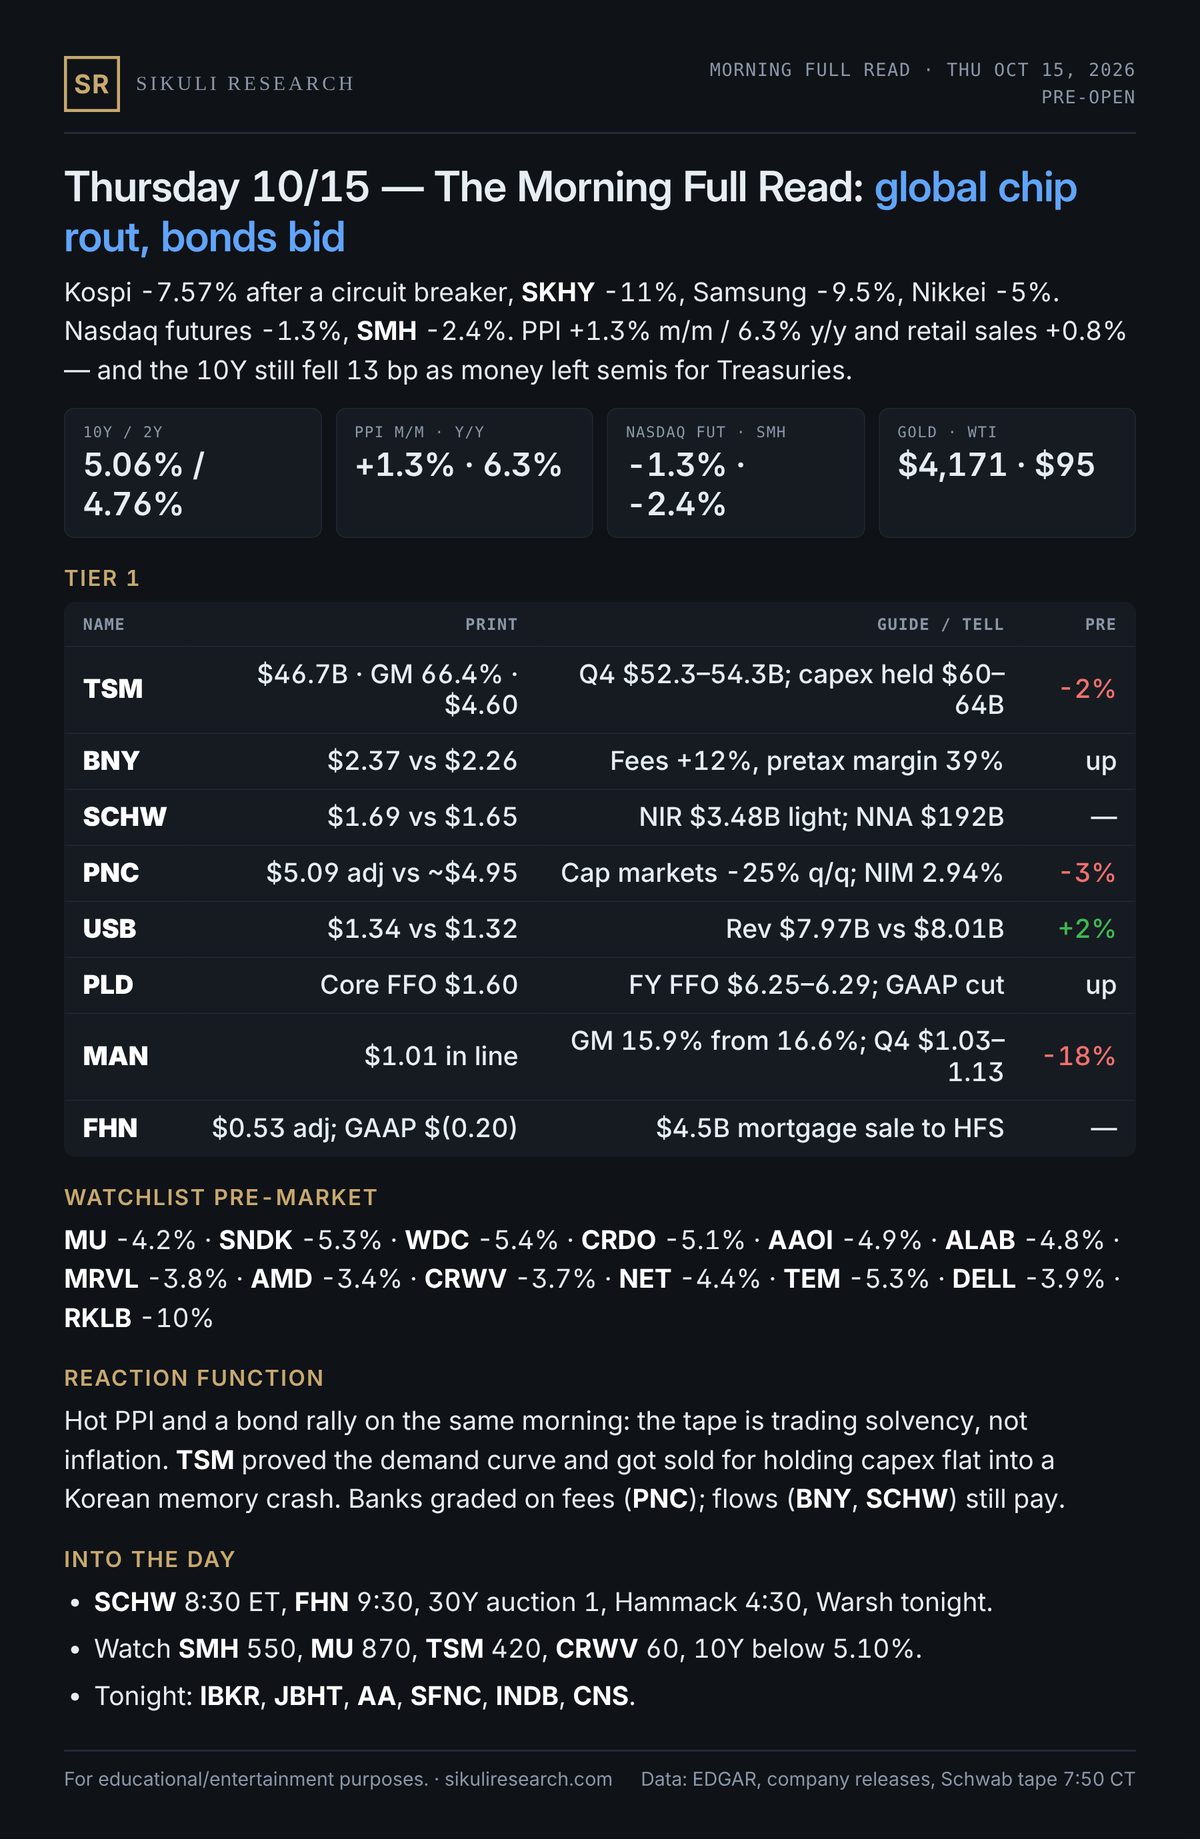
Global chip rout: Kospi -7.6% on a circuit breaker, SK Hynix -11%, Samsung -9.5%. PPI +1.3% m/m, yet the 10Y fell 13 bp as money left semis for Treasuries. $TSM record quarter, capex held, ADR -2%. Full read at Sikuli Research (link in bio)
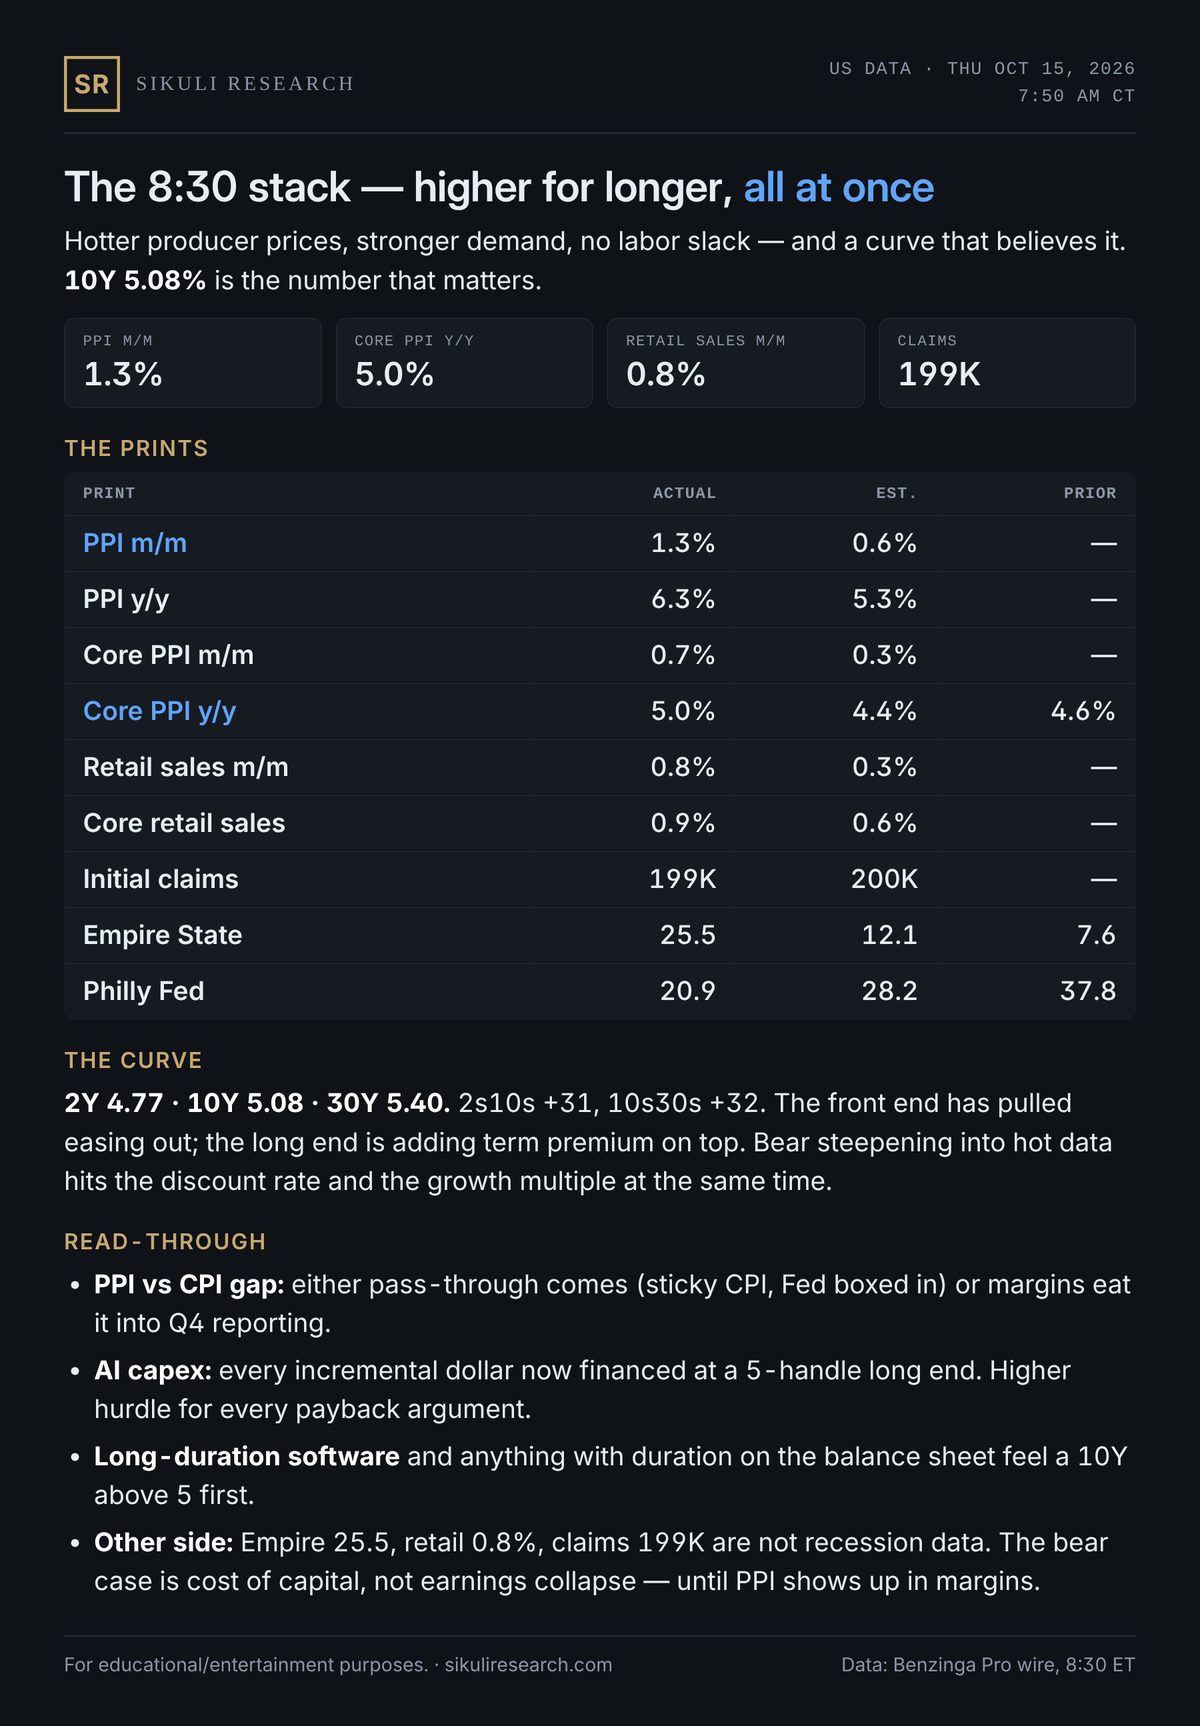
PPI 1.3% m/m vs 0.6% est, core 5.0% y/y. Retail sales 0.8% vs 0.3%. Claims 199K. Empire 25.5, Philly 20.9. 2Y 4.77 / 10Y 5.08 / 30Y 5.40. Hot prices + strong demand + no labor slack = higher for longer, and the long end is charging for it. $SPY
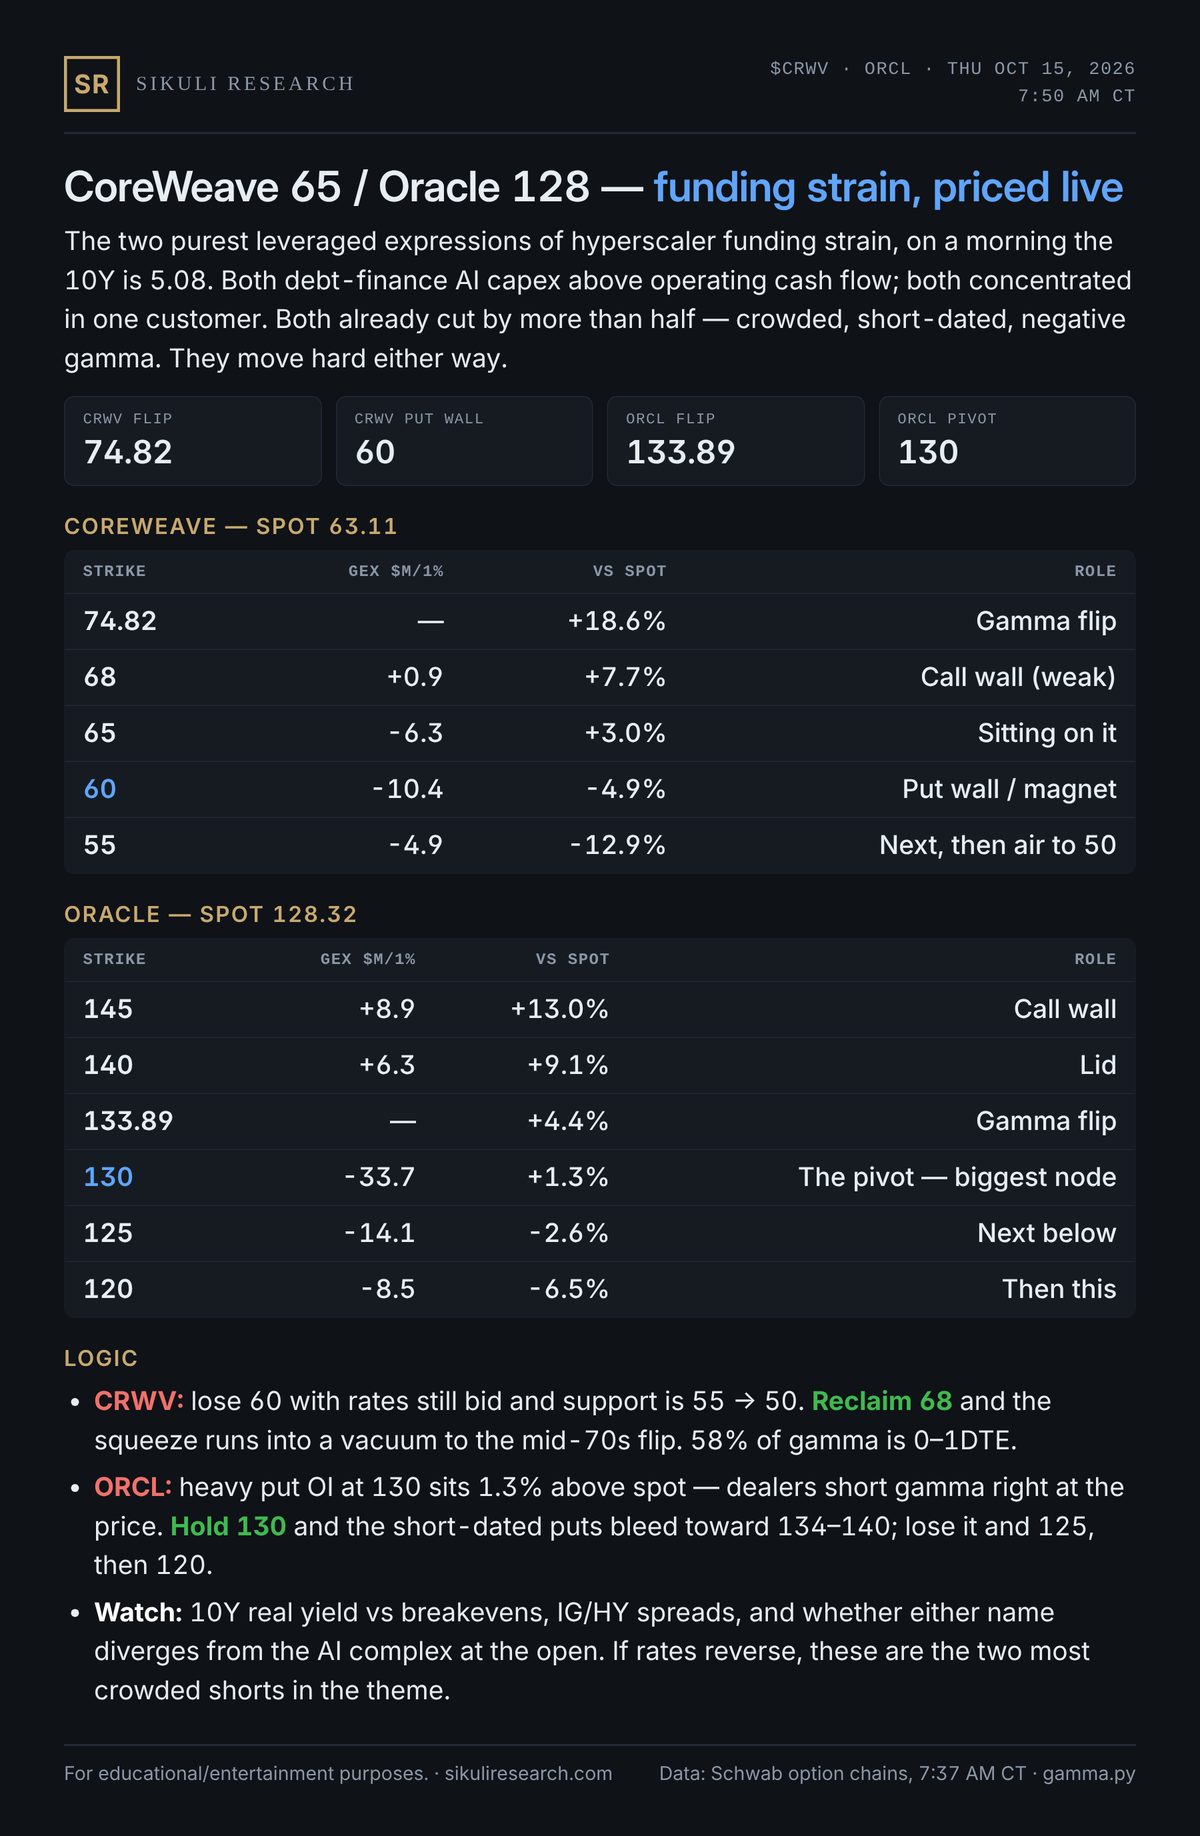
$CRWV: flip 74.8, put wall 60, call wall 68. Short gamma all the way. Oracle: 130 is the pivot (-$33.7M, biggest node). 125/120 below, 140/145 above. Levels, not advice.
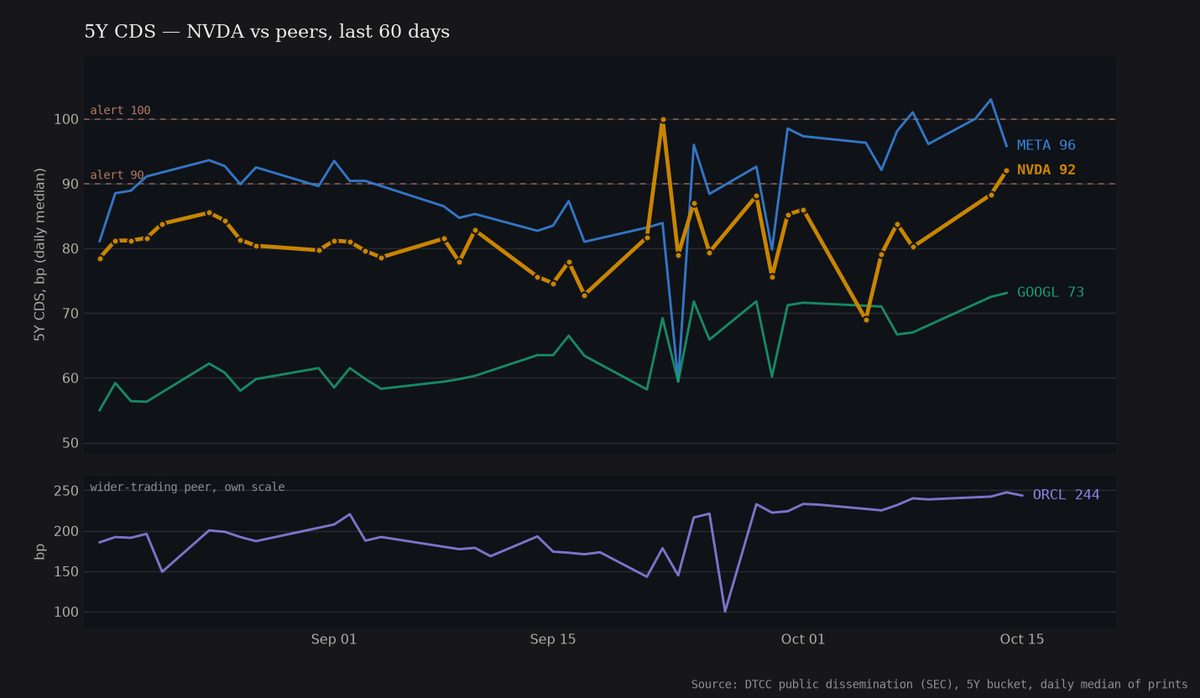
8 prints, Oct 14. Peers: META 96, GOOGL 73, ORCL 244. Alert: crossed 90 bp Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
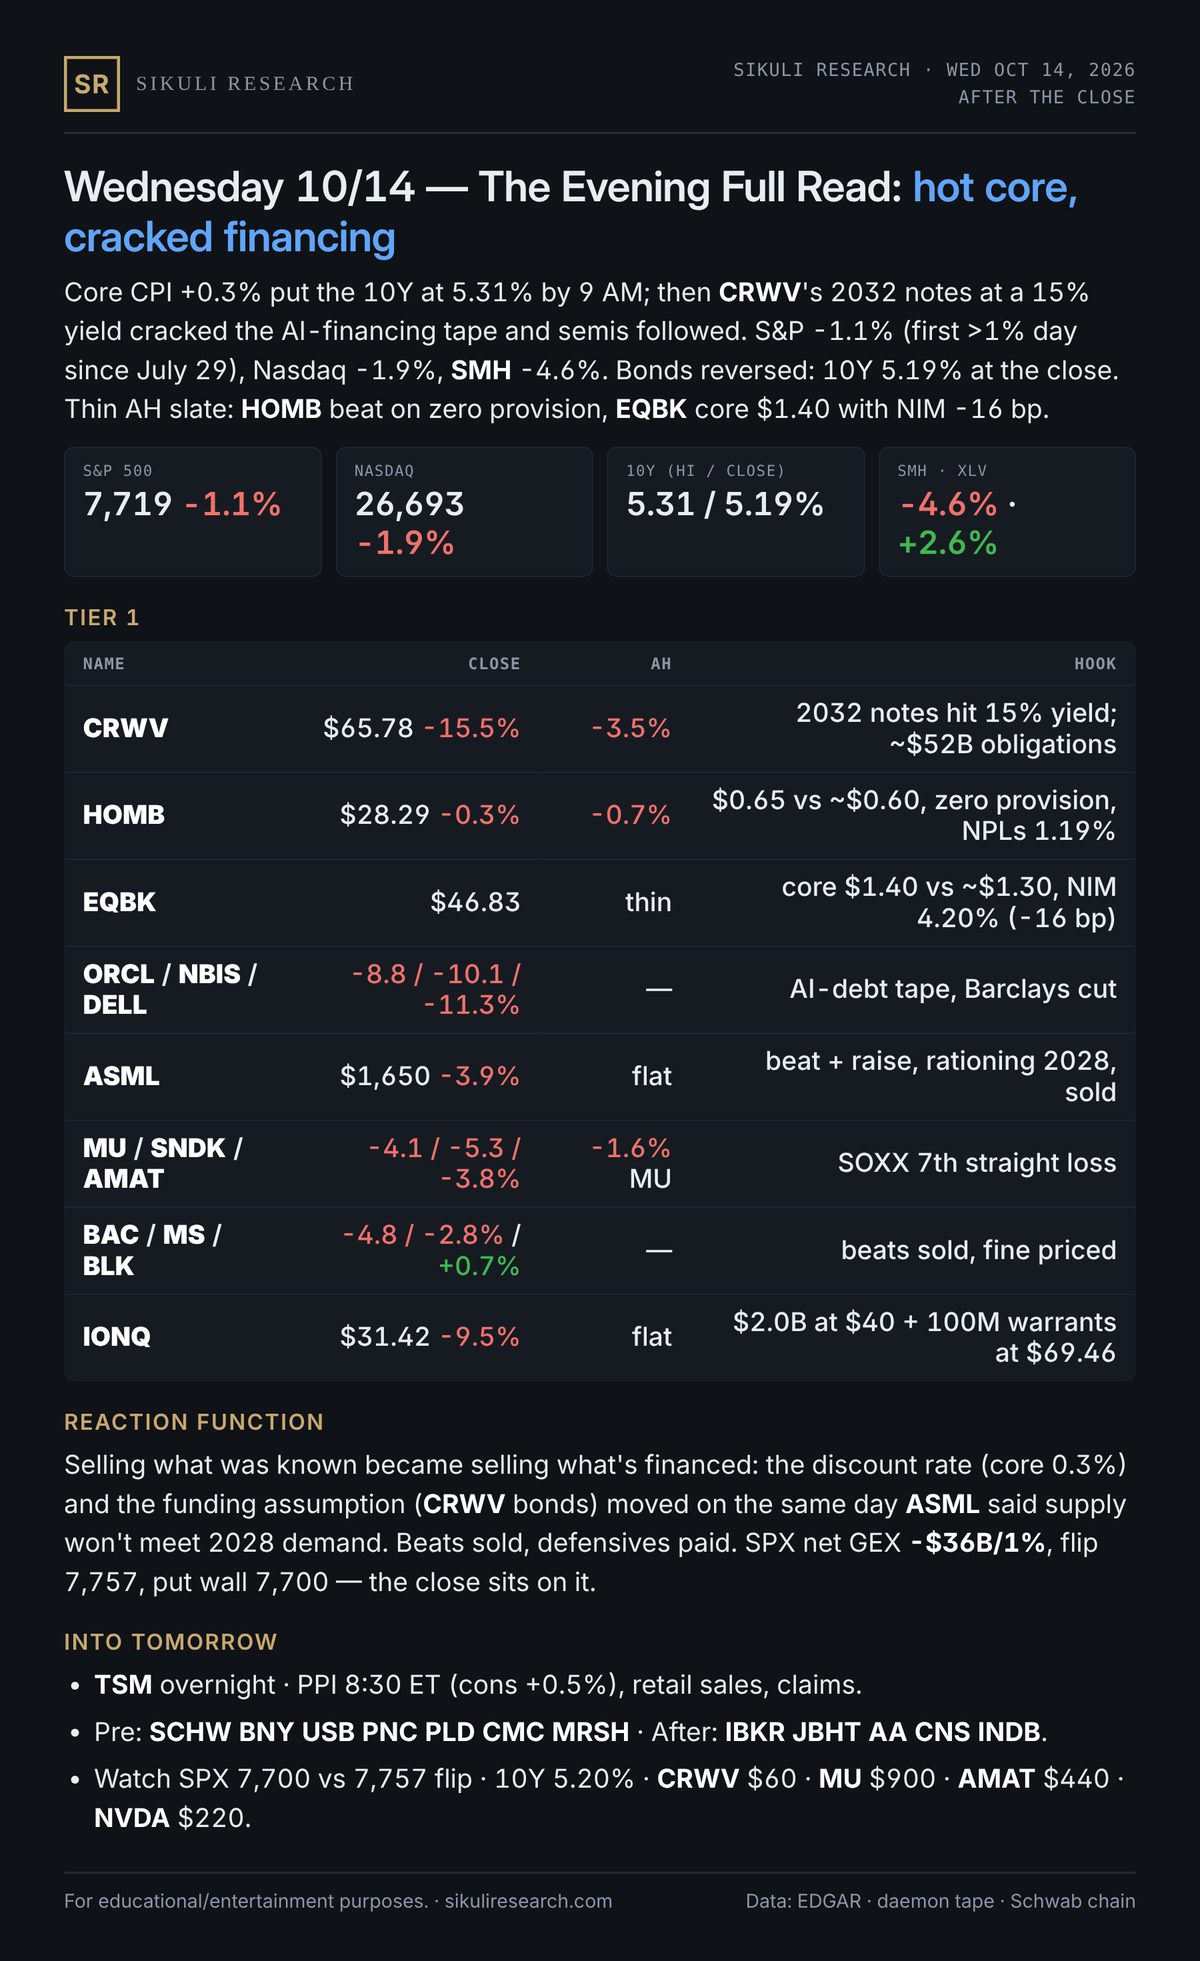
Hot core CPI sent the 10Y to 5.31%, then the AI-financing tape cracked: $CRWV -15.5% as its 2032 notes hit a 15% yield, DELL -11.3%, SMH -4.6%. S&P -1.1%, Nasdaq -1.9%. HOMB beat on zero provision. Full read at Sikuli Research (link in bio)
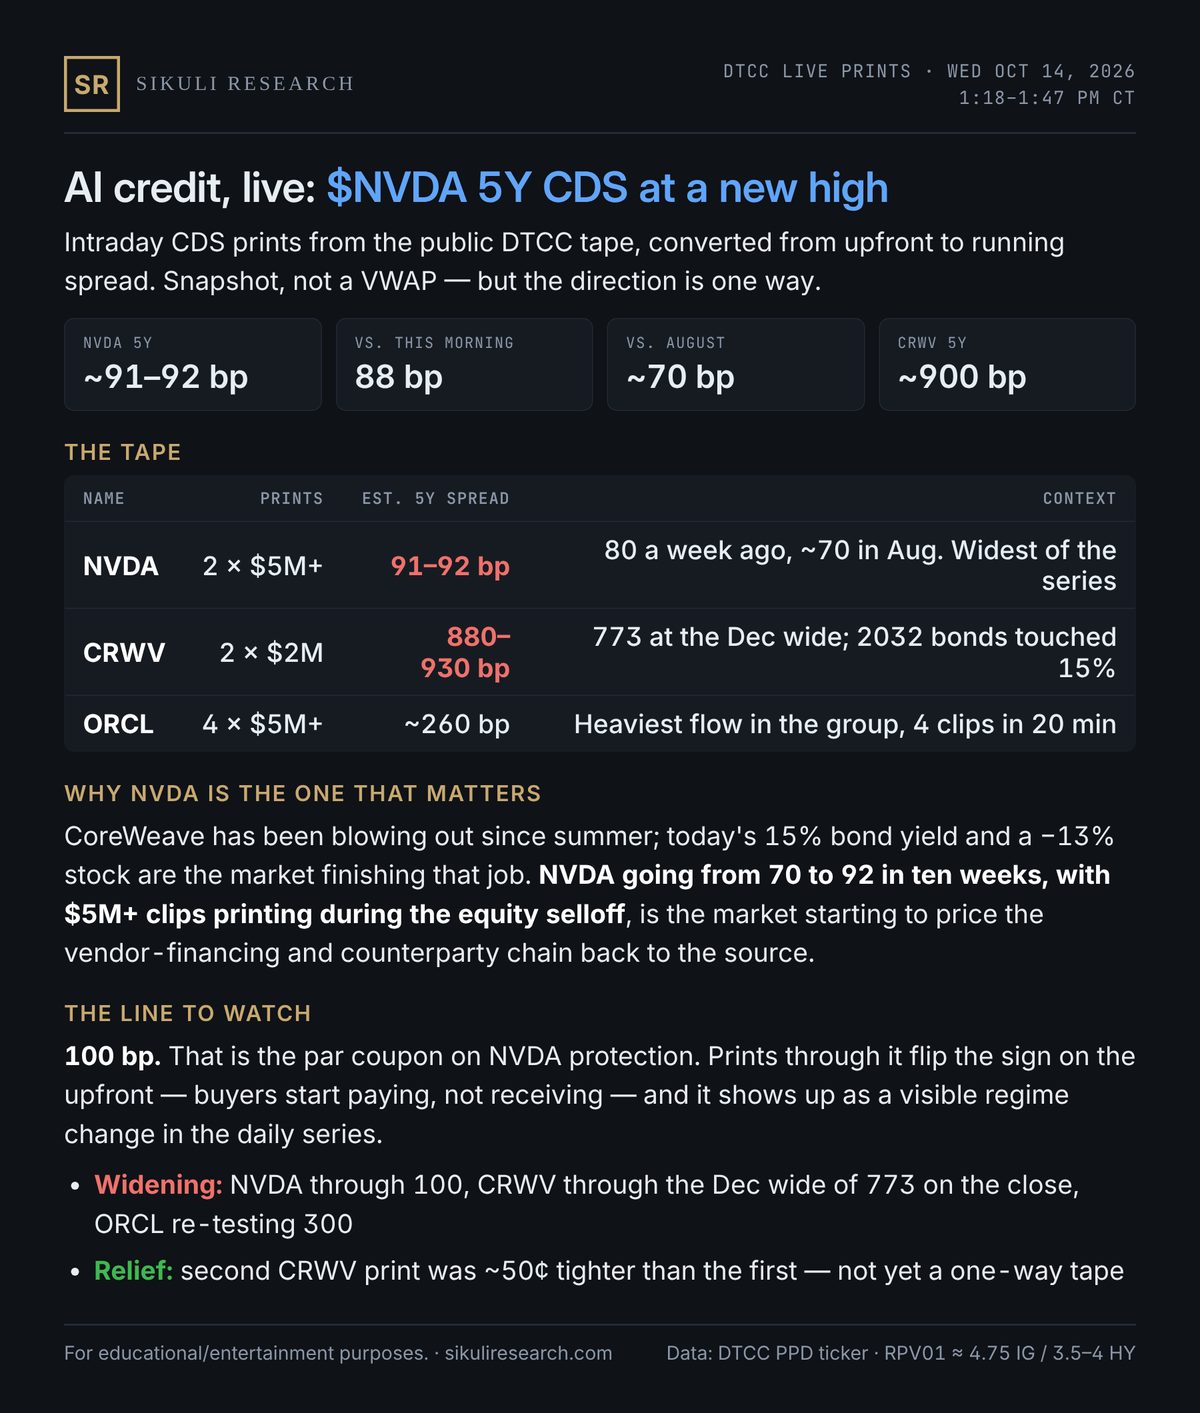
$NVDA 5Y CDS ~91–92 bp, a new high. 88 this morning, 80 a week ago, ~70 in August. $5M+ clips printing into the equity selloff. CRWV ~900 bp. ORCL ~260 bp, heaviest flow in the group. The line: 100 bp, par coupon on NVDA protection.
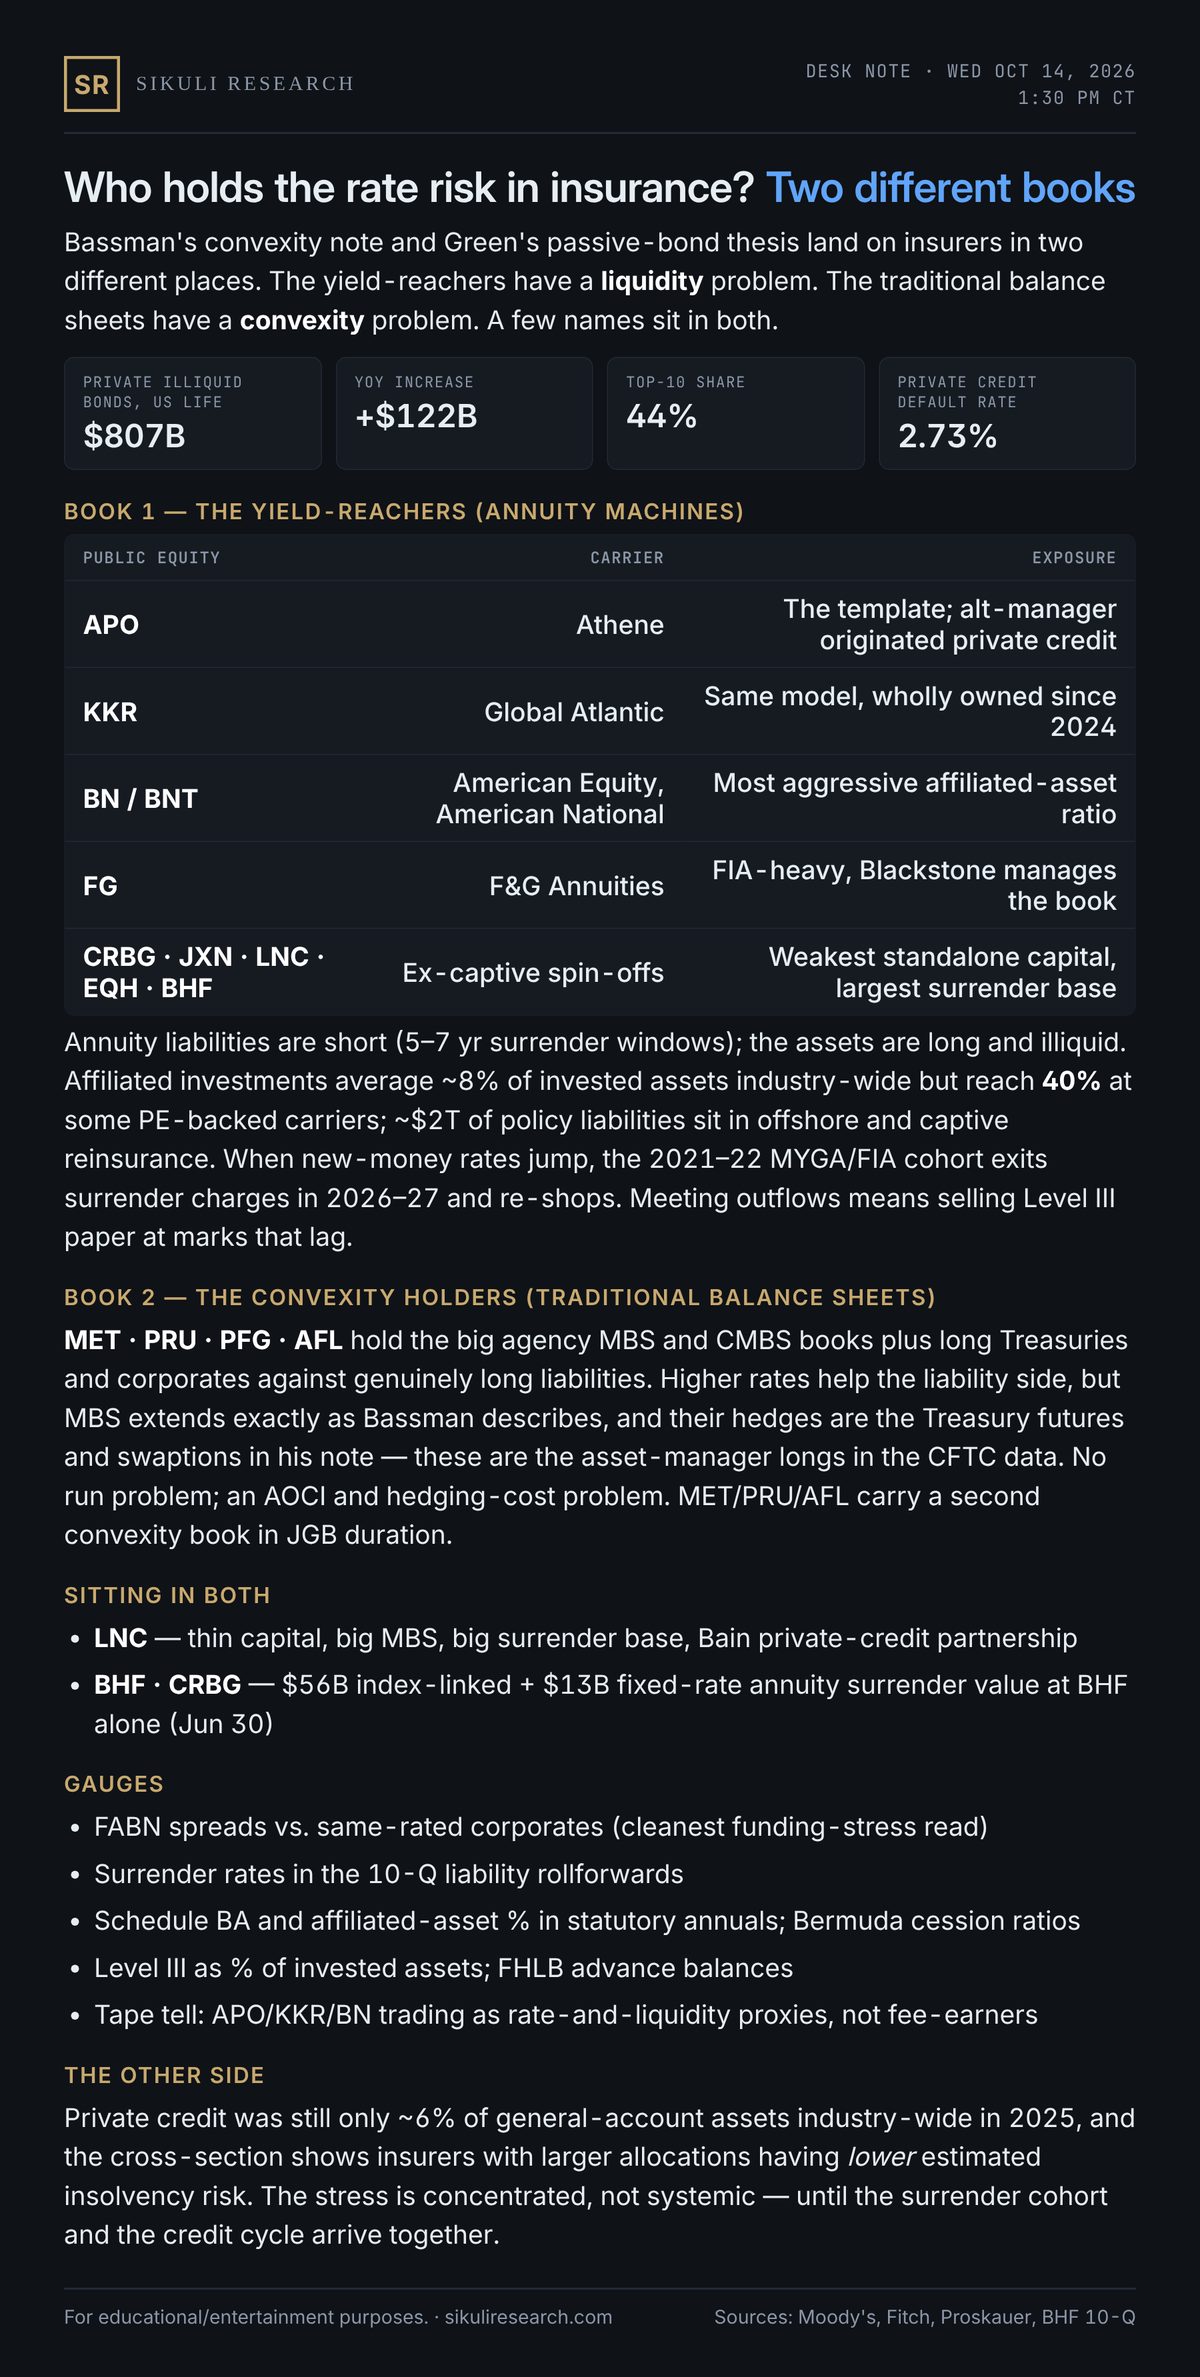
Yield-reachers ($APO, KKR, BN, FG, ex-captive spin-offs): a liquidity problem. Short surrender windows, long illiquid assets. Traditional balance sheets (MET, PRU, PFG, AFL): a convexity problem. LNC, BHF, CRBG: both.
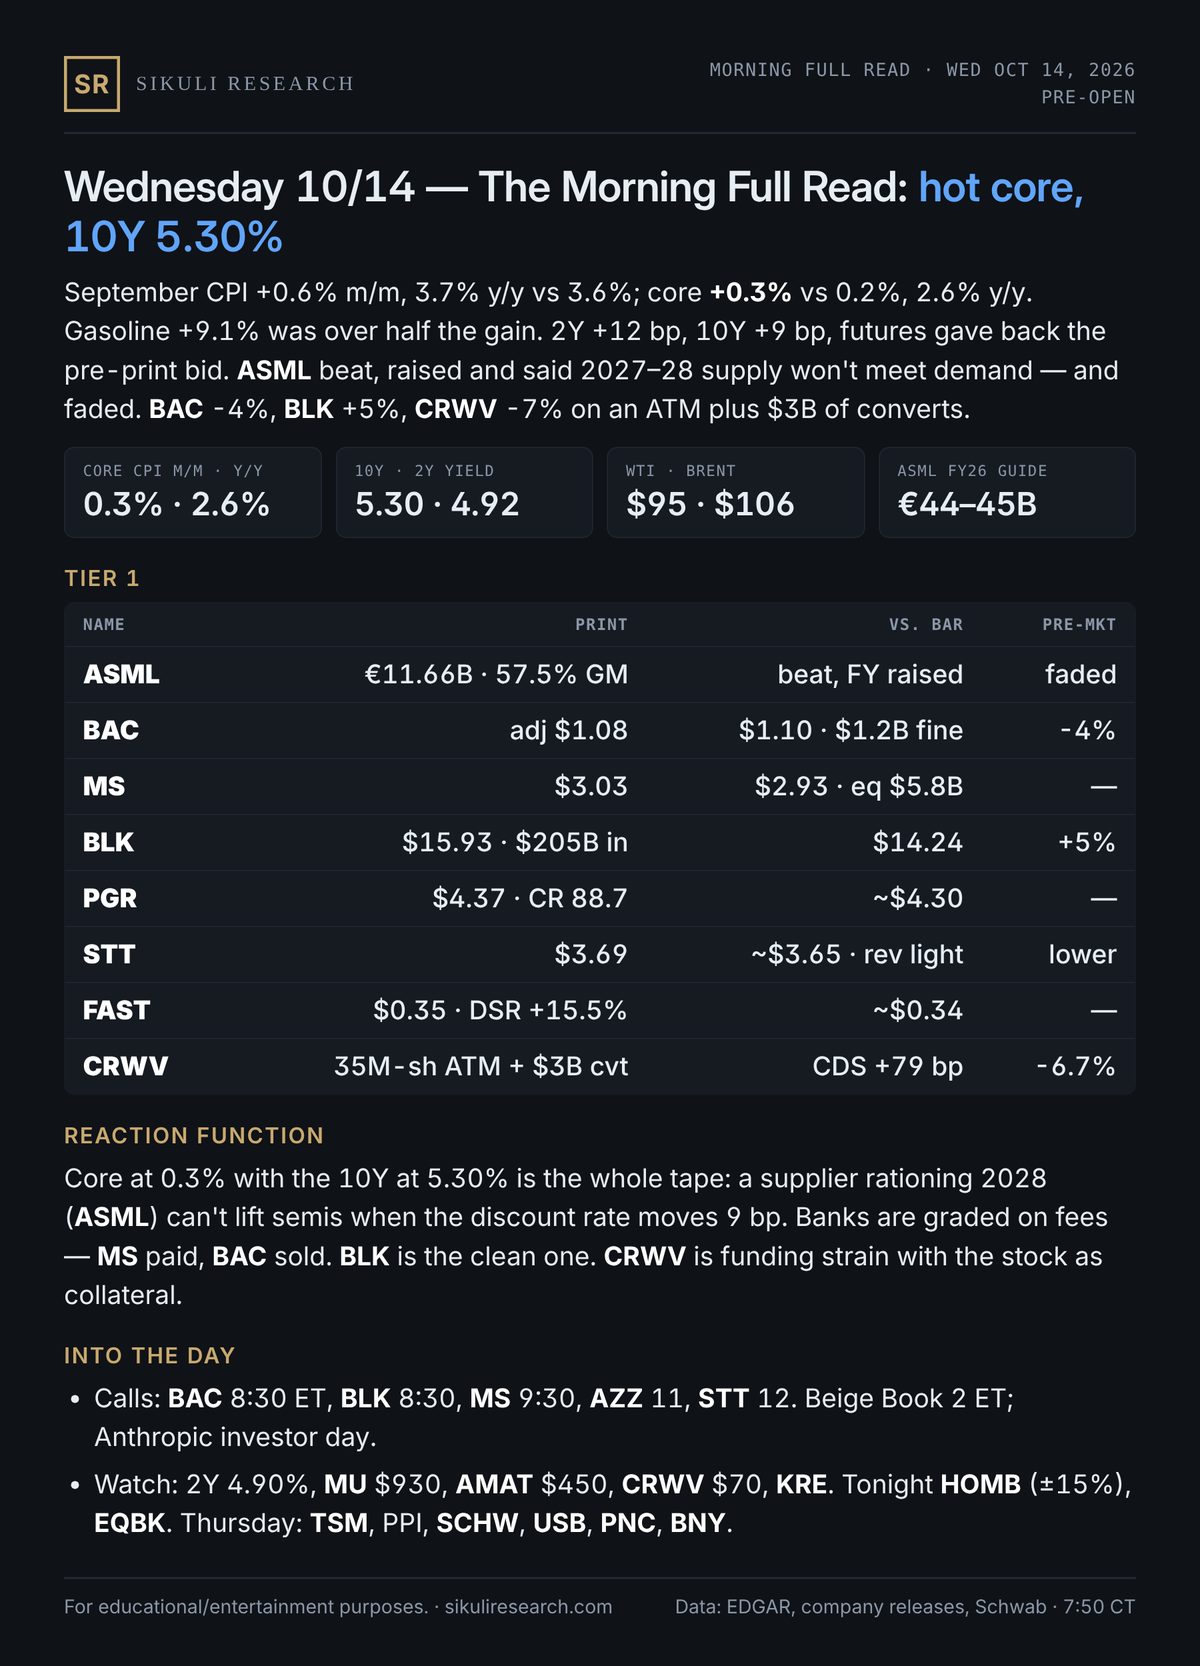
Hot core: CPI 0.3% m/m, 10Y 5.30%. ASML beat, raised, said 2027–28 supply won't meet demand — and faded. BAC -4% on a fine and a trading miss; BLK +5% on $205B of inflows; CoreWeave -7% on new equity. Full read at Sikuli Research (link in bio)
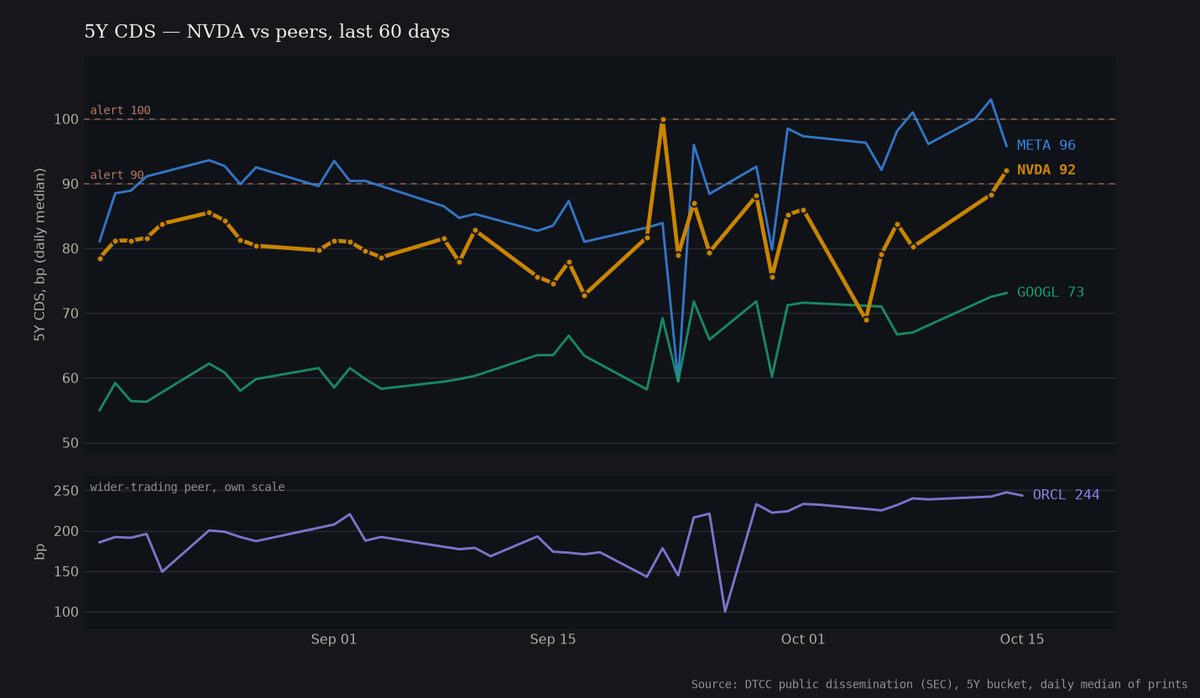
7 prints, Oct 13. Peers: META 103, GOOGL 72, ORCL 242. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
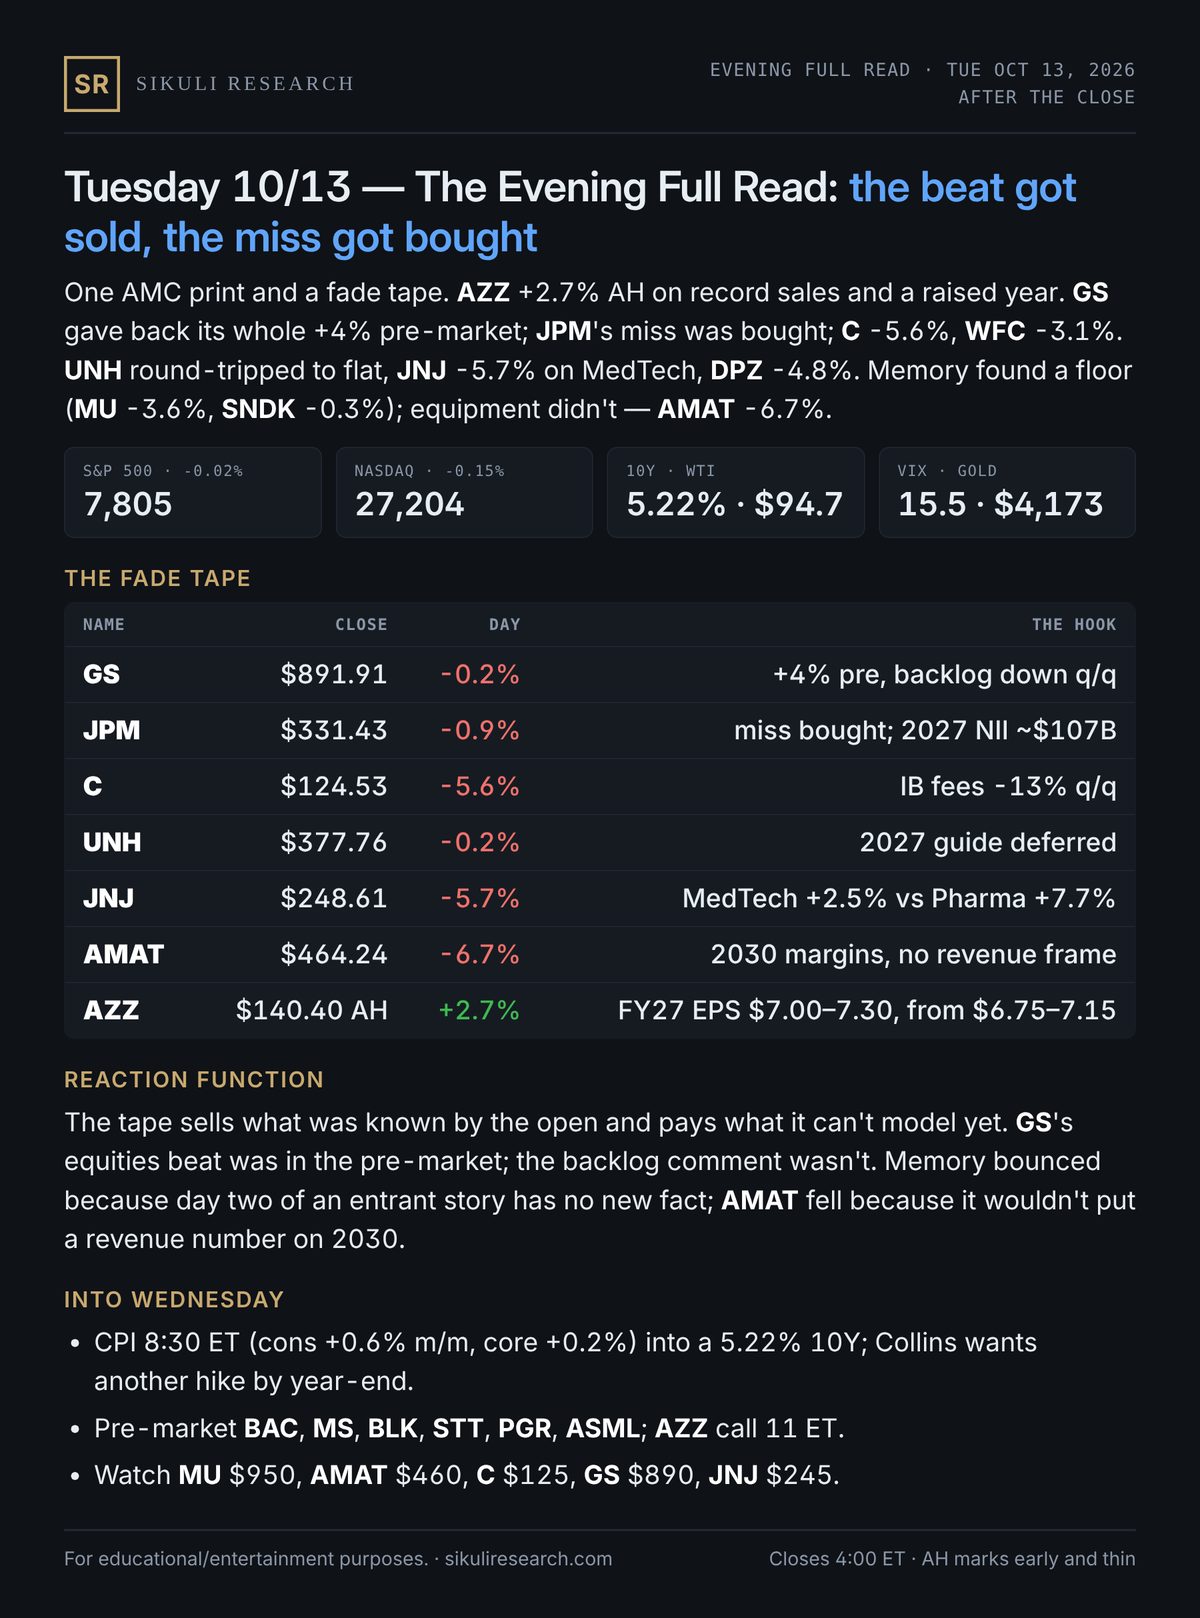
The beat got sold, the miss got bought: GS gave back its whole pre-market pop, C -5.6%, JNJ -5.7% on MedTech. Memory found a floor; AMAT -6.7% with no 2030 revenue number. $AZZ +2.7% AH on a raised year. Full read at Sikuli Research (link in bio)
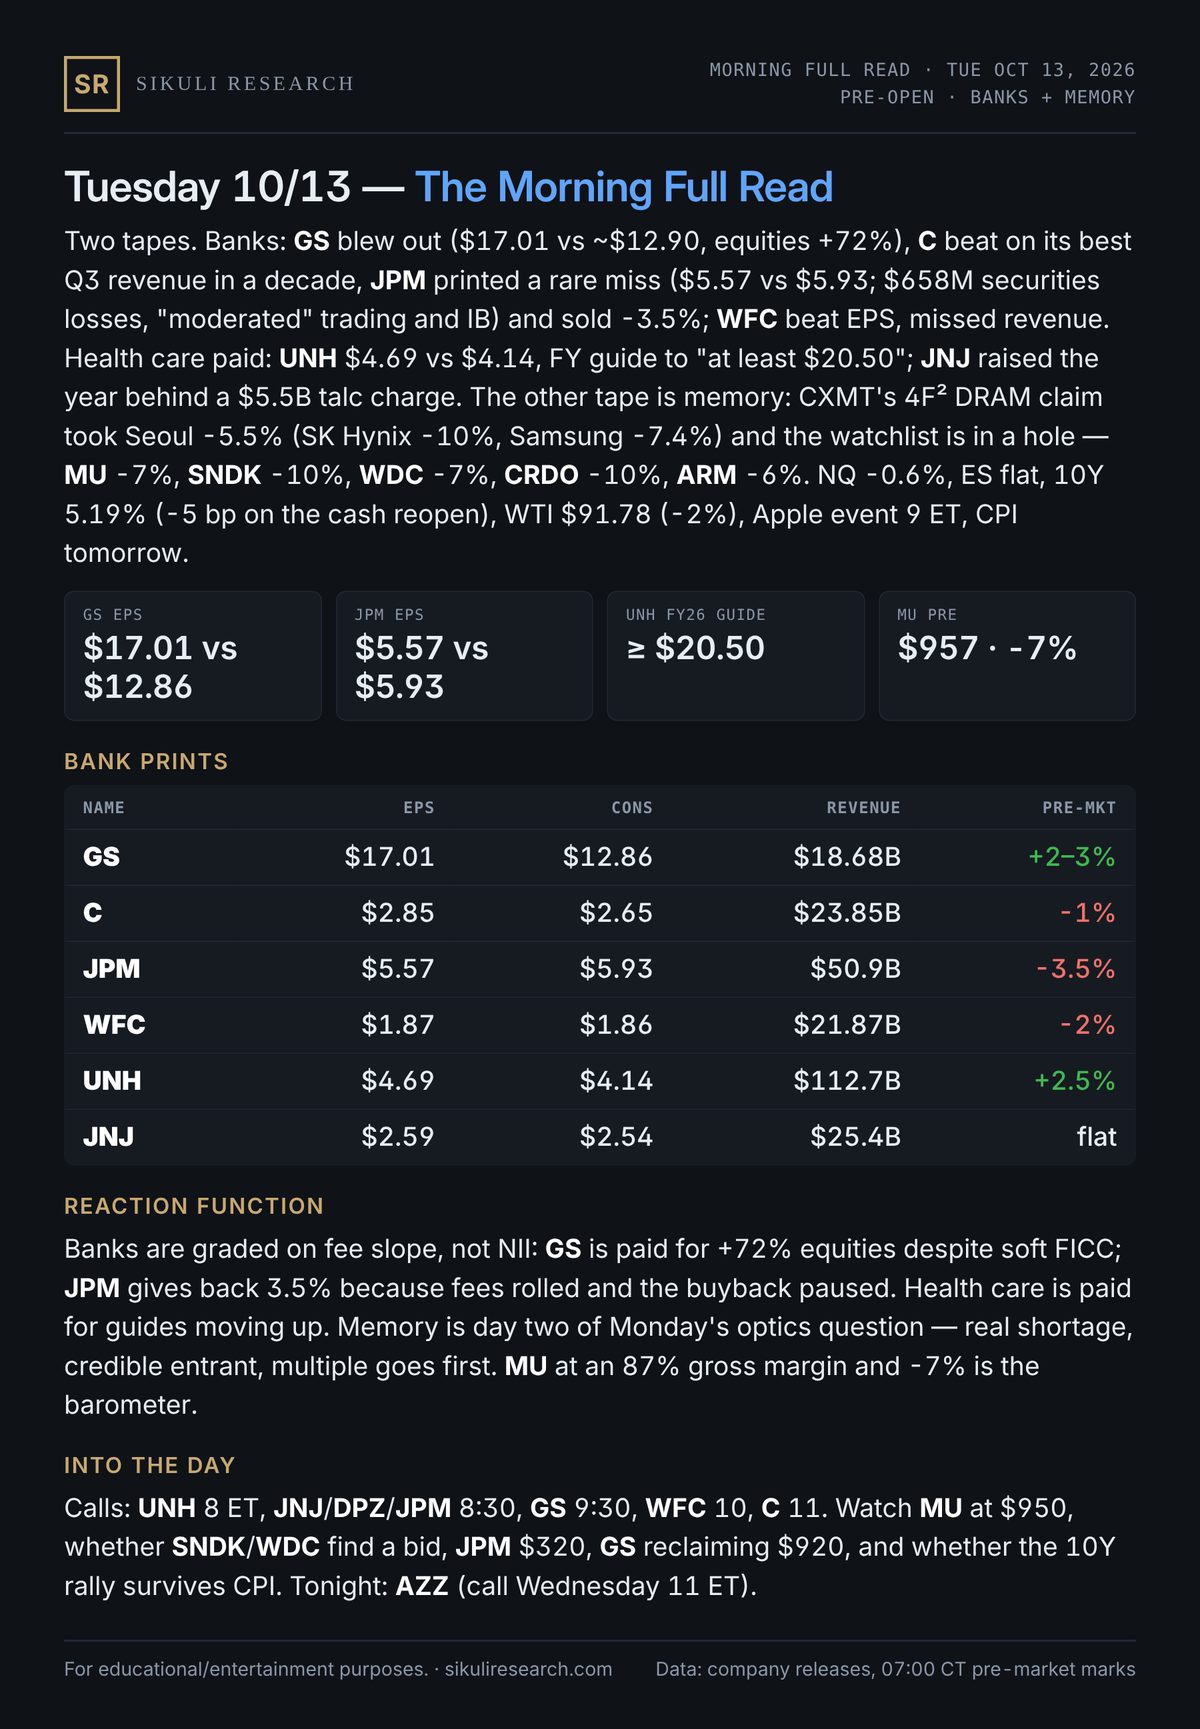
Goldman blew out on +72% equities; JPM printed a rare miss and sold 3.5% — banks graded on fee slope, not NII. UNH guides to $20.50+. Memory in a hole on CXMT's DRAM claim: $MU -7%, SanDisk -10%. Full read at Sikuli Research (link in bio)
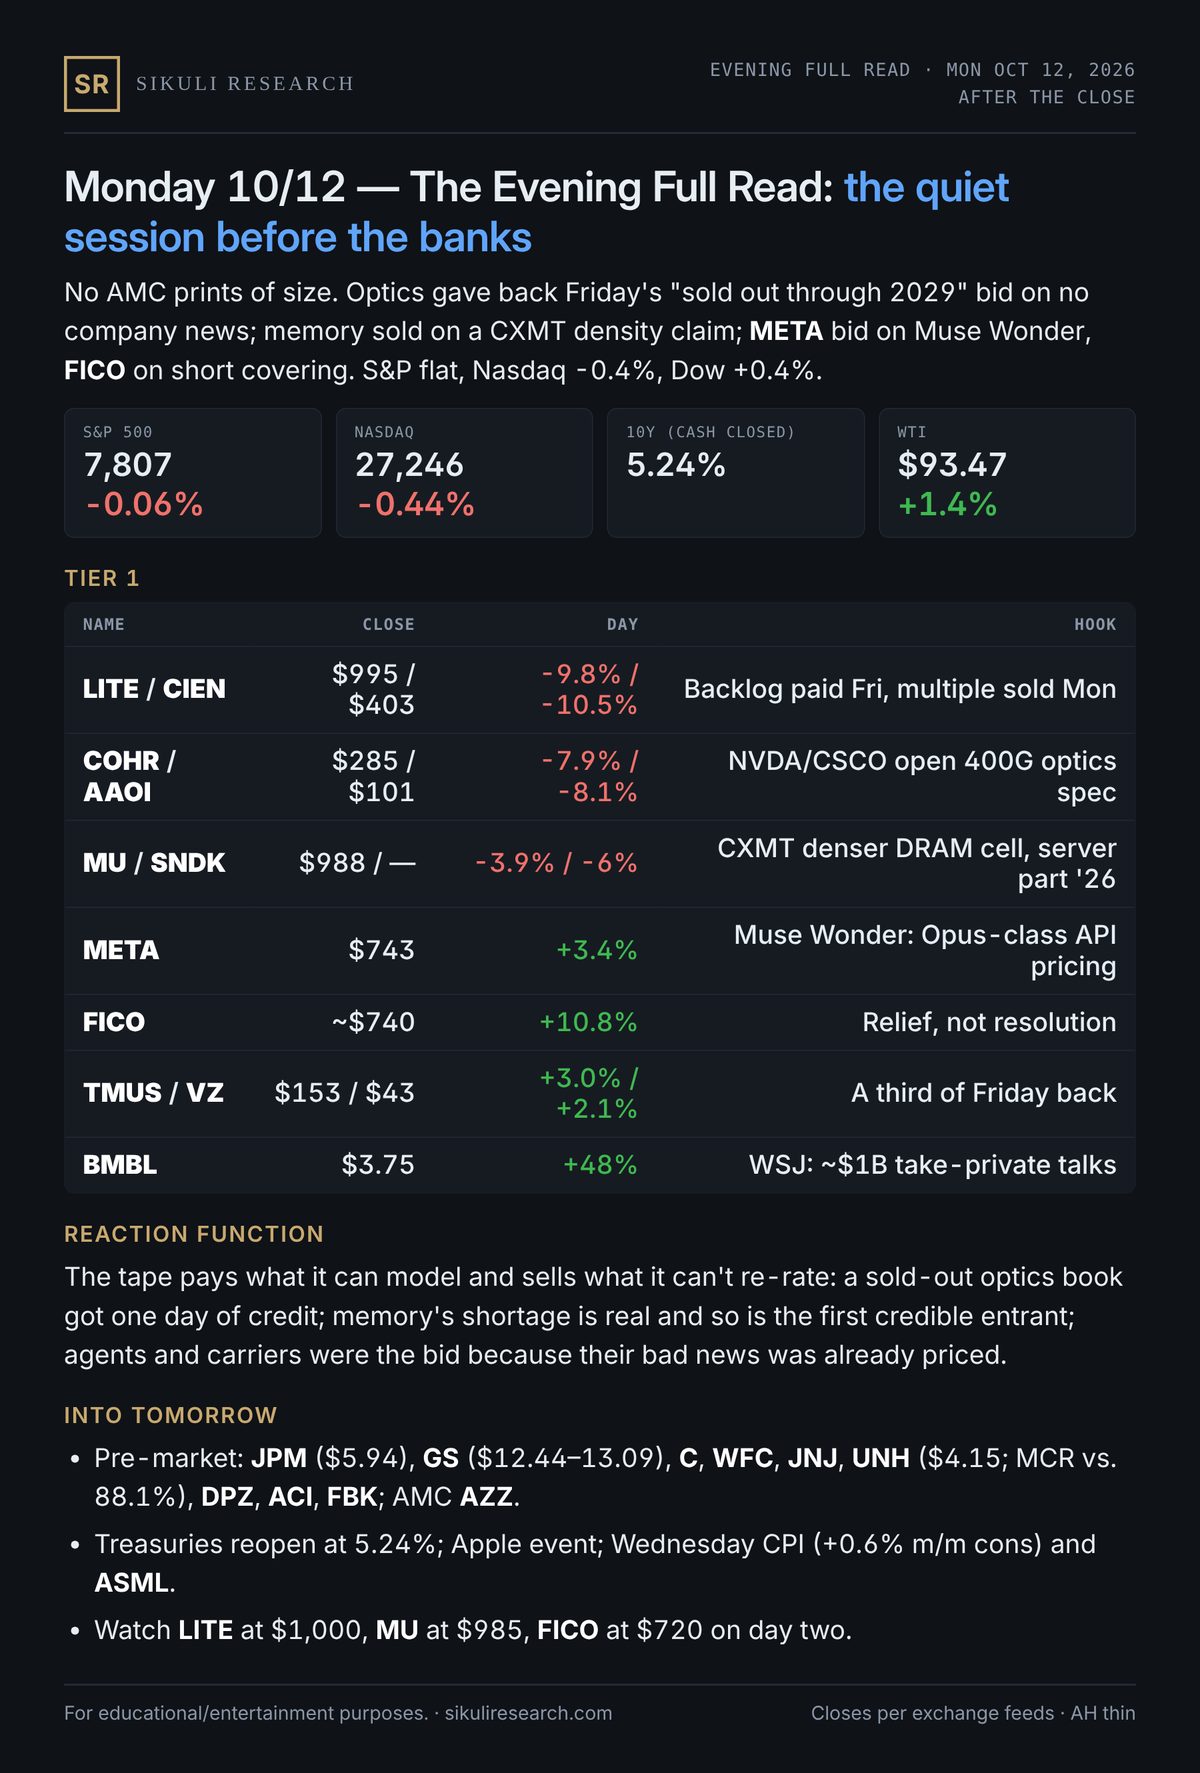
Optics gave back Friday's "sold out through 2029" bid on no news (LITE -9.8%, CIEN -10.5%); memory sold on a CXMT density claim ($MU -3.9%); META bid on Muse Wonder, FICO +10.8%. Banks open Q3 at the bell. Full read at Sikuli Research (link in bio)
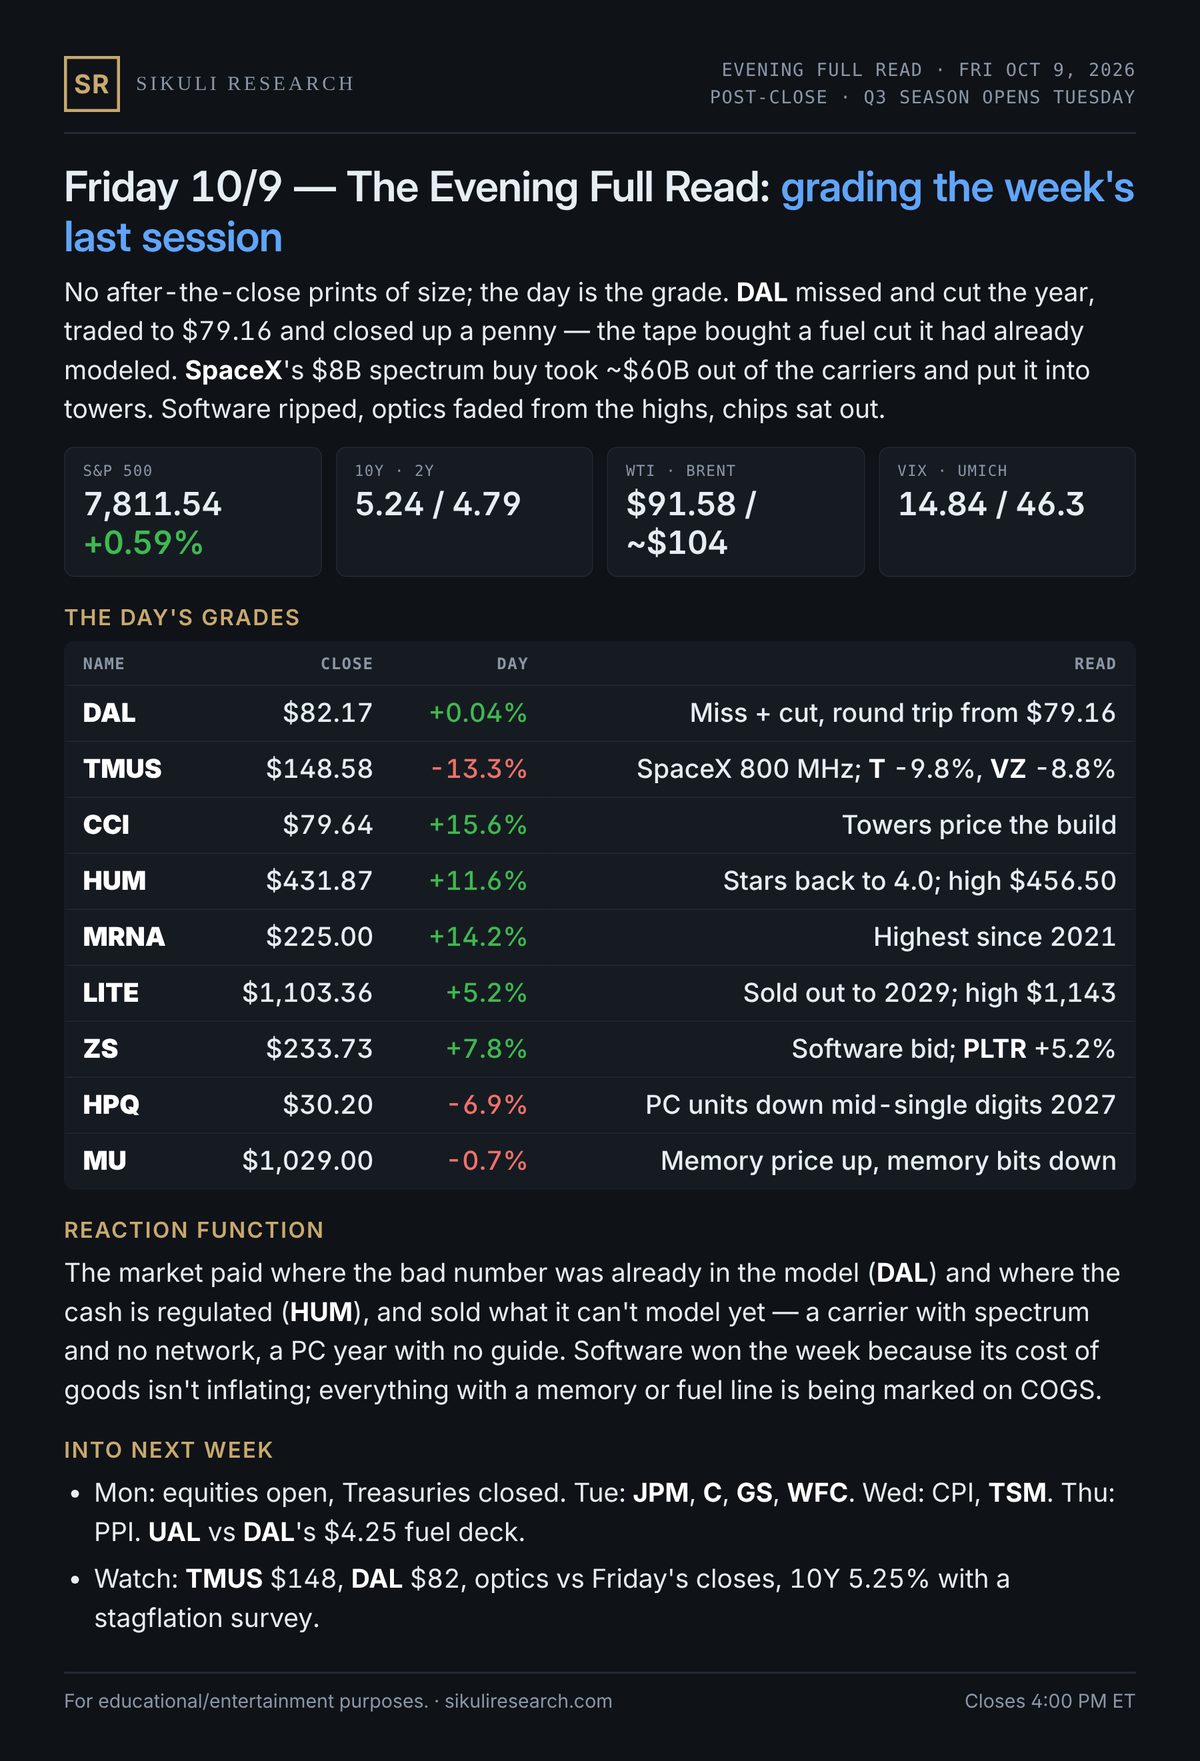
$DAL missed, cut the year, closed flat — the tape had already modeled the fuel. SpaceX's spectrum buy moved tens of billions out of the carriers into towers. Software ripped, optics faded, chips sat out. Full read at Sikuli Research (link in bio)
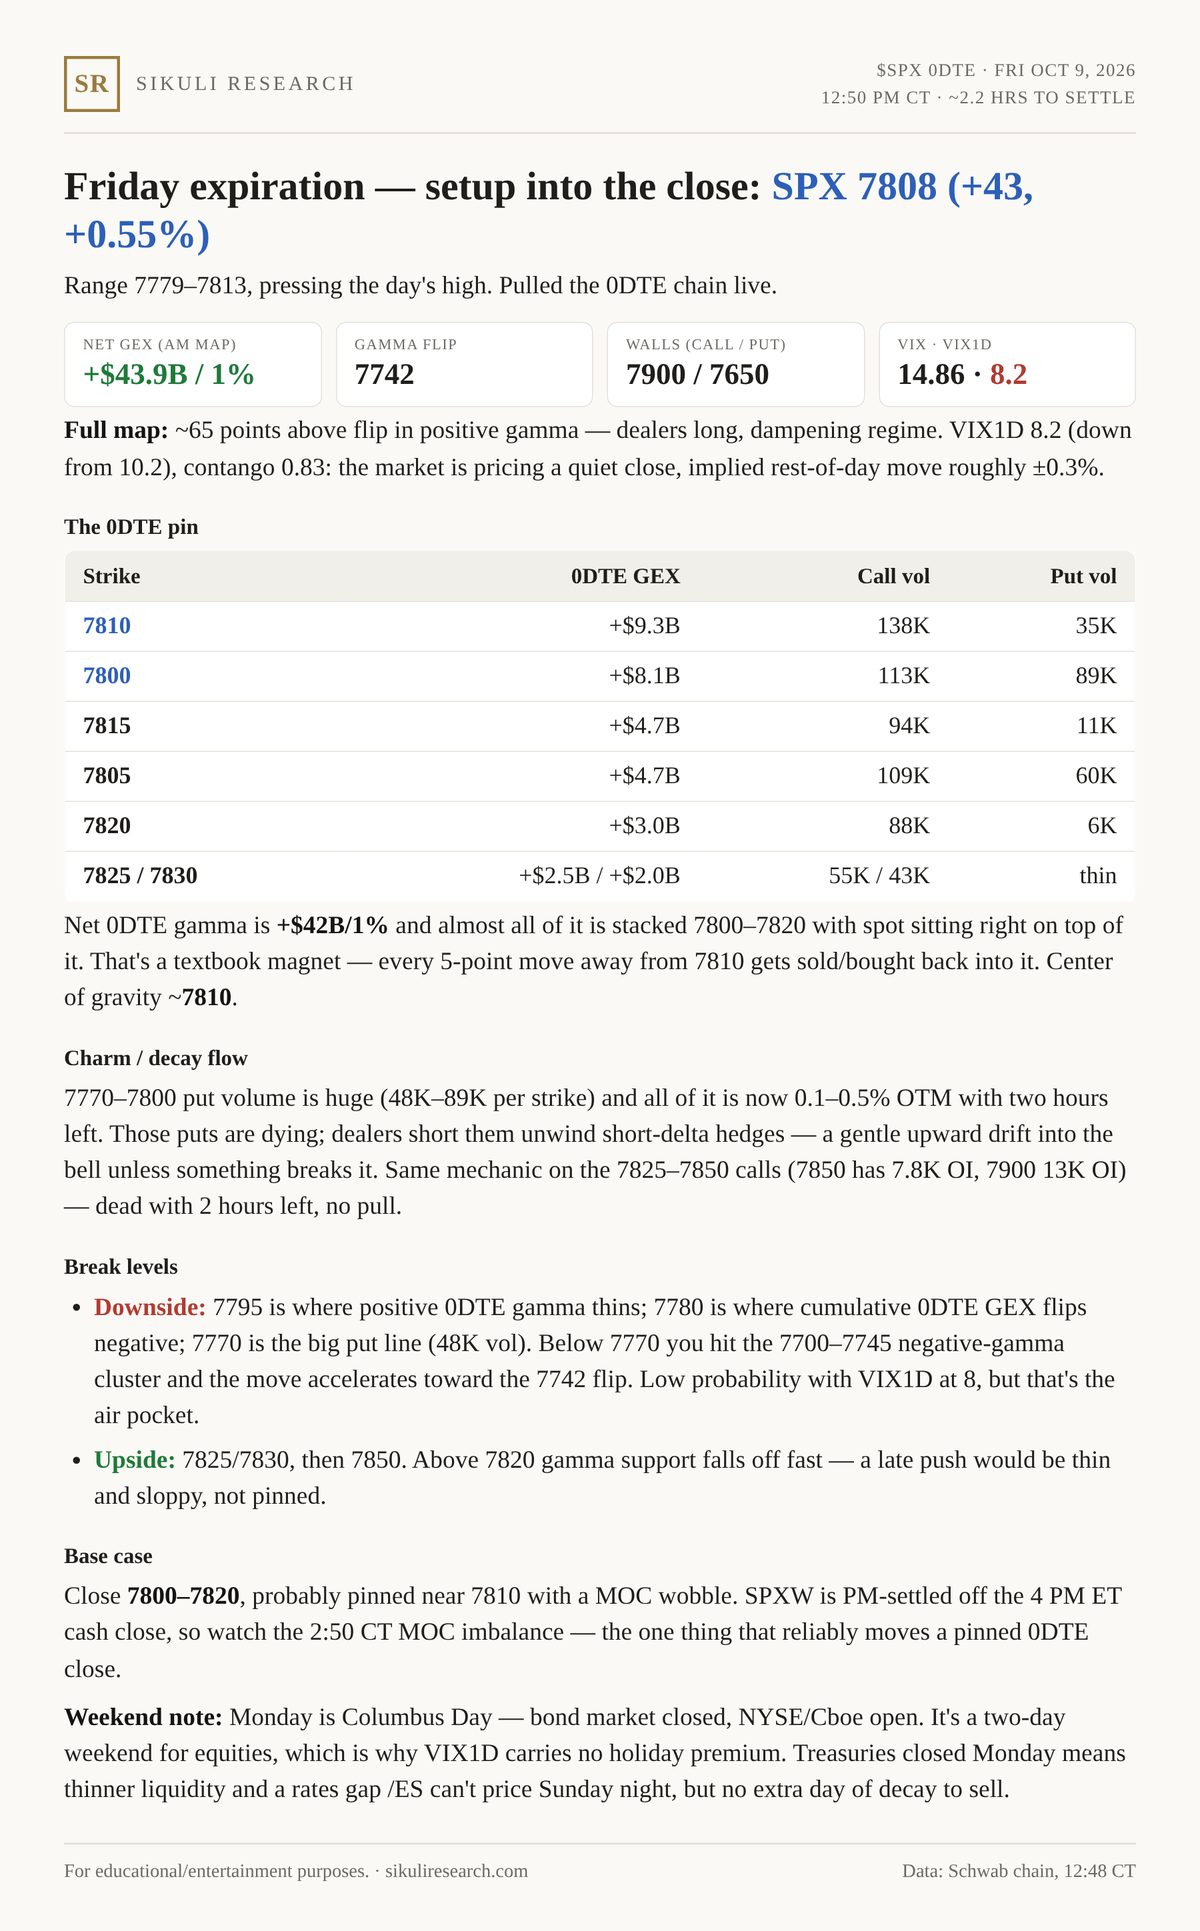
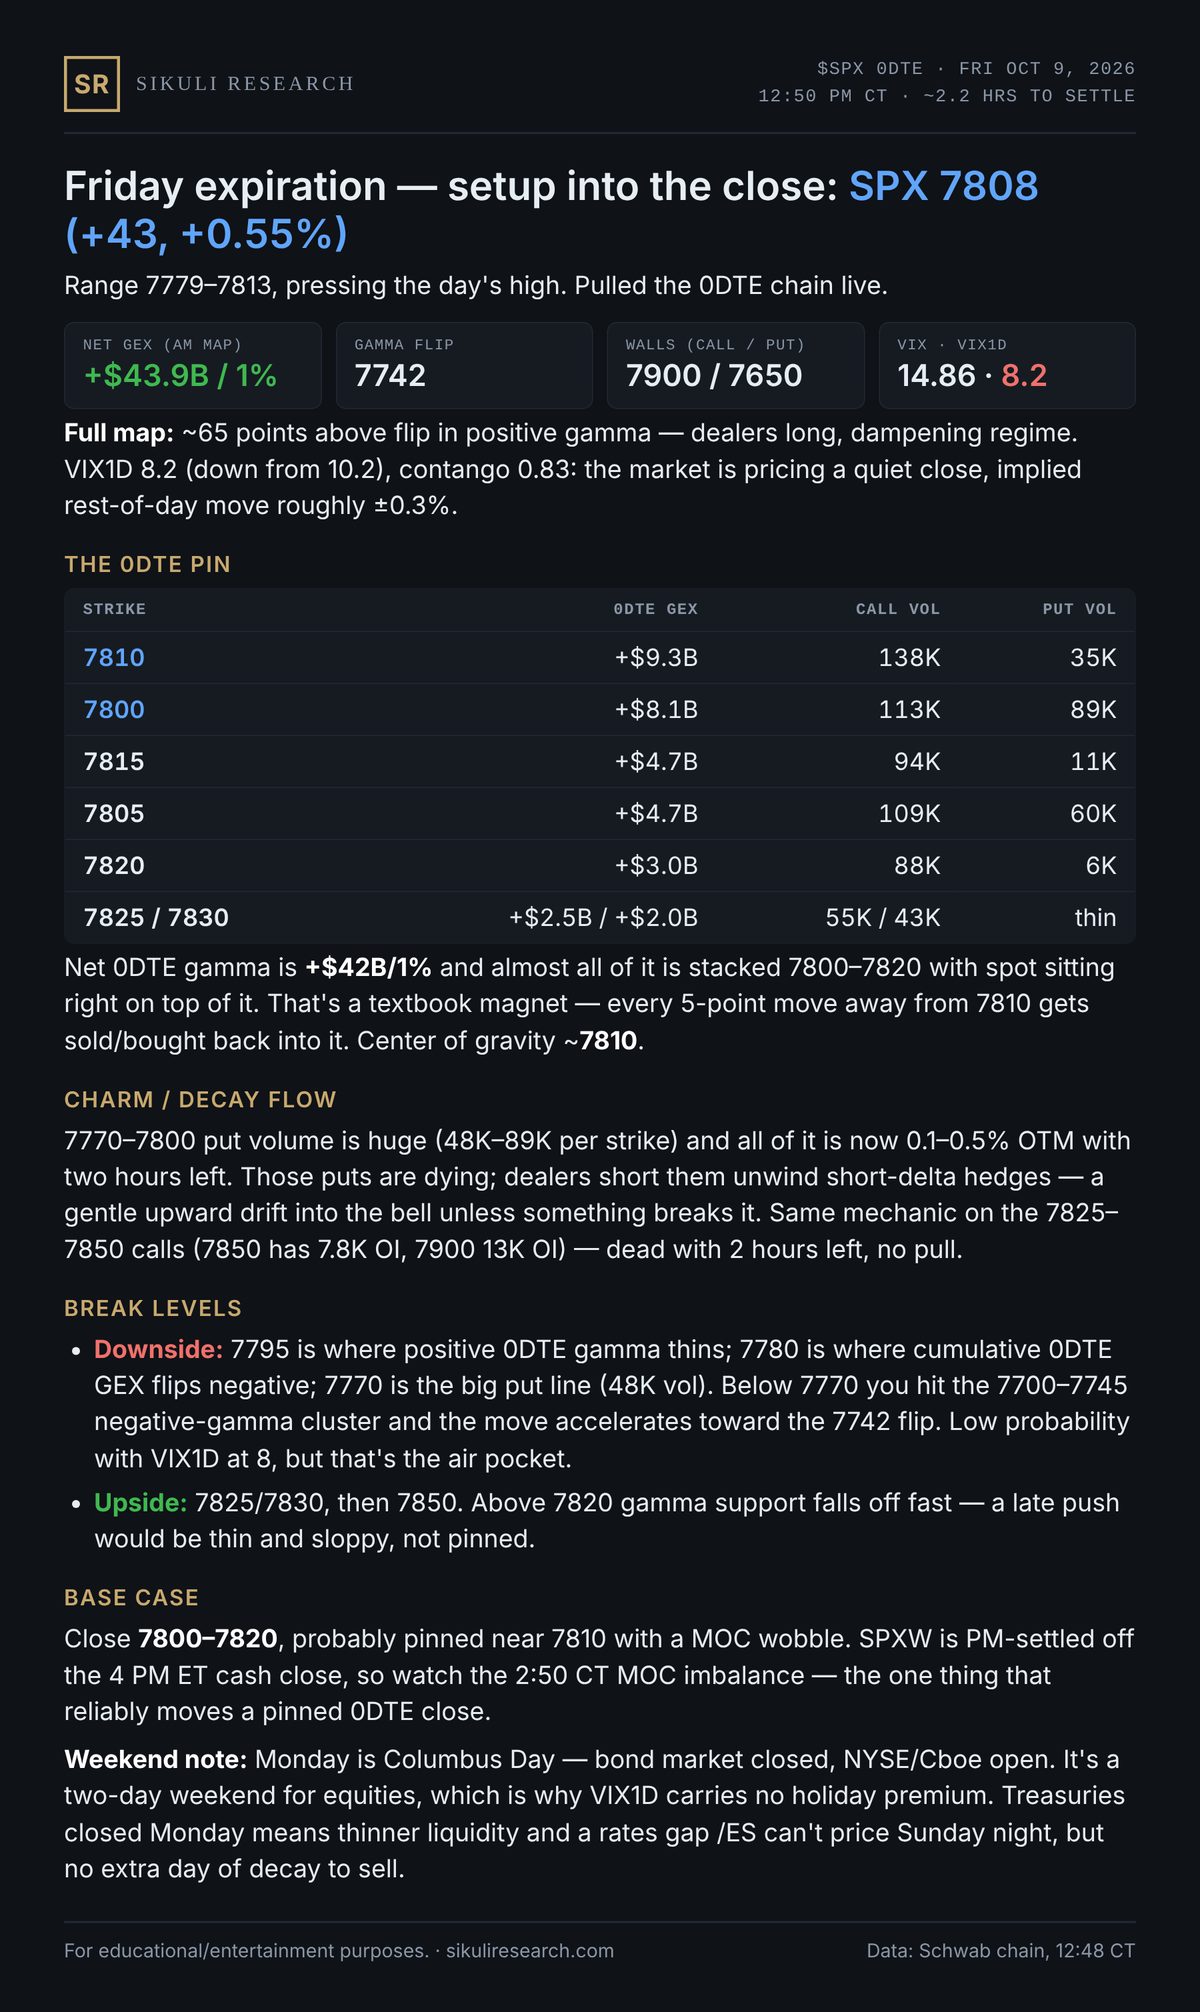
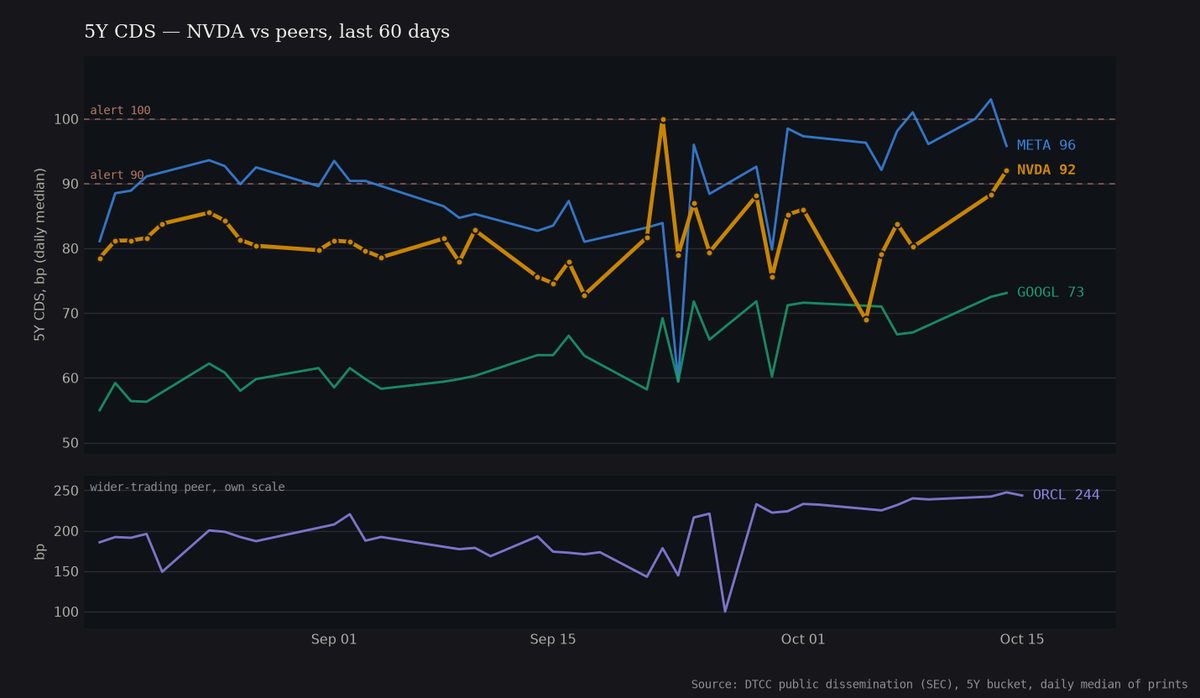
9 prints, Oct 08. Peers: META 96, GOOGL 67, ORCL 239. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
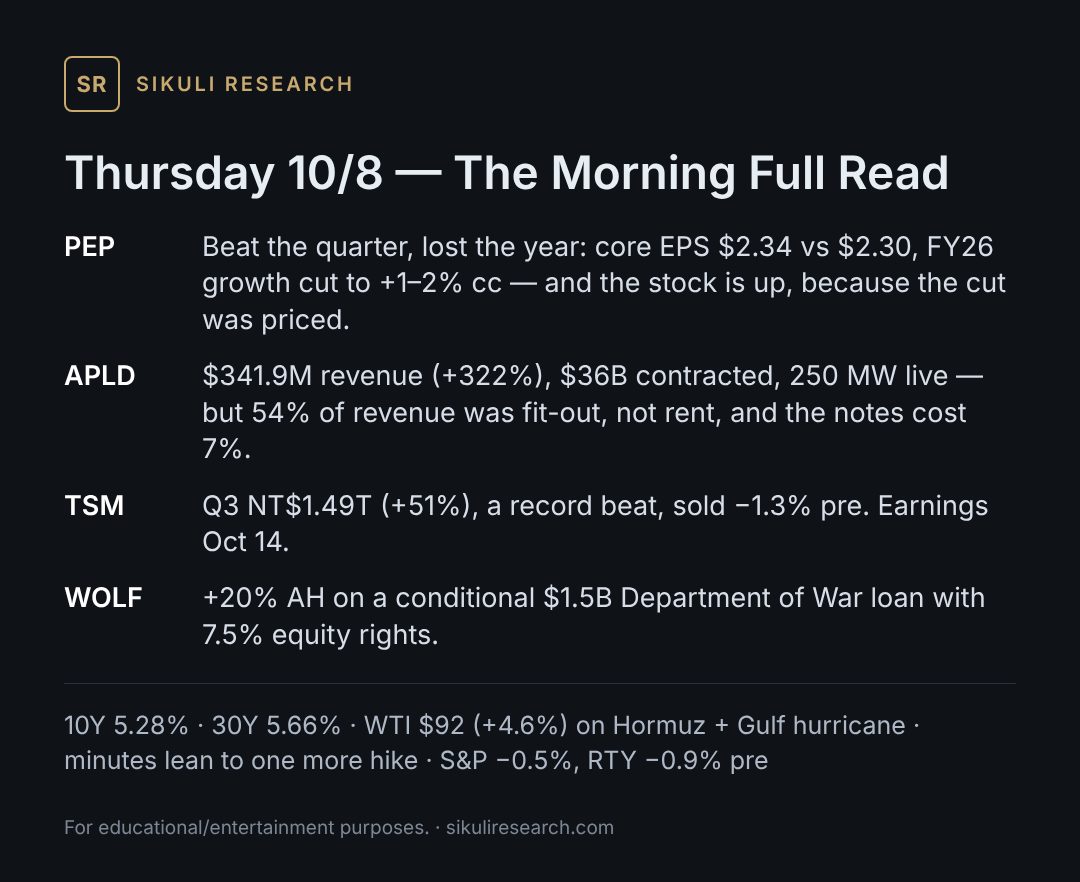
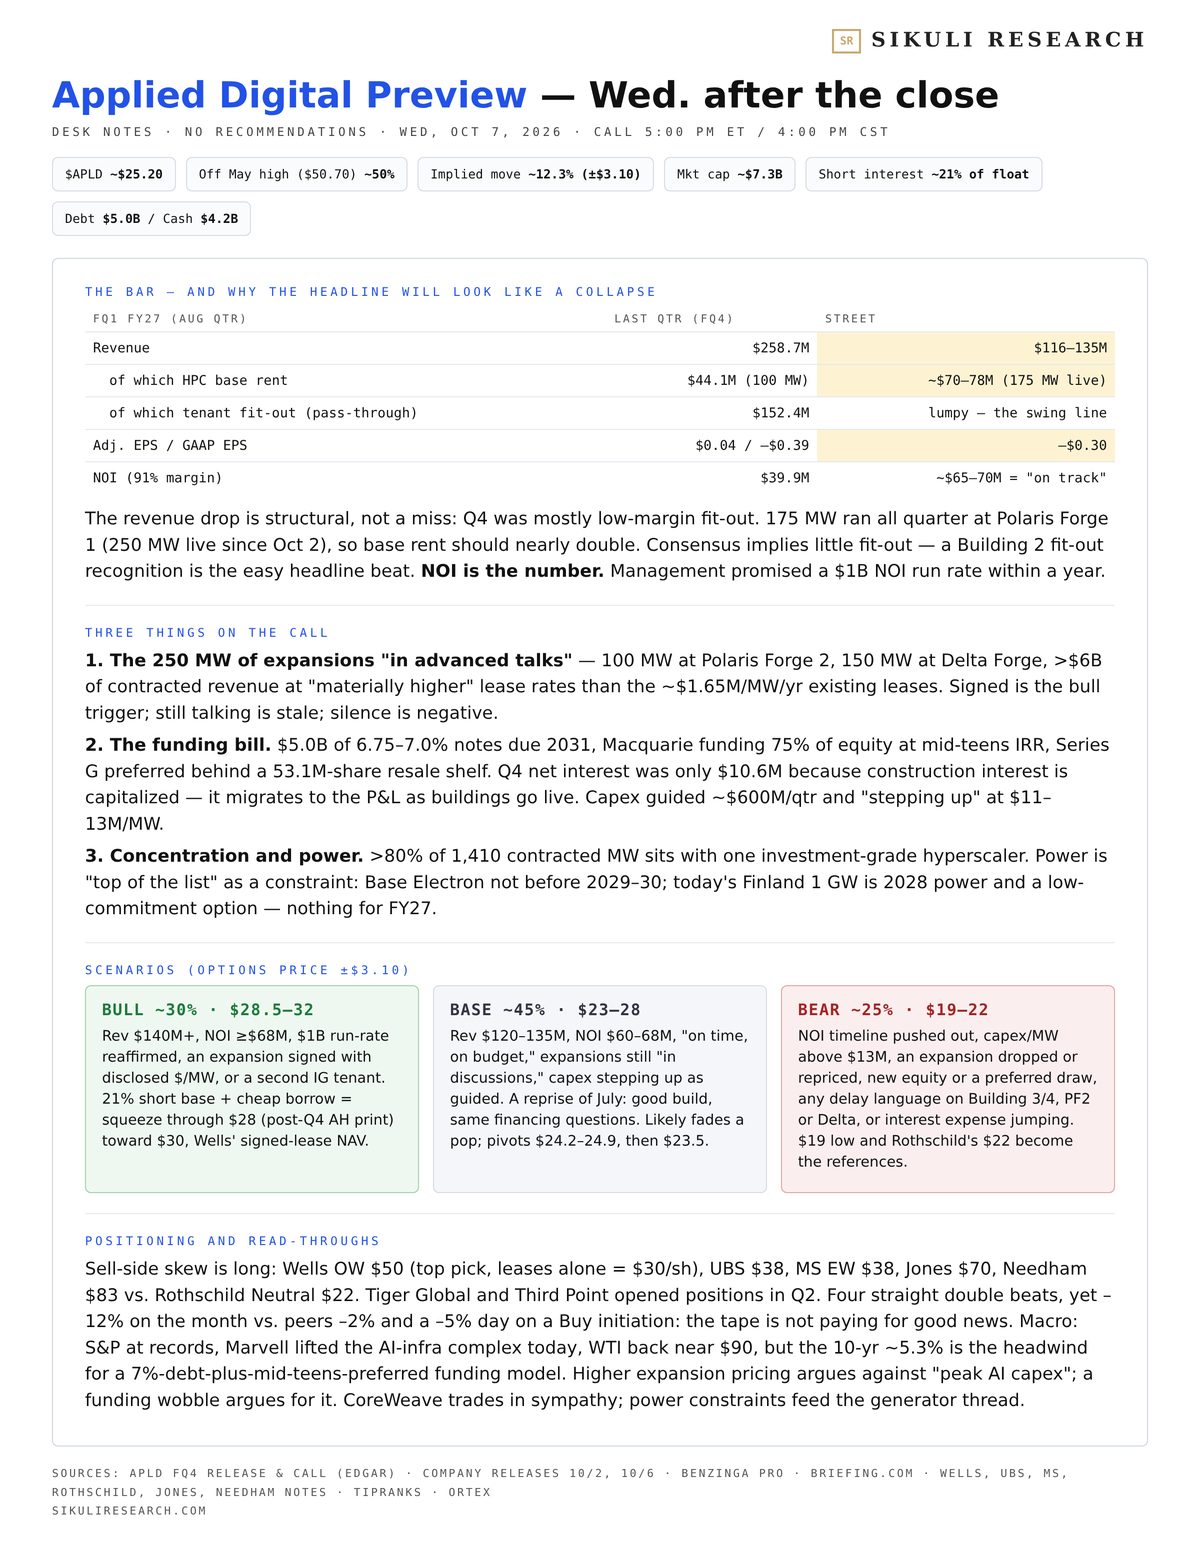
PEP beat the quarter and cut the year, and the stock is up because the cut was priced. APLD: $36B contracted, 7% to fund it. TSM record beat, sold. 10Y 5.28%, WTI $92. Full read at Sikuli Research (link in bio)
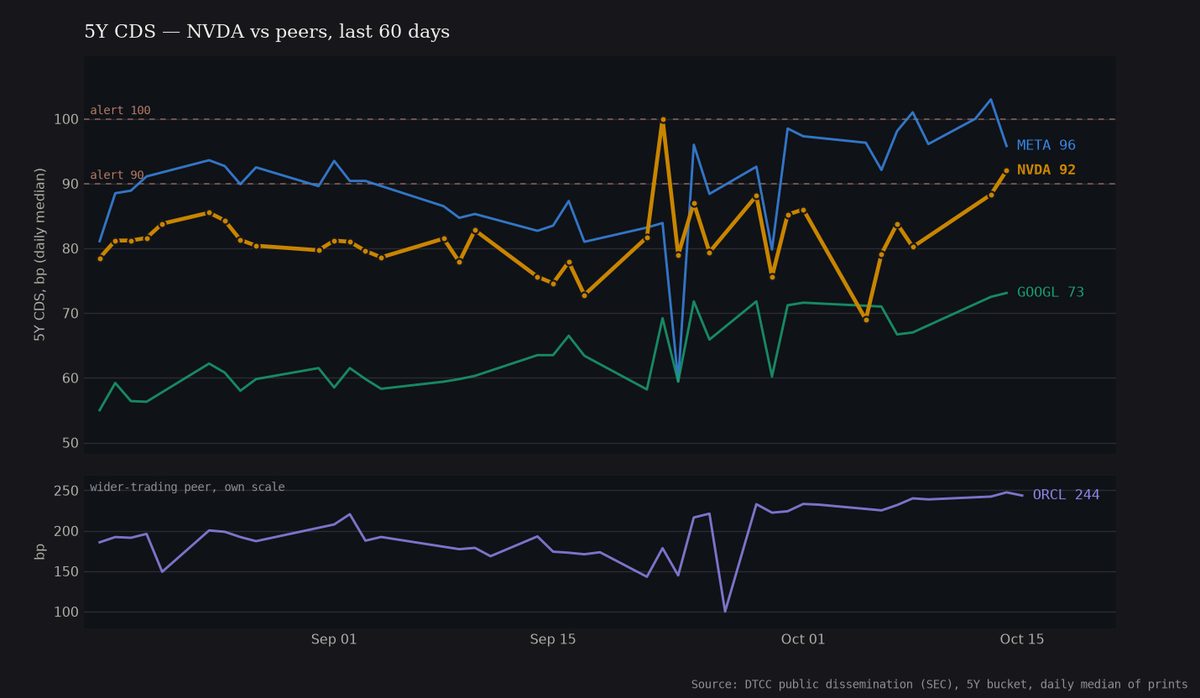
1 prints, Oct 07. Peers: META 92, GOOGL 71, ORCL 234. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
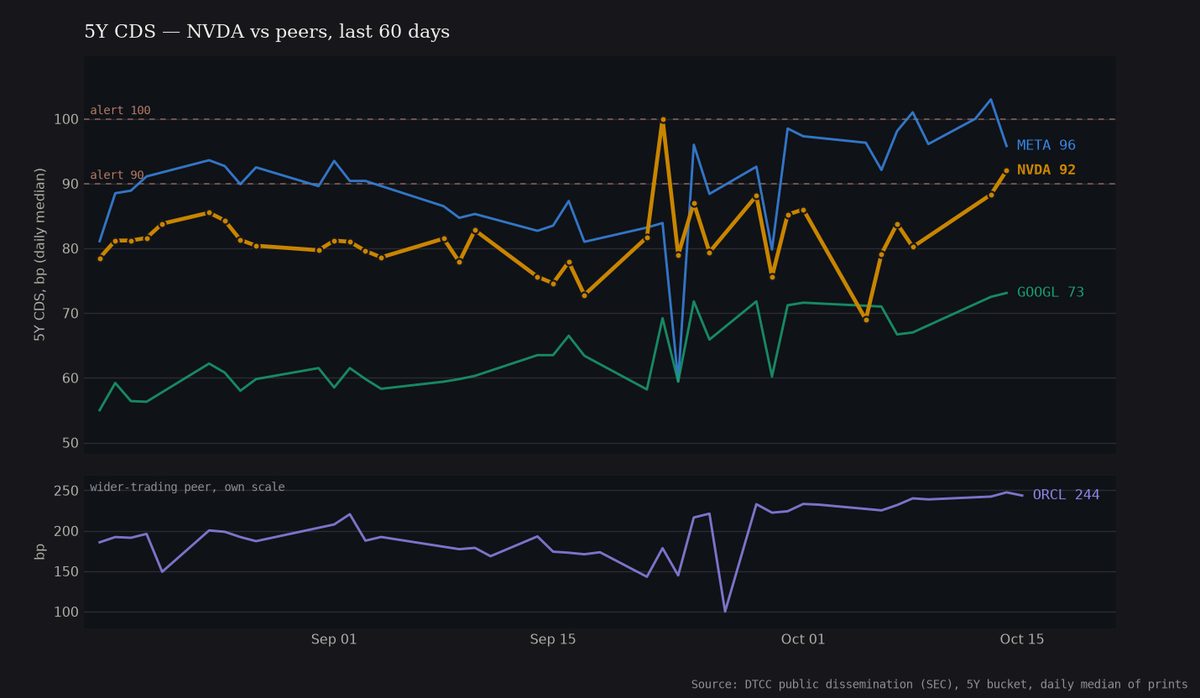
5 prints, Oct 05. Peers: META 96, GOOGL 72, ORCL 227. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
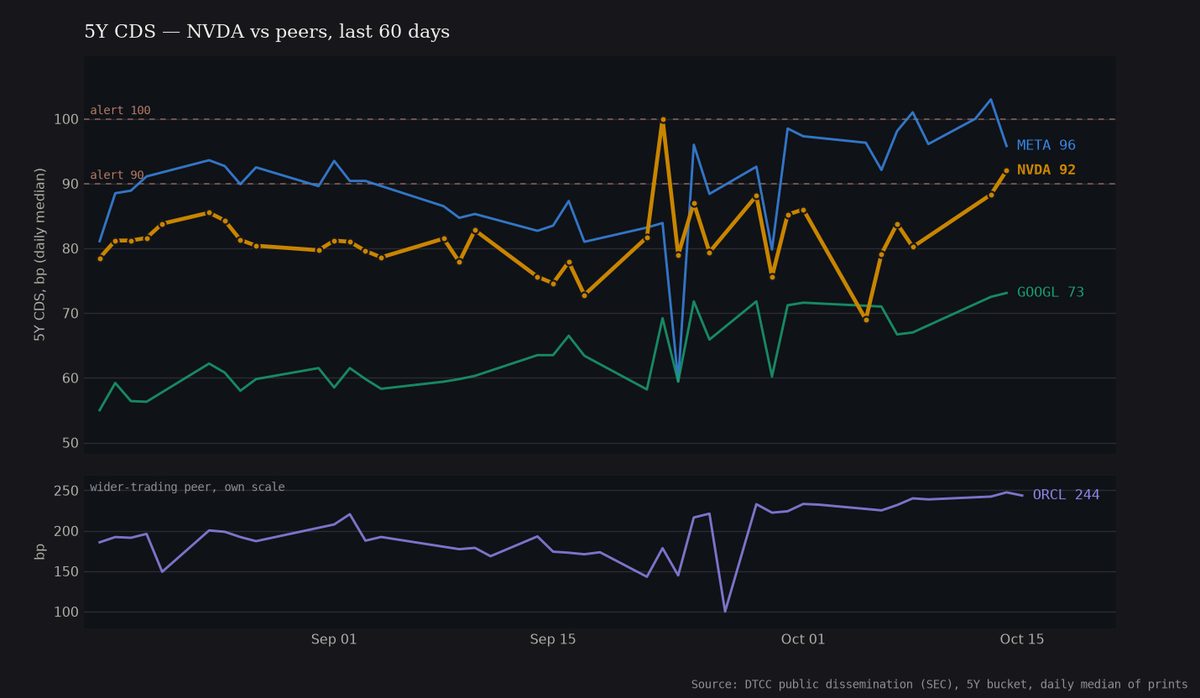
11 prints, Oct 01. Peers: META 97, GOOGL 72, ORCL 232. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
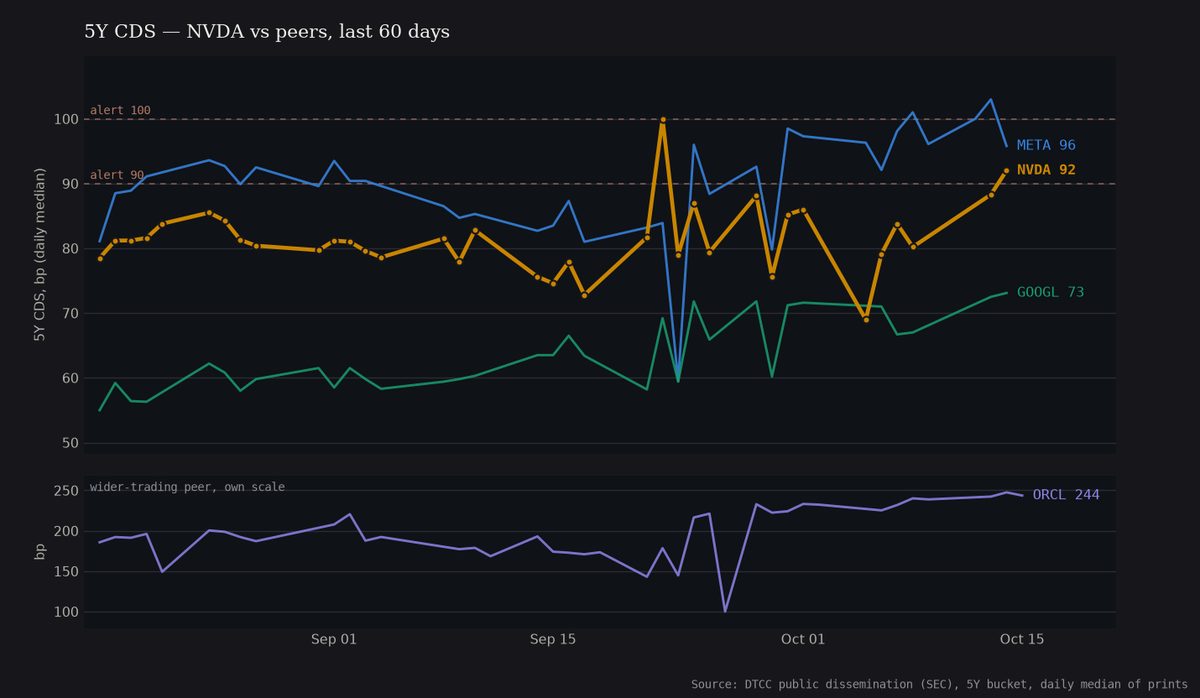
1 prints, Sep 30. Peers: META 98, GOOGL 71, ORCL 224. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
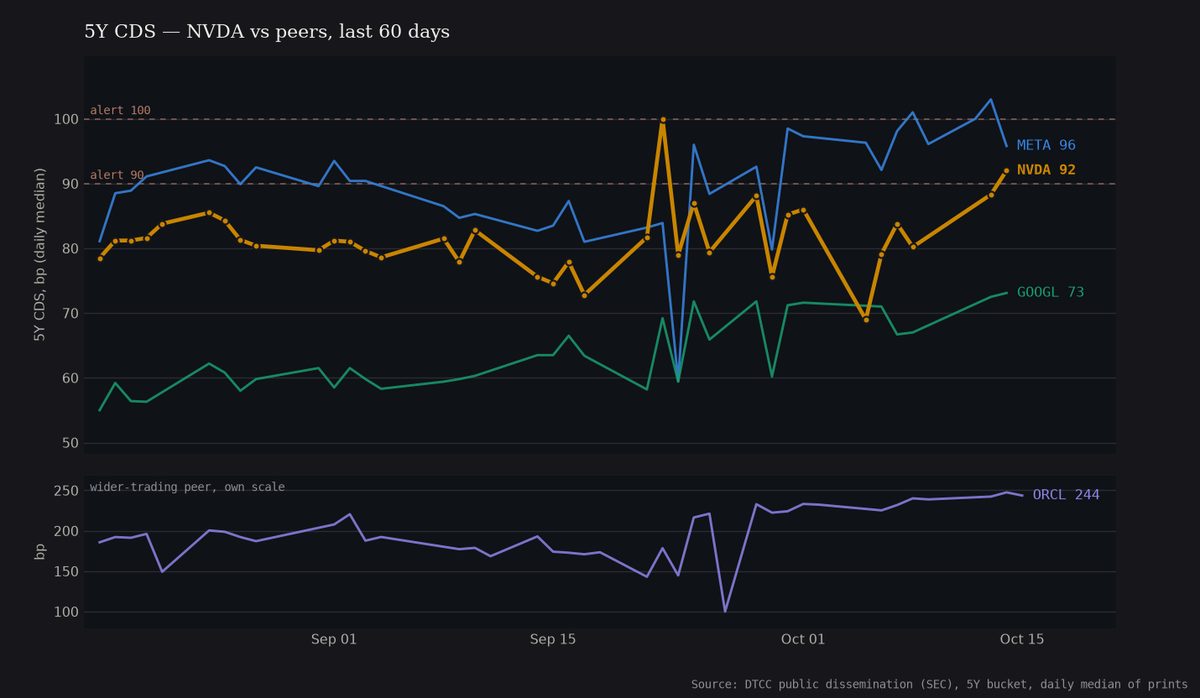
3 prints, Sep 29. Peers: META 98, GOOGL 60, ORCL 222. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
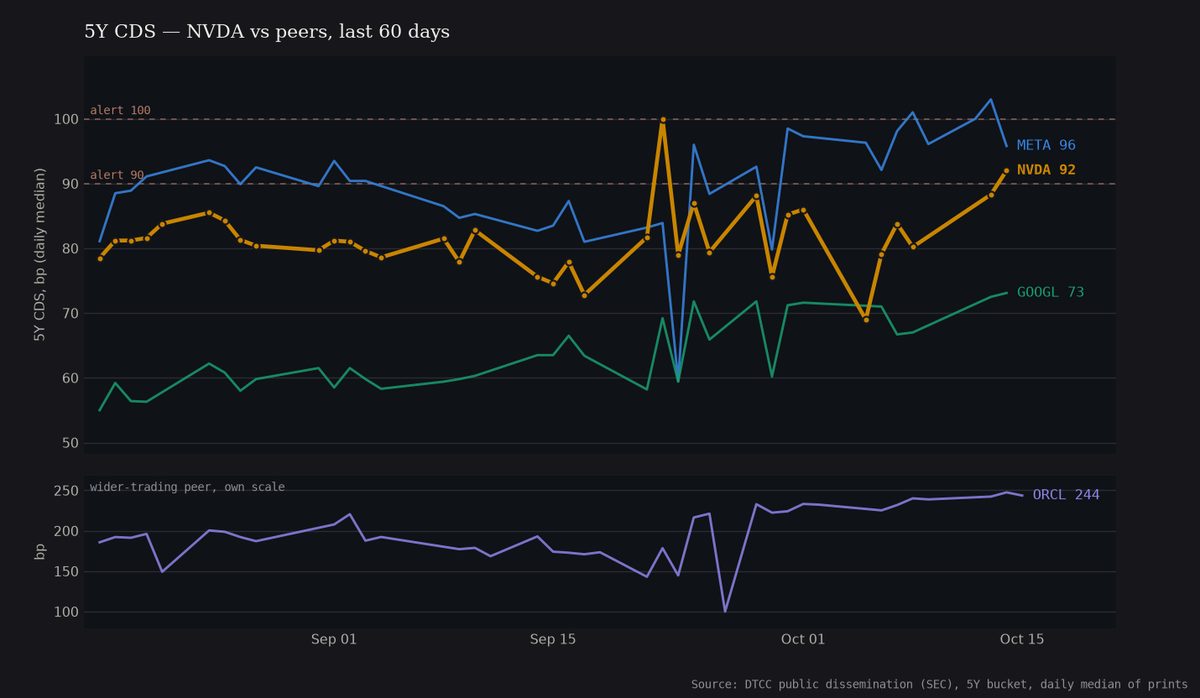
1 prints, Sep 28. Peers: META 92, GOOGL 66, ORCL 100. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
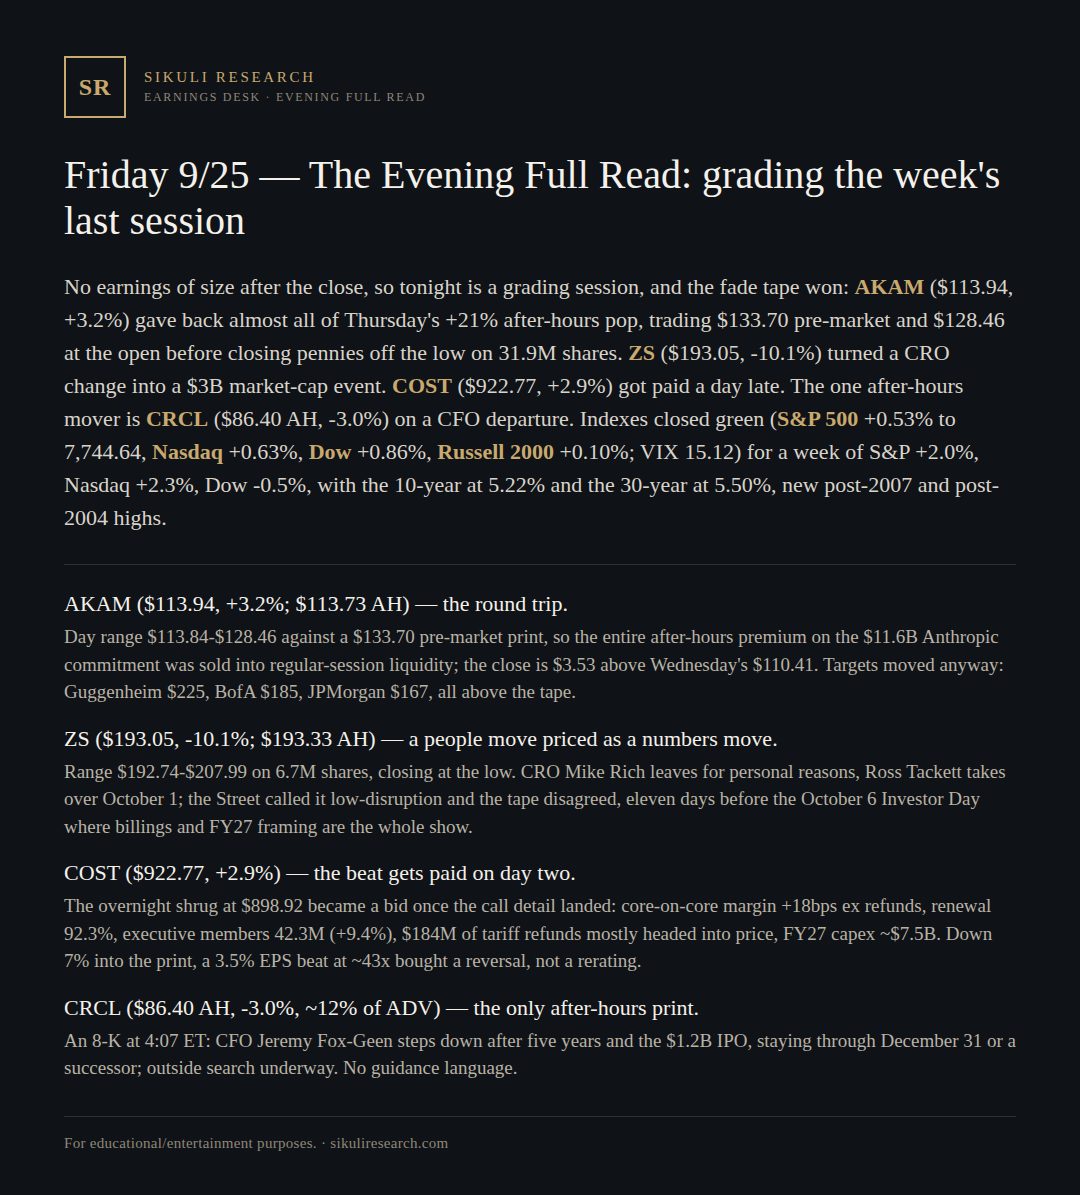
No prints of size after the close, so the fade tape graded the week: AKAM round-tripped its +21% Anthropic pop to close +3%, ZS -10% on a CRO change, COST paid a day late. 10-yr 5.22%. MU Tuesday. Full read at Sikuli Research (link in bio)
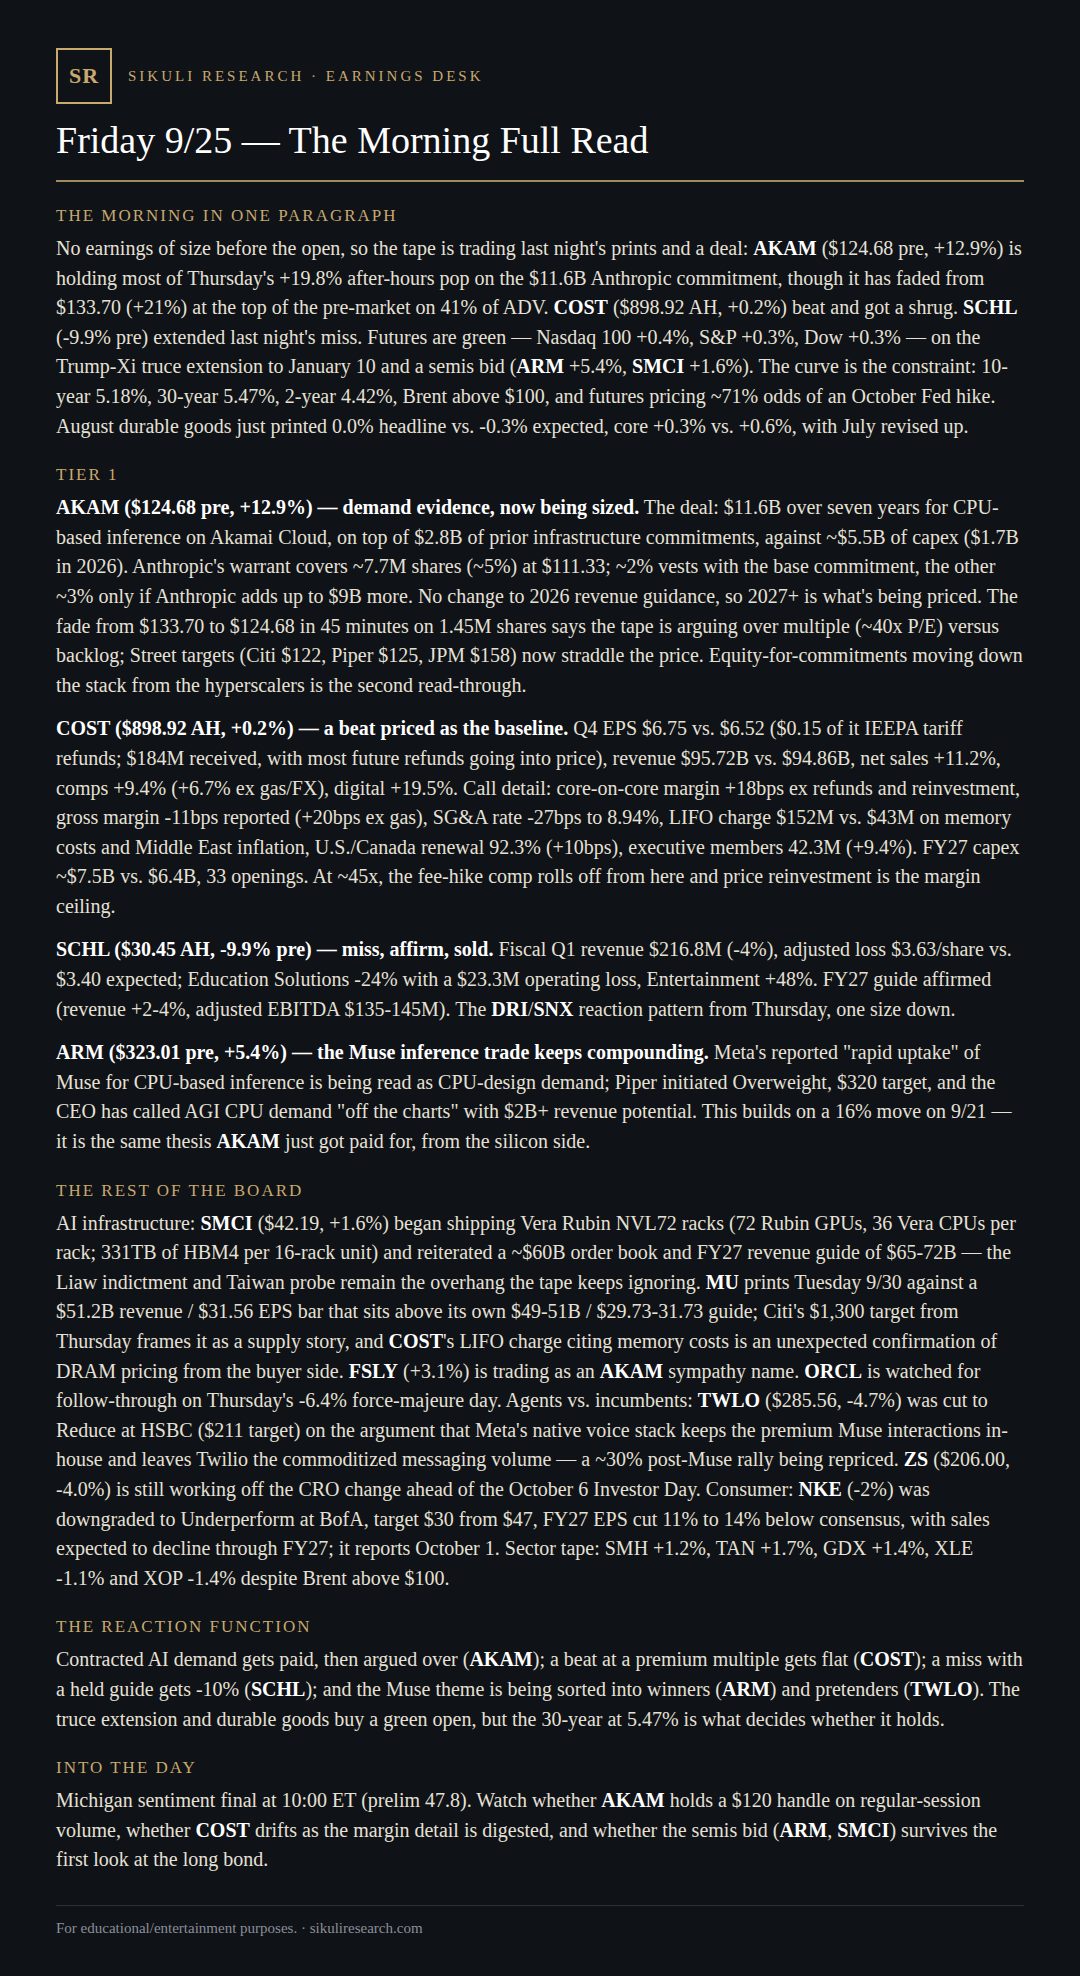
AKAM holds +13% pre on the $11.6B Anthropic deal after a +21% high; COST beats, gets flat; SCHL -10% on a miss. Futures green on the Trump-Xi truce and semis (ARM +5%); 30-year at 5.47%. Full read at Sikuli Research (link in bio)
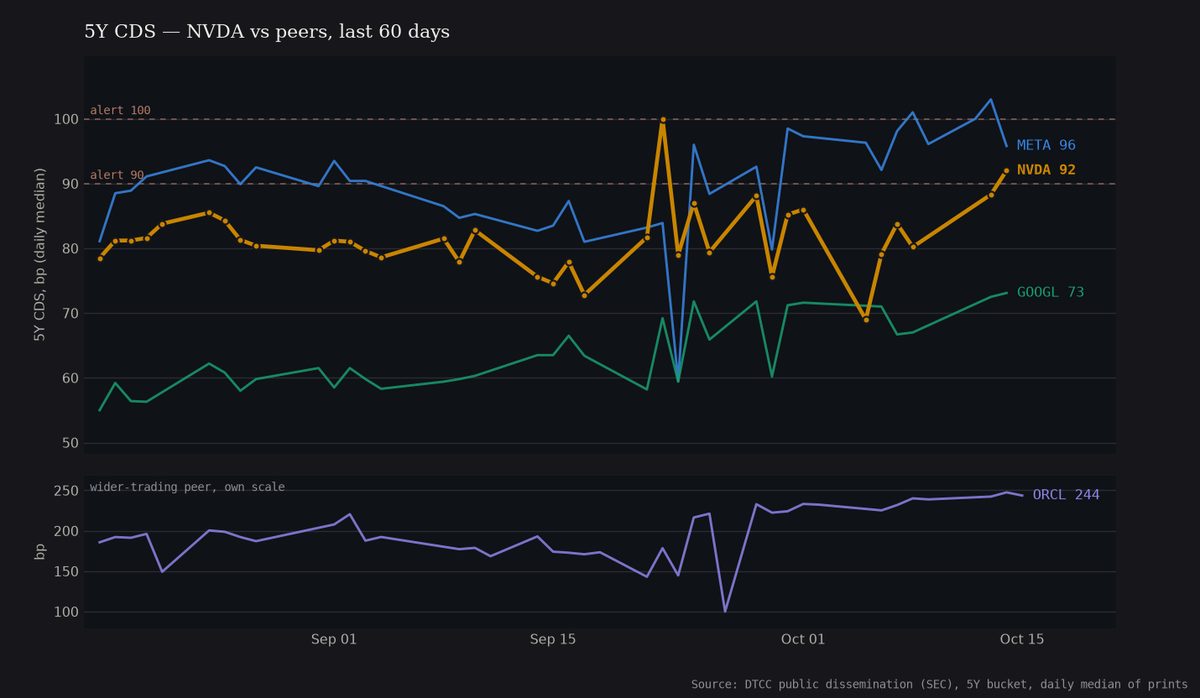
2 prints, Sep 25. Peers: META 96, GOOGL 72, ORCL 214. Cost of default protection - the AI-complex credit canary. Daily median of DTCC public prints. Not advice.
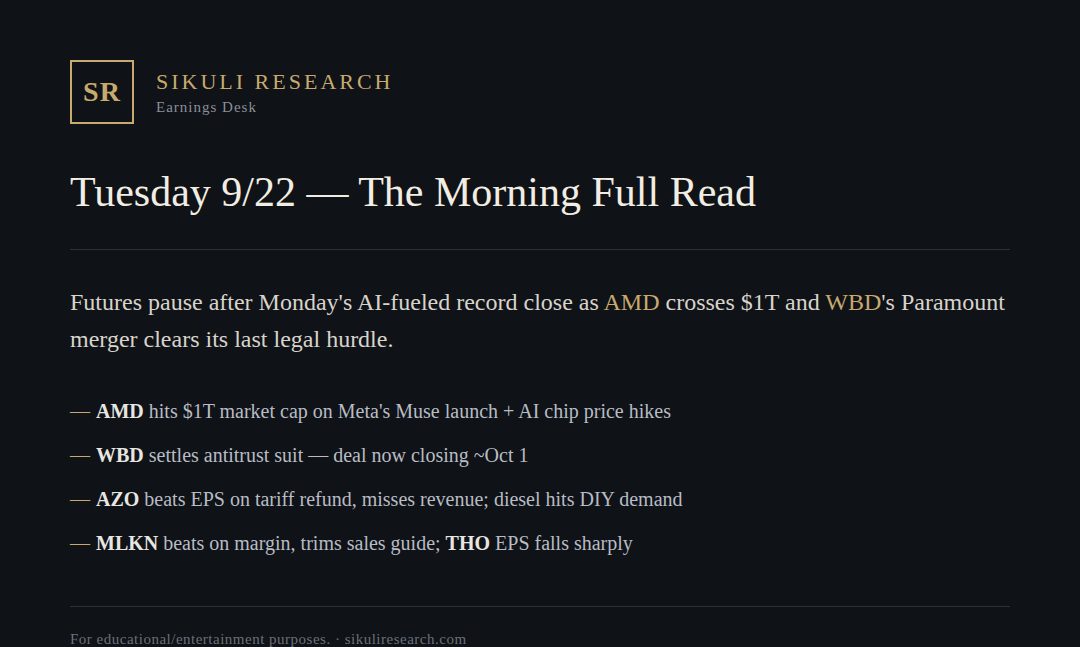
AMD crosses $1T on Meta's Muse launch as WBD's Paramount merger clears its last legal hurdle; AZO beats EPS, misses revenue. Full read at Sikuli Research (link in bio)
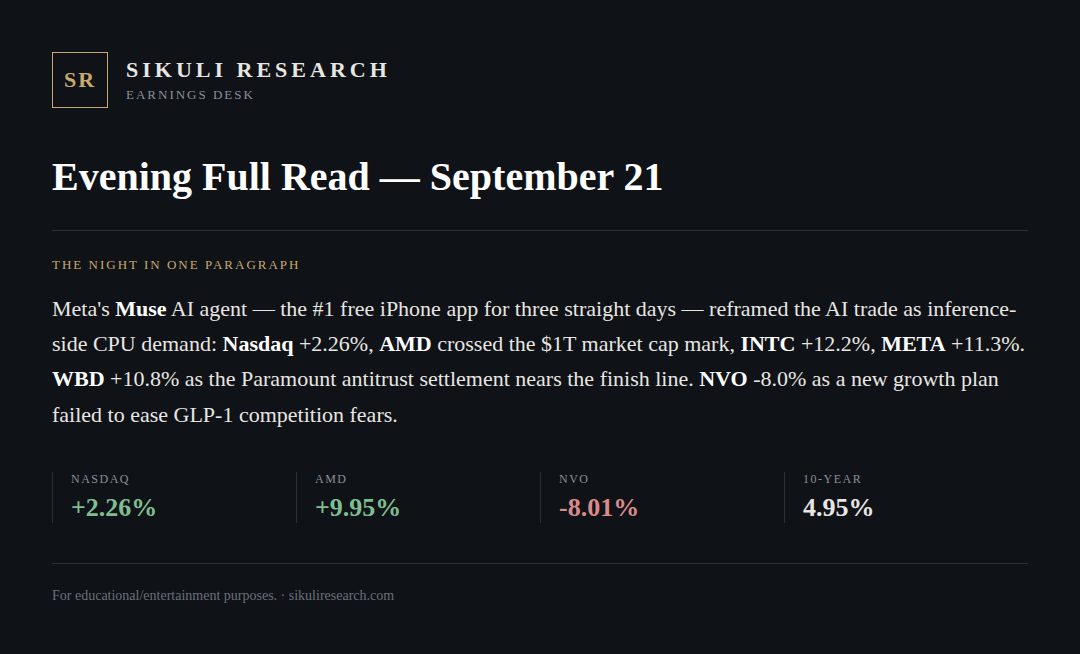
Muse (Meta's AI agent) hit #1 free iPhone app 3 days running — Nasdaq +2.26%, AMD crossed $1T cap, INTC +12%, META +11% on inference-chip demand. WBD +10.8% on Paramount settlement progress. NVO -8%. Full read at Sikuli Research (link in bio)
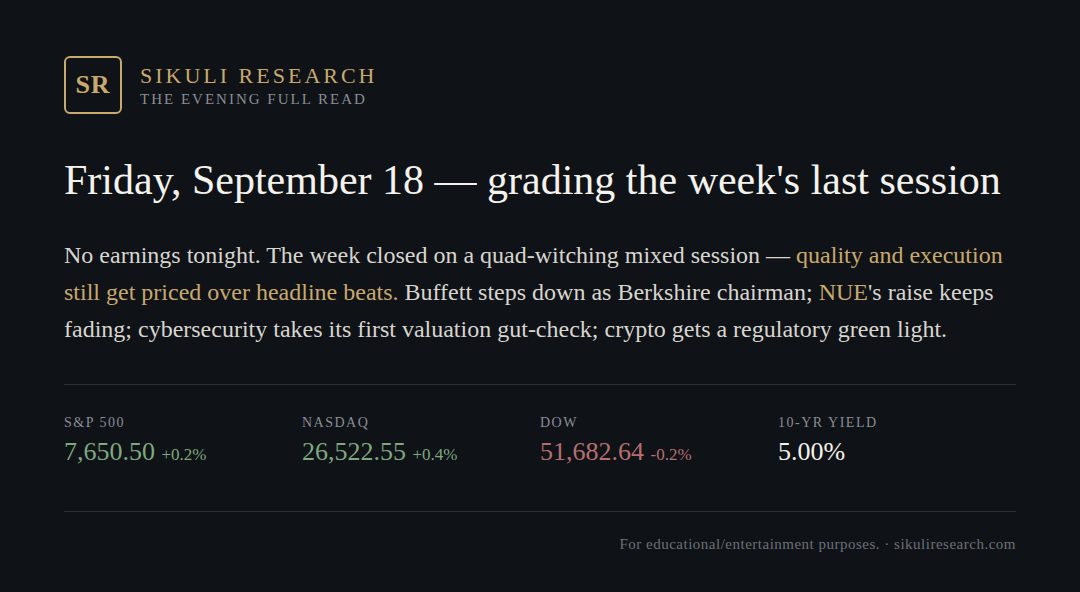
No earnings tonight. Quiet, mixed quad-witching close: Buffett steps down as Berkshire chairman, NUE's raise keeps fading, cybersecurity's first valuation gut-check. Full read at Sikuli Research (link in bio)
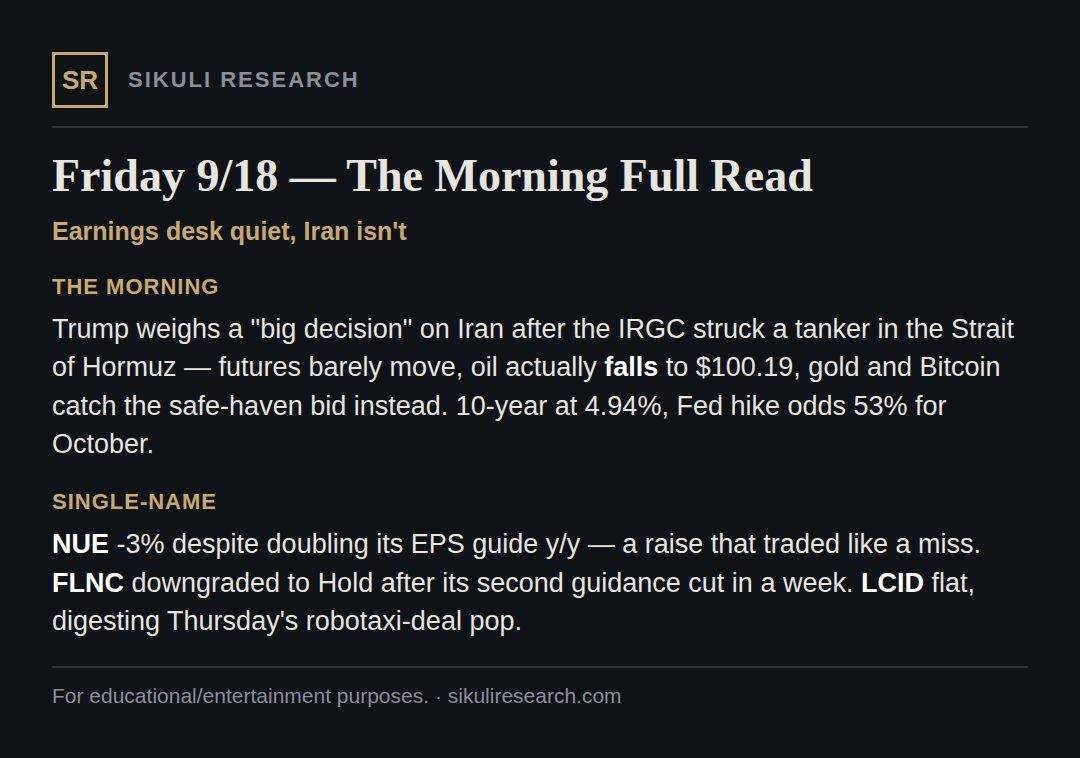
Iran overshadows an empty earnings tape: Trump weighs a "big decision" after a tanker strike in Hormuz; oil dips while gold and BTC catch the safe-haven bid. NUE, FLNC and LCID lead single-name action. Full read at Sikuli Research (link in bio)
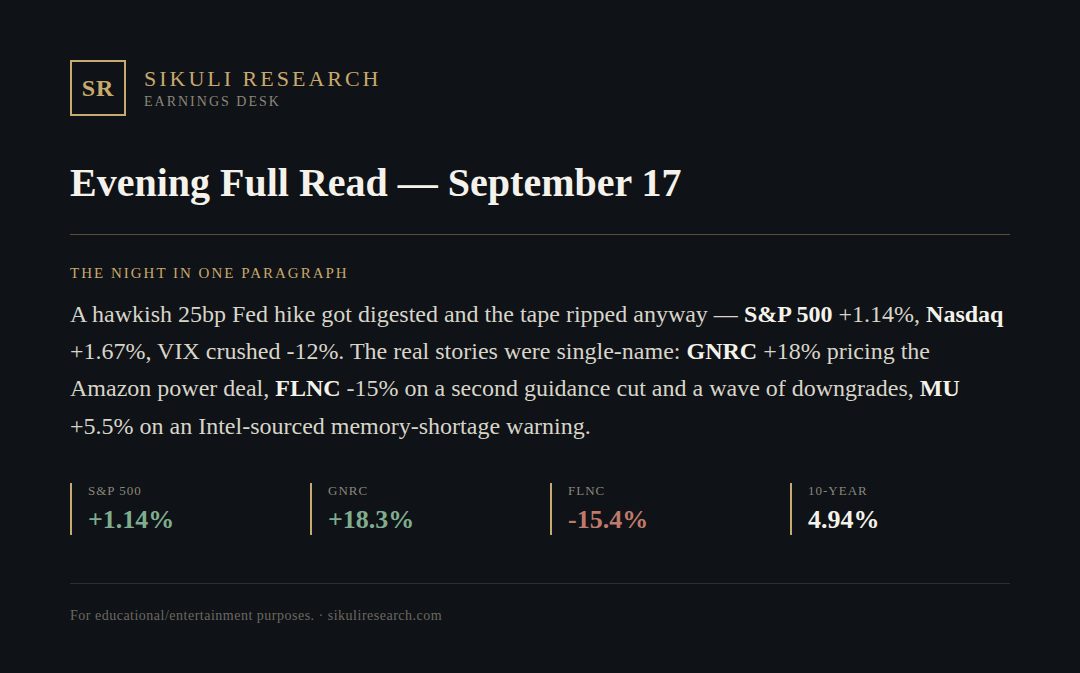
Fed hiked 25bp Wed, market ripped anyway: S&P +1.1%, VIX -12%. GNRC +18% on the Amazon deal's first real session, FLNC -15% on a 2nd guidance cut, MU +5.5% on an Intel memory-shortage warning. Full read at Sikuli Research (link in bio)
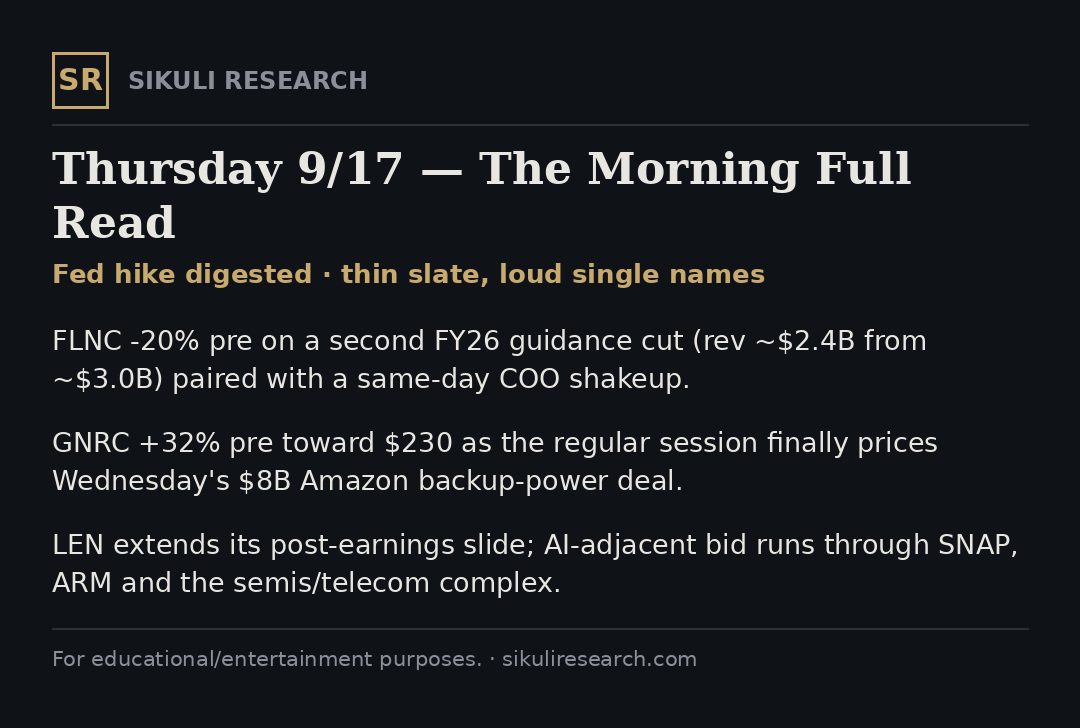
Fed hike digested; thin earnings slate. Real action: FLNC's guidance cut + COO shakeup, GNRC finally pricing the Amazon deal, LEN's post-earnings slide. Full read at Sikuli Research (link in bio)
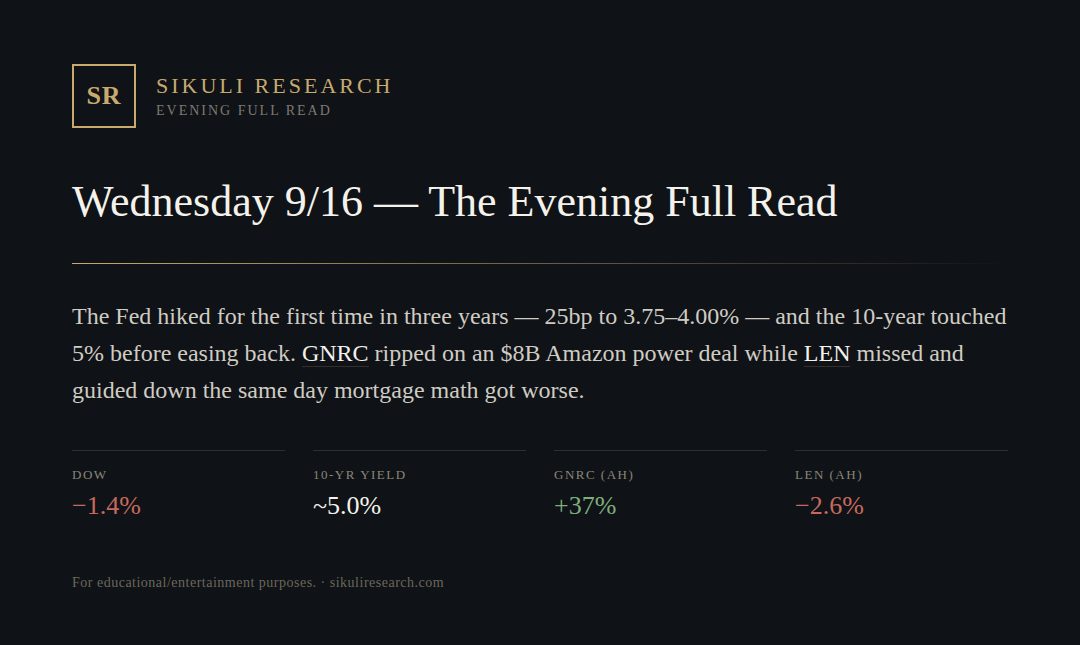
Fed hikes for first time in 3 years (25bp to 3.75-4.00%), 10-yr touches 5%. GNRC rips +37% AH on $8B Amazon power deal; LEN misses & guides down as mortgage math gets worse. Full read at Sikuli Research (link in bio)
Fed day, thin slate: TCOM +4% on a beat, oil caps long-haul; LUXE guides margins up. The bid is the compute bounce (INTC/SK Hynix fab talks, MRVL) into a 92.5%-priced hike, tens at 5%. Full read at Sikuli Research (link in bio)
Fed day, thinnest slate of the month: TCOM +4% on the beat but names oil as the long-haul governor; LUXE guides margins up. The bid is the compute bounce — INTC/SK Hynix U.S. fab talks, MRVL — into a 92.5%-priced hike with tens at 5.00%. Full read at Sikuli Research (link in bio)
TCOM beats but EBITDA slips; FPS backlog +256%. Ten-year closes at 5.00% into the Fed, AI-safety rotation stalls, crypto takes the hit. Full read at Sikuli Research (link in bio)
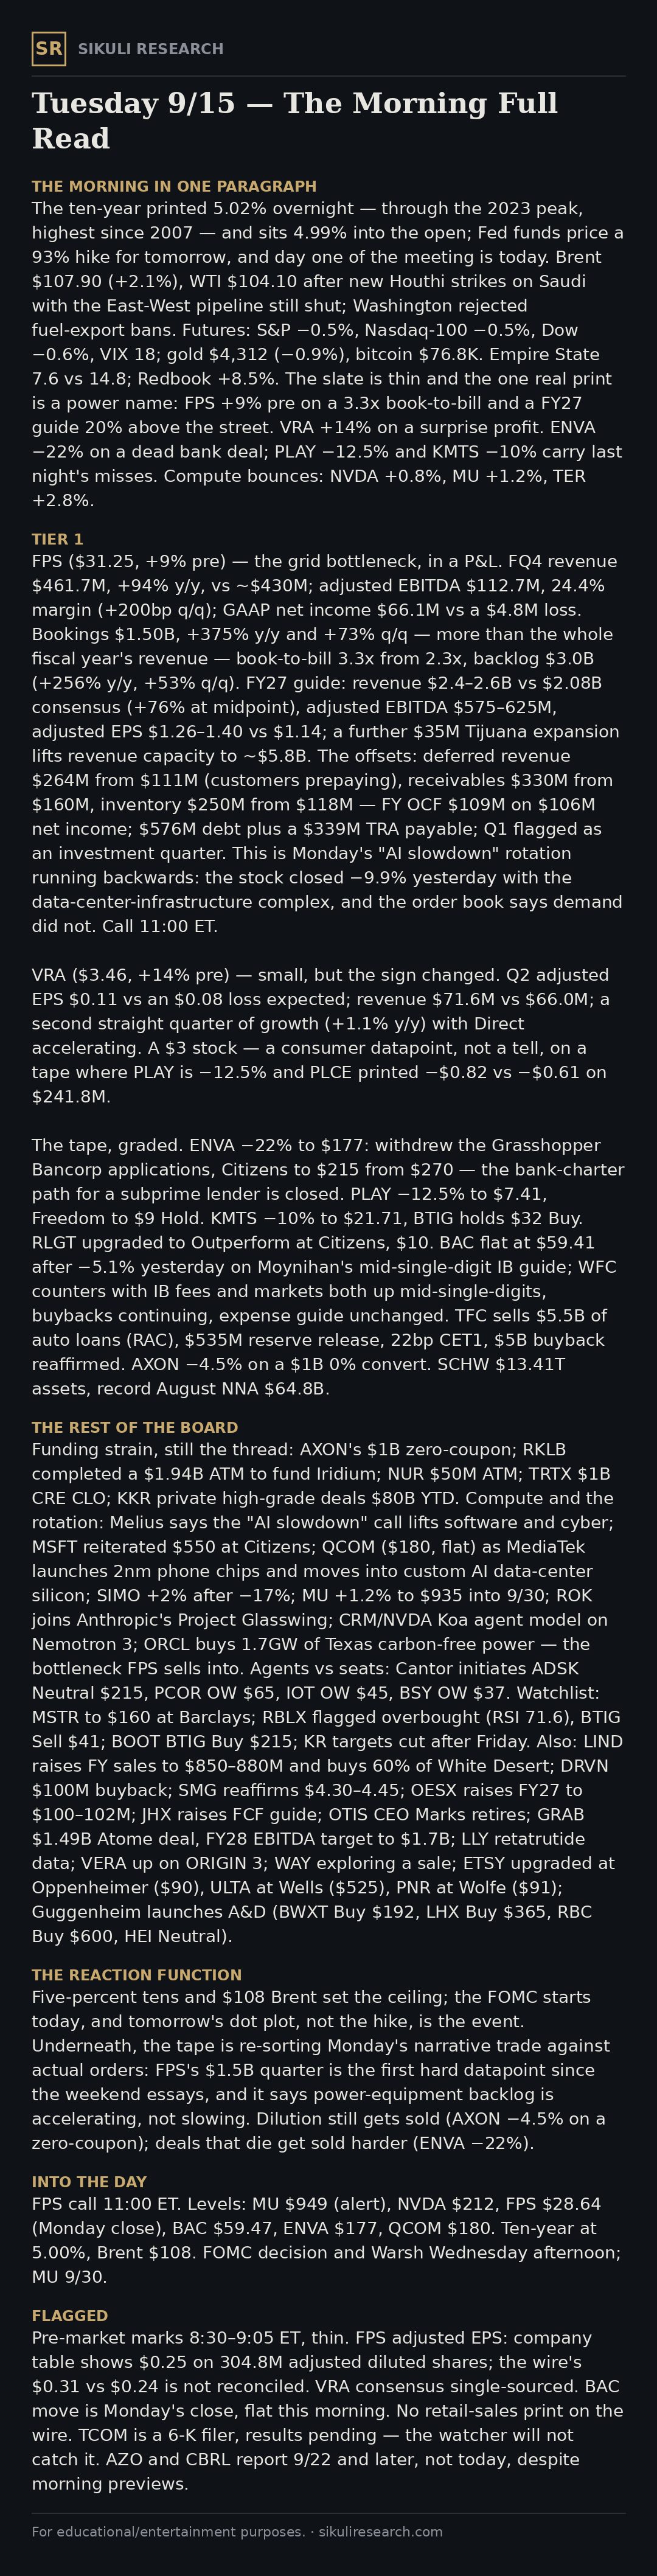
FPS +9% pre: $1.5B bookings, 3.3x book-to-bill, FY27 guide 20% above the street — the order book says Monday's "AI slowdown" trade got demand wrong. Ten-year 5.02%, Brent $108, 93% hike odds into FOMC. Full read at Sikuli Research (link in bio)
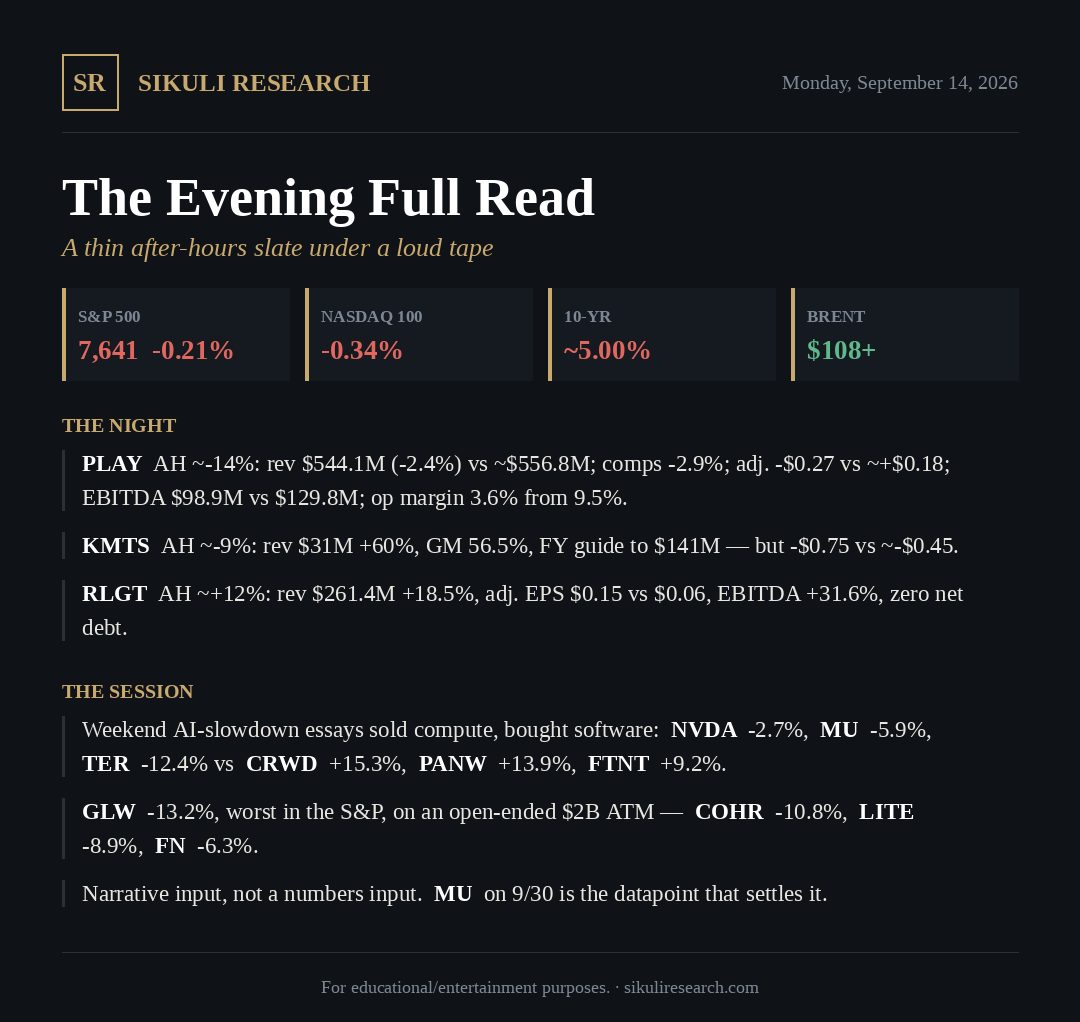
PLAY -14% AH: comps -2.9%, EBITDA $98.9M vs $129.8M. But the session was the story — weekend AI-slowdown essays sold compute and bought software, and GLW -13% on an open-ended $2B ATM. Full read at Sikuli Research (link in bio)
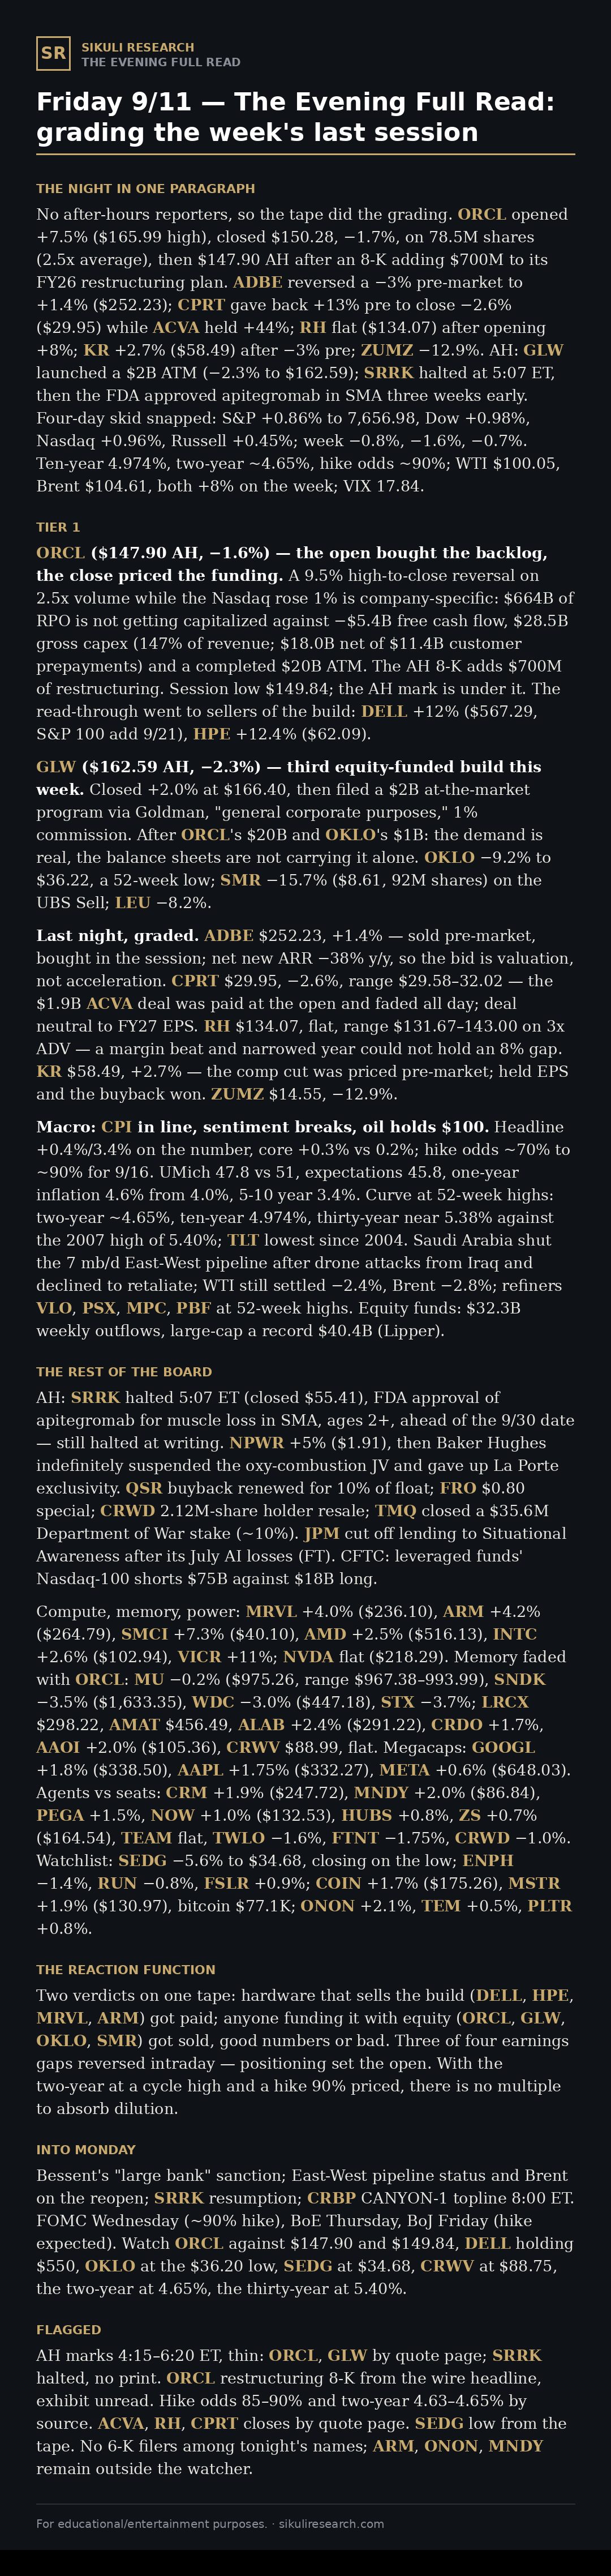
No AH prints; the tape graded. ORCL erased a 7.5% gap to close −1.7%, fell again AH on a $700M restructuring add; GLW filed a $2B ATM. Build sellers (DELL, HPE +12%) paid; equity-funded builders sold. Full read at Sikuli Research (link in bio)
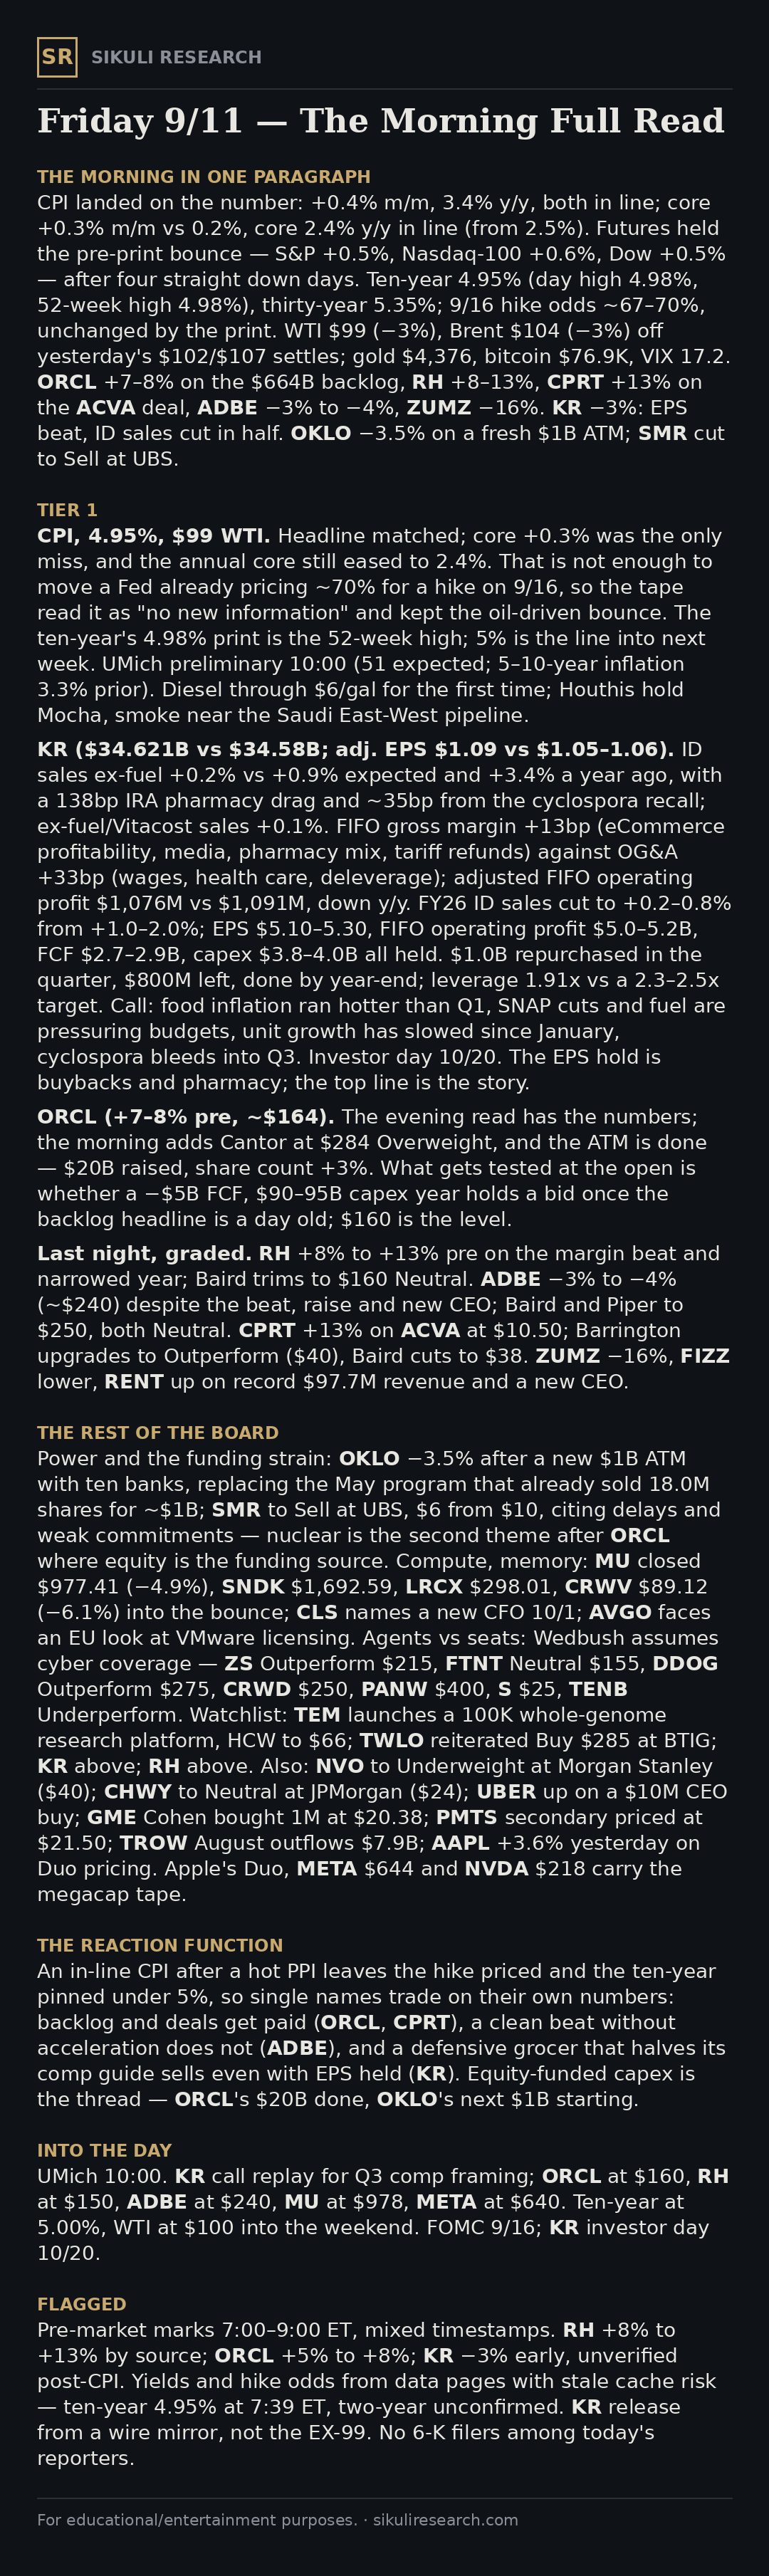
CPI in line (0.4% m/m, 3.4% y/y; core 0.3%); hike odds ~70% unmoved, ten-year 4.95%, WTI $99. ORCL +7%, RH up, ADBE −3%. Kroger beats on EPS, halves its comp guide, −3%. OKLO's next $1B ATM. Full read at Sikuli Research (link in bio)
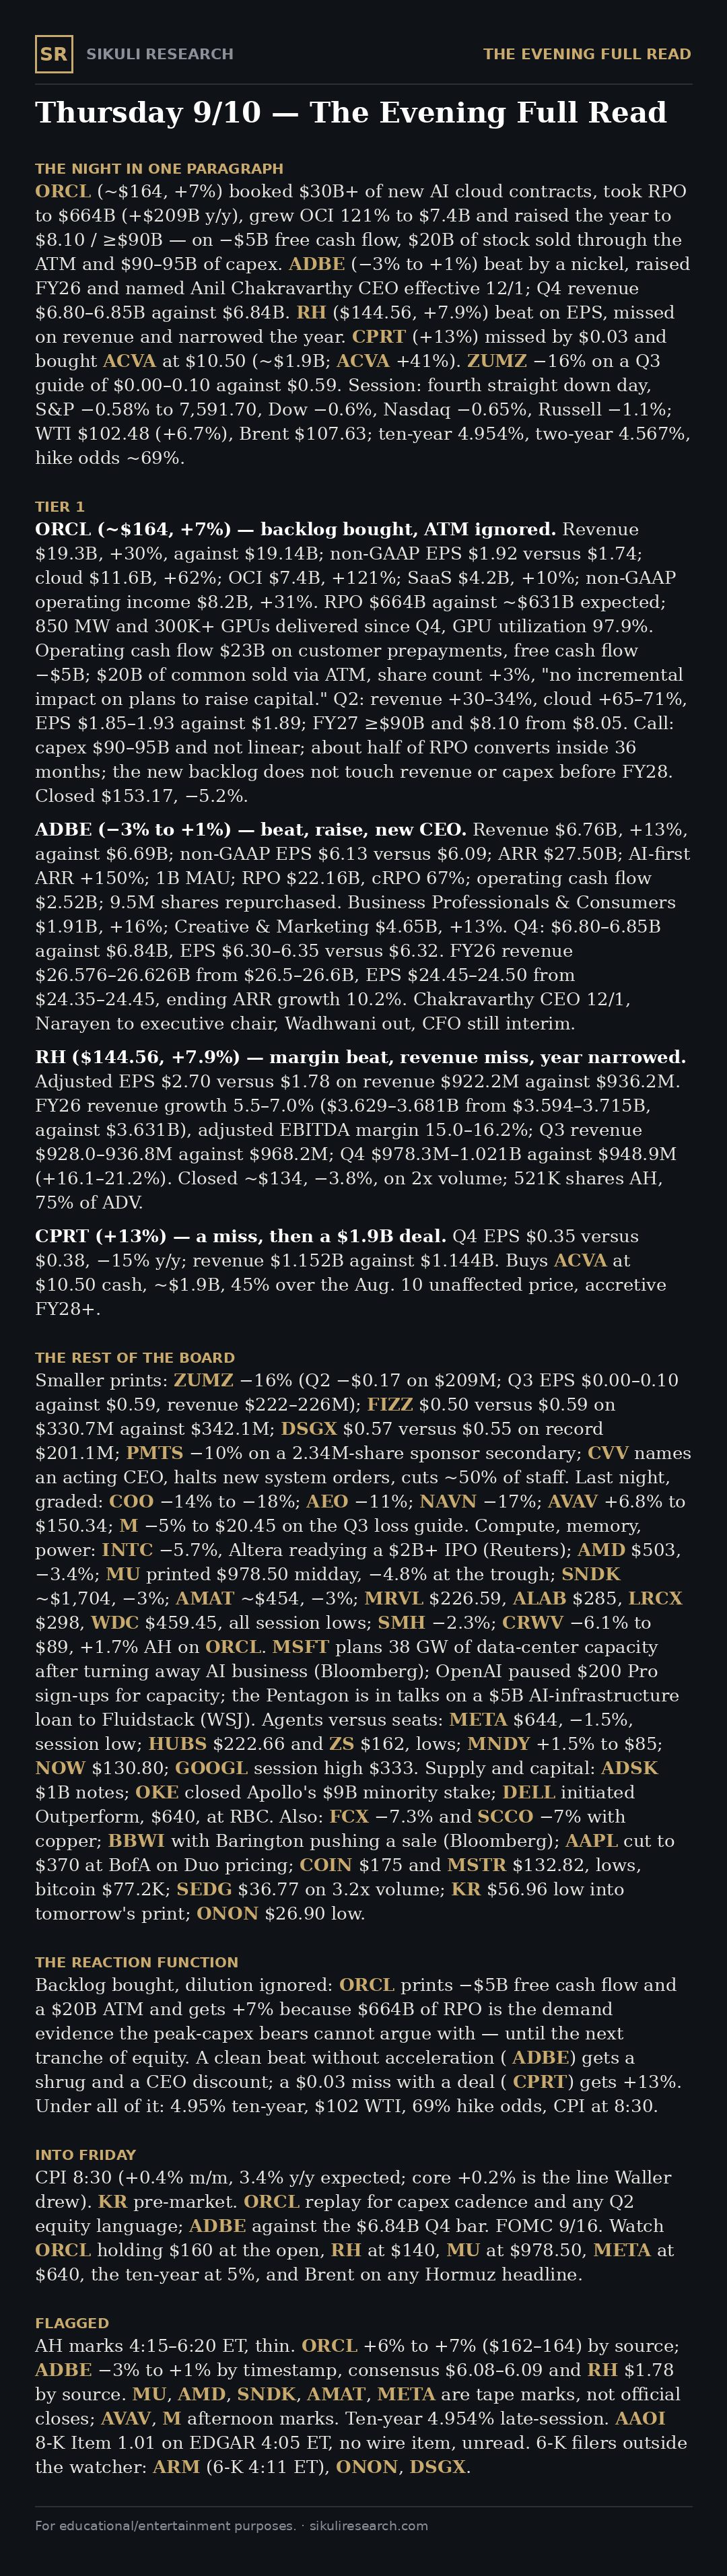
ORCL +7% AH: $30B of new AI contracts, RPO $664B, OCI +121% — on −$5B FCF and a $20B ATM. ADBE beat, raised, named a new CEO; flat AH. RH +8%, CPRT +13% on the ACV deal. 10-yr 4.95%, WTI $102, CPI 8:30. Full read at Sikuli Research (link in bio)
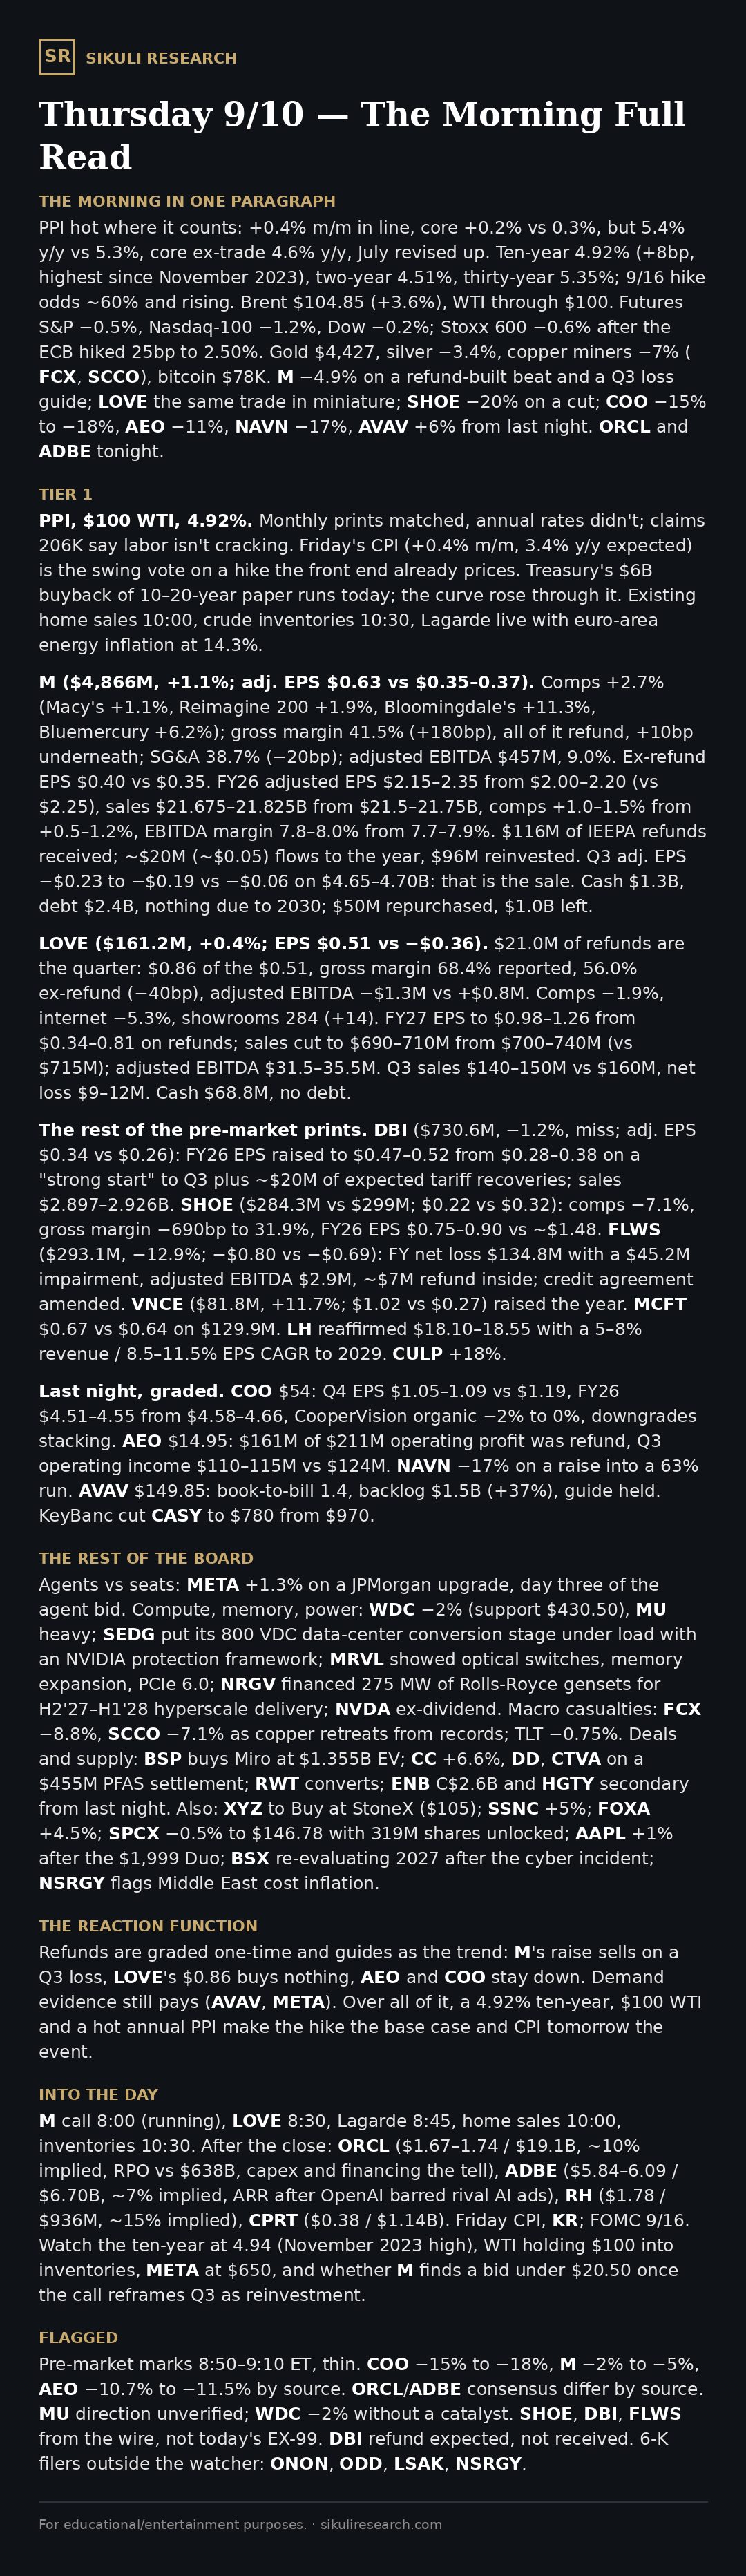
Hot annual PPI (5.4%) sends the 10-year to 4.92% and WTI through $100; hike odds up into CPI. Macy's beats on tariff refunds, guides Q3 to a loss, −5%. COO −15%, AEO −11%. ORCL and ADBE tonight. Full read at Sikuli Research (link in bio)
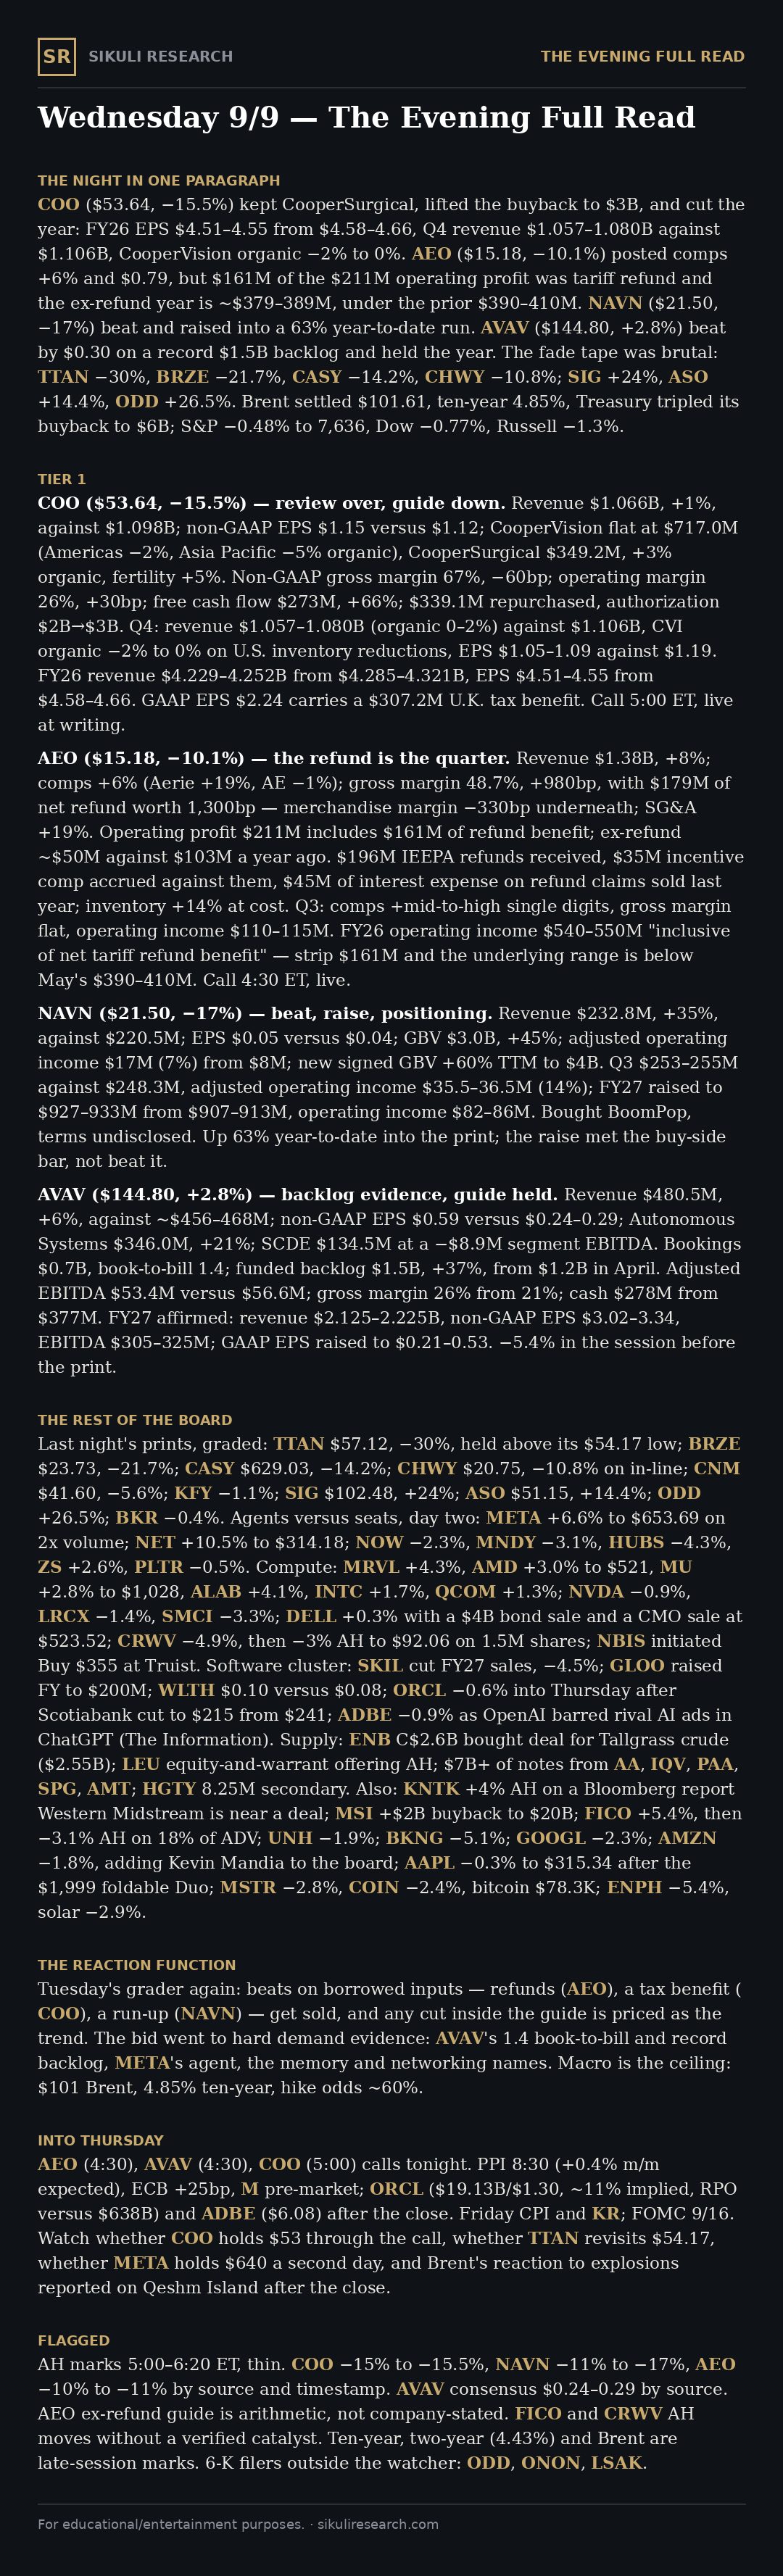
COO -15% AH: review over, buyback to $3B, year cut. AEO -10%: $161M of a $211M quarter was tariff refund. NAVN -17% on a beat-and-raise; AVAV +3%. Fade tape: TTAN -30%, BRZE -22%, CASY -14%. Full read at Sikuli Research (link in bio)
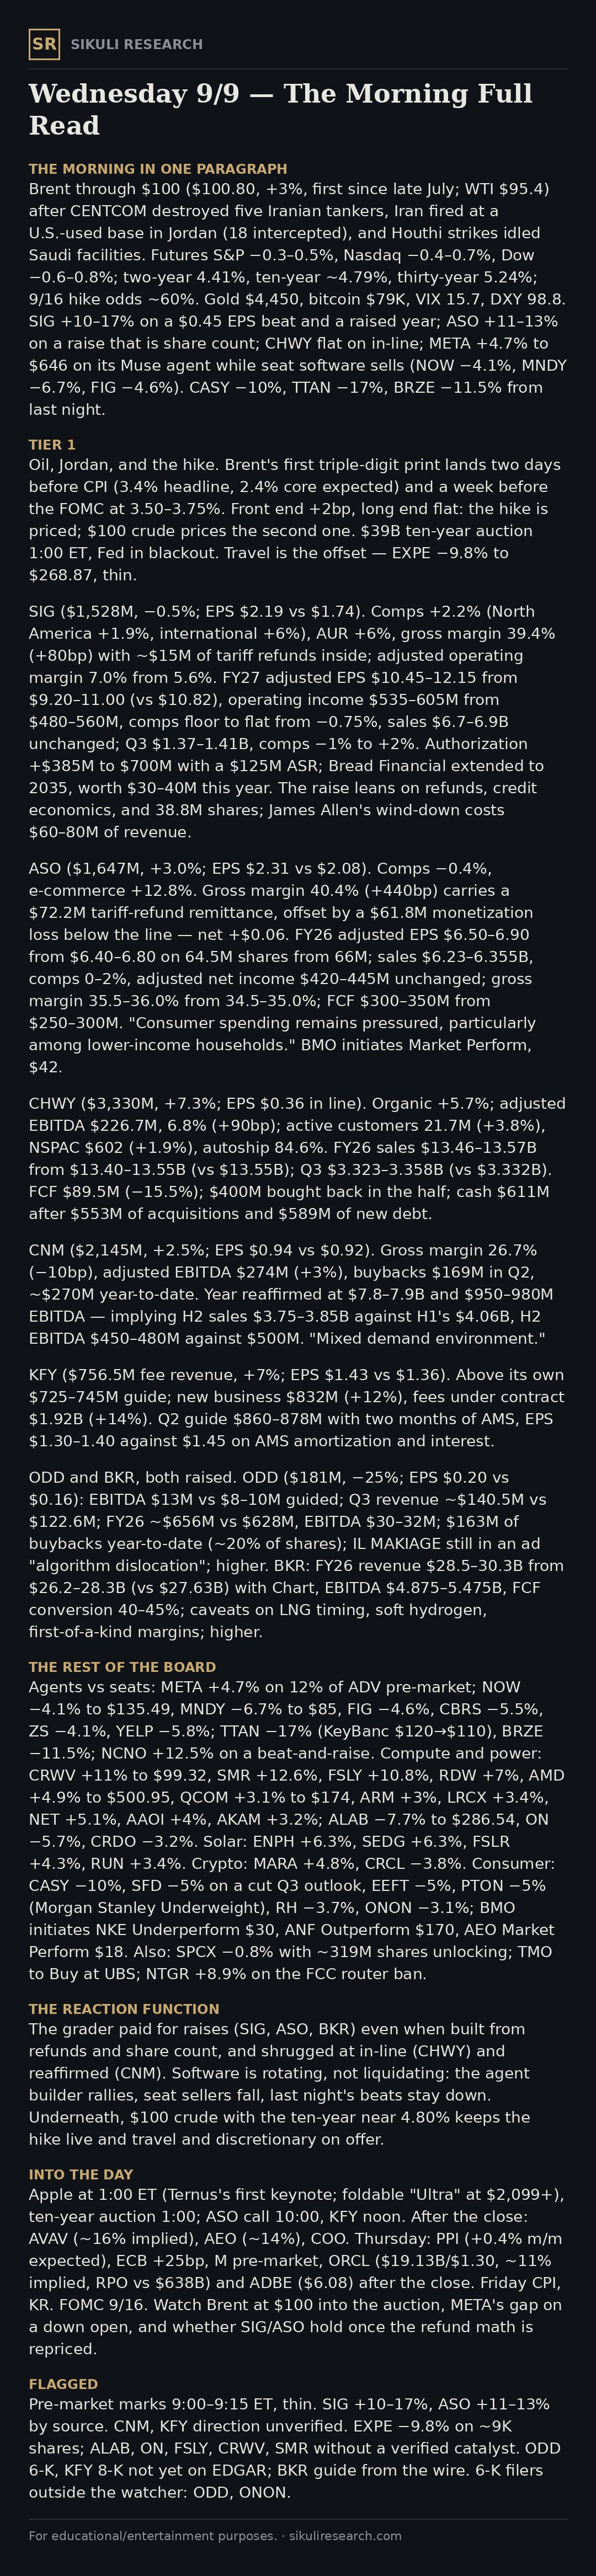
Brent through $100 on U.S.-Iran tanker strikes; 10-year ~4.79%, hike odds ~60%. SIG +10–17% and ASO +11% on tariff-refund raises, CHWY flat; META +4.7% on its agent launch while seat software sells. Full read at Sikuli Research (link in bio)
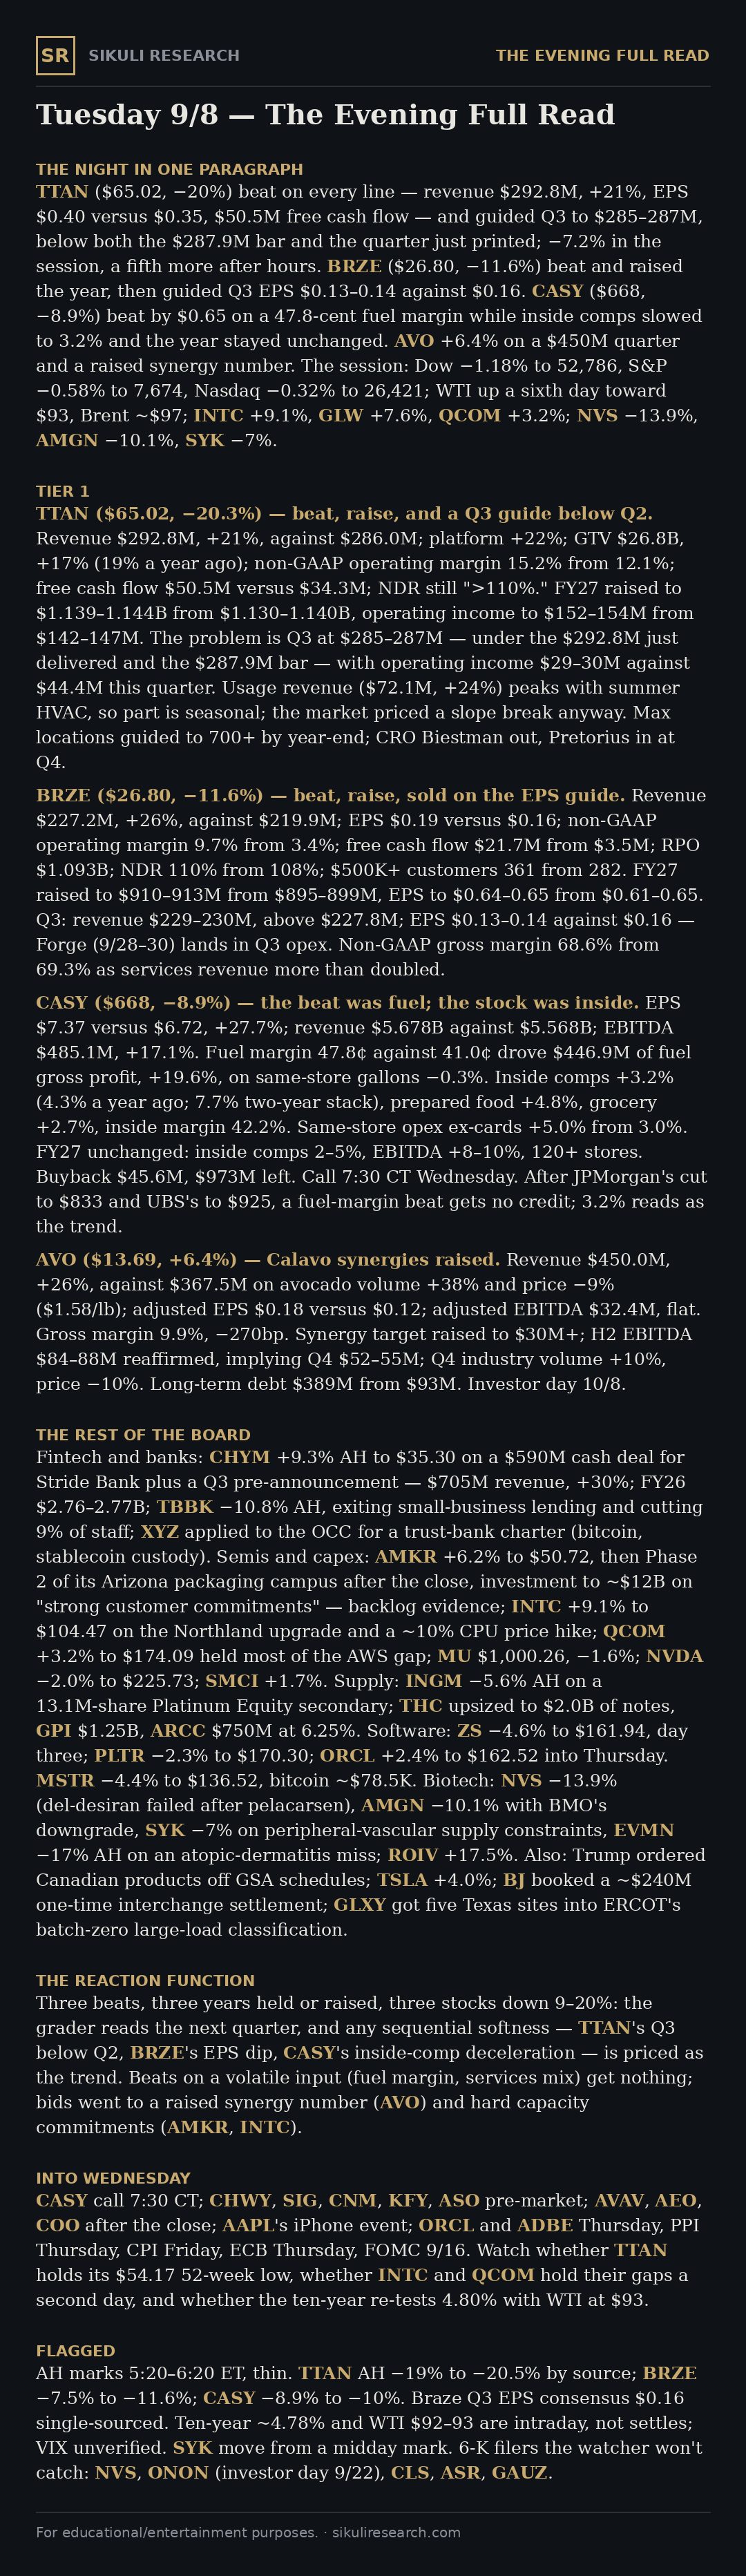
Three beats, three years held or raised, three stocks down 9-20%: TTAN -20% AH on a Q3 guide below Q2, BRZE -12% on the EPS guide, CASY -9% on a fuel-margin beat. The grader reads the next quarter. Full read at Sikuli Research (link in bio)
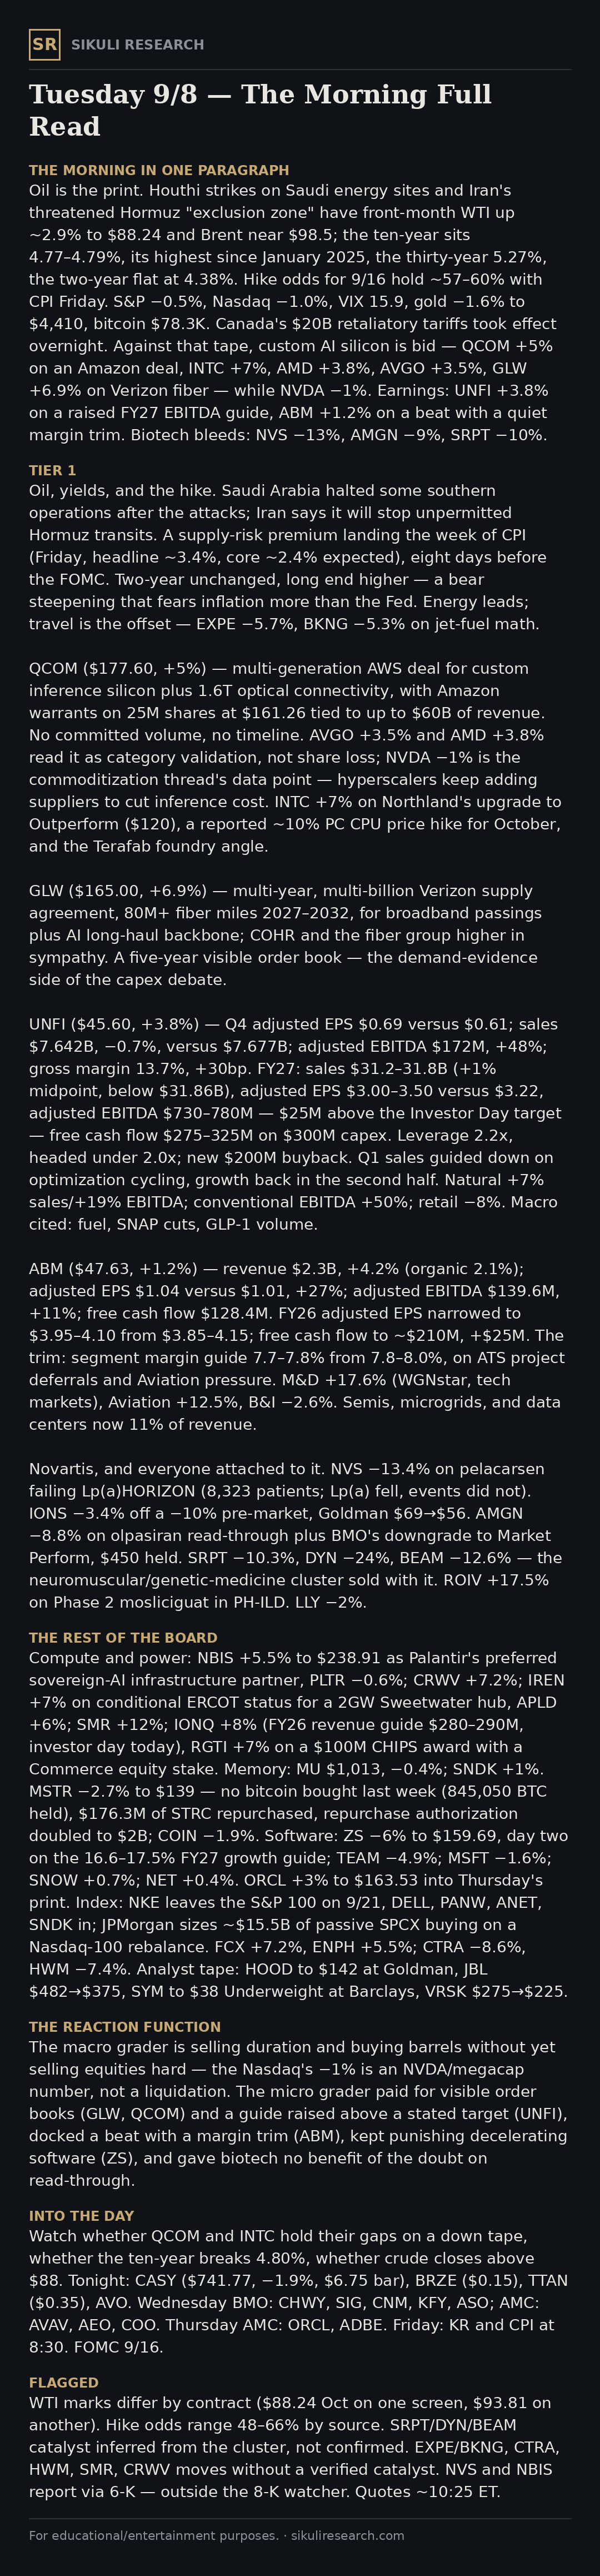
Oil near $90 on Saudi strikes; 10-year 4.79%, highest since Jan 2025. QCOM +5% on an Amazon custom-silicon deal, GLW +7% on Verizon fiber, UNFI raises FY27; NVS/AMGN/SRPT sold on the Lp(a) miss. Full read at Sikuli Research (link in bio)
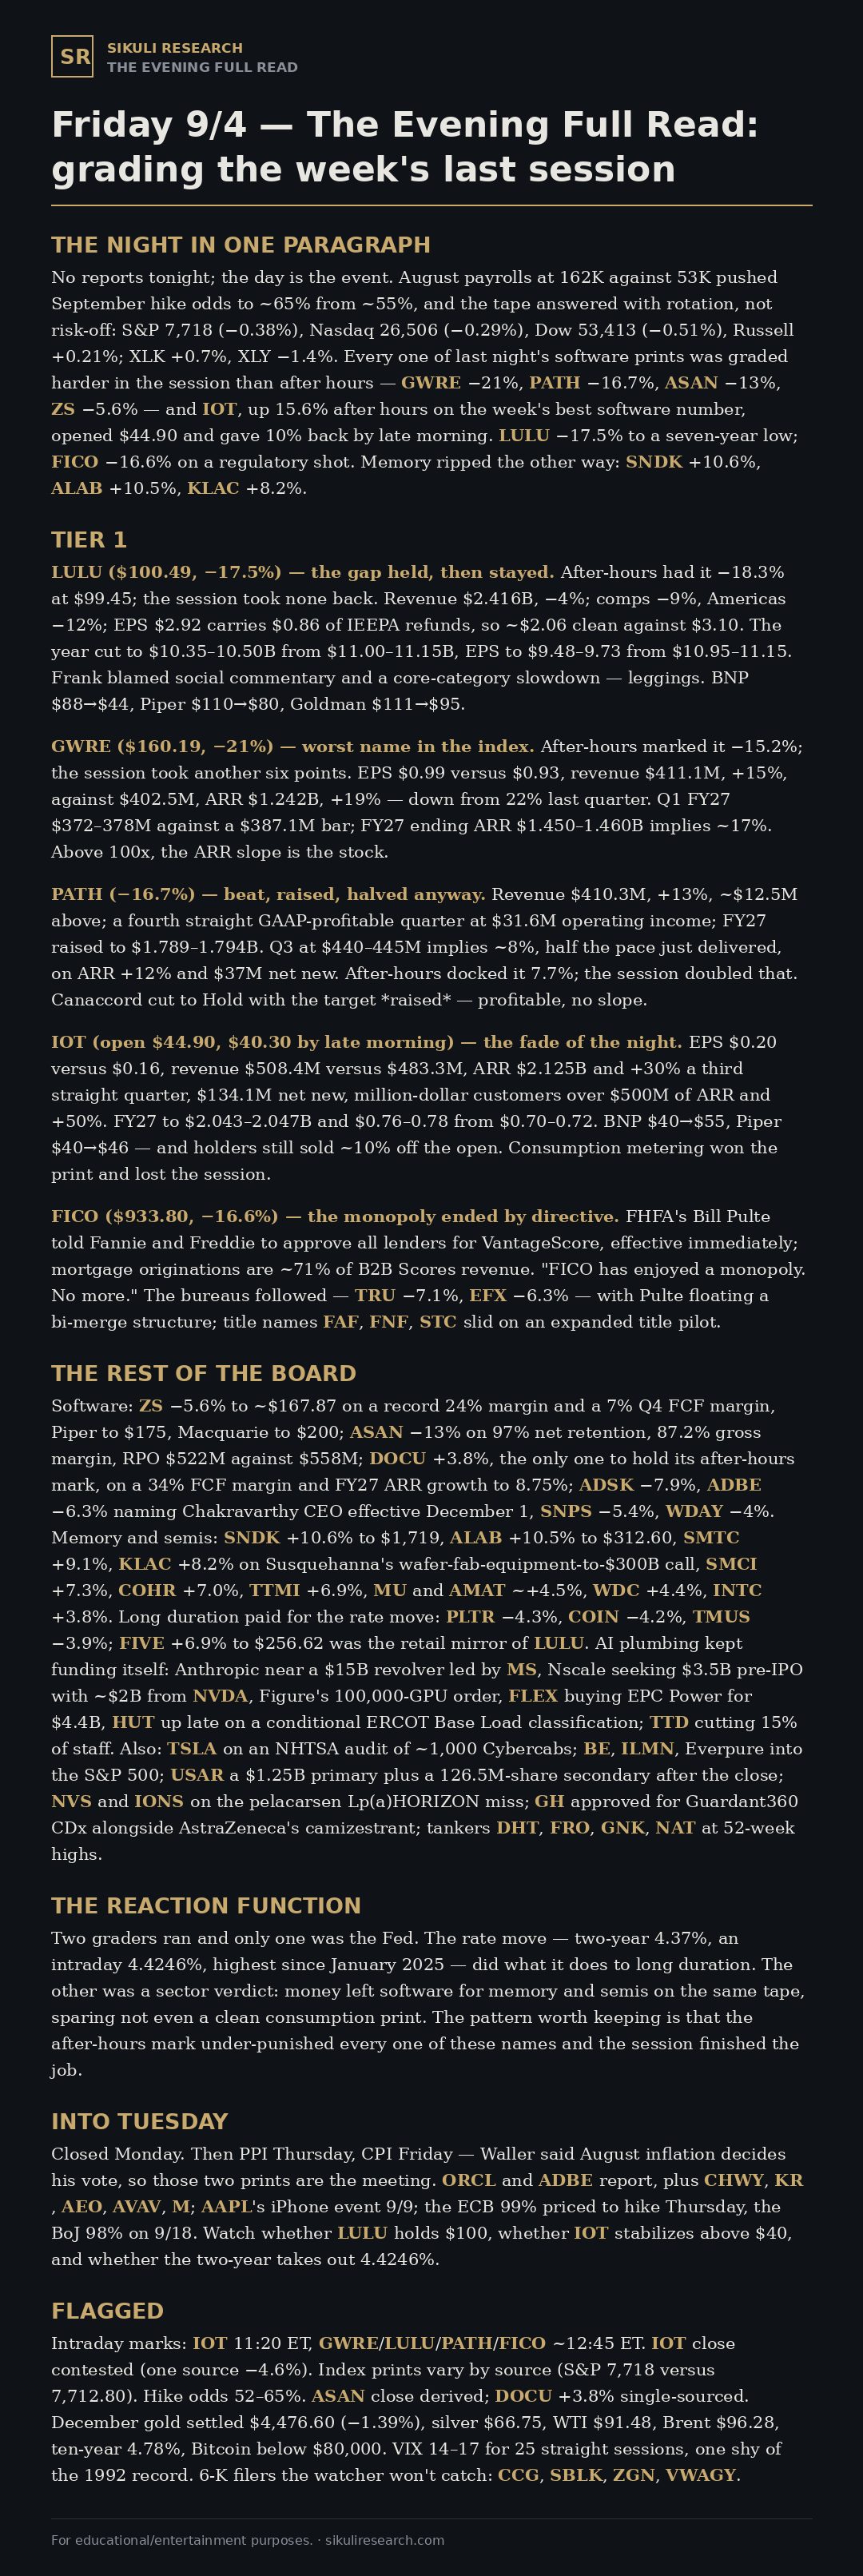
Payrolls at 162K took Sept hike odds to ~65%. The tape rotated, not sold off: memory bid, software gutted. Last night's prints were graded harder in the session than after hours: GWRE -21%, PATH -16.7%. Full read at Sikuli Research (link in bio)
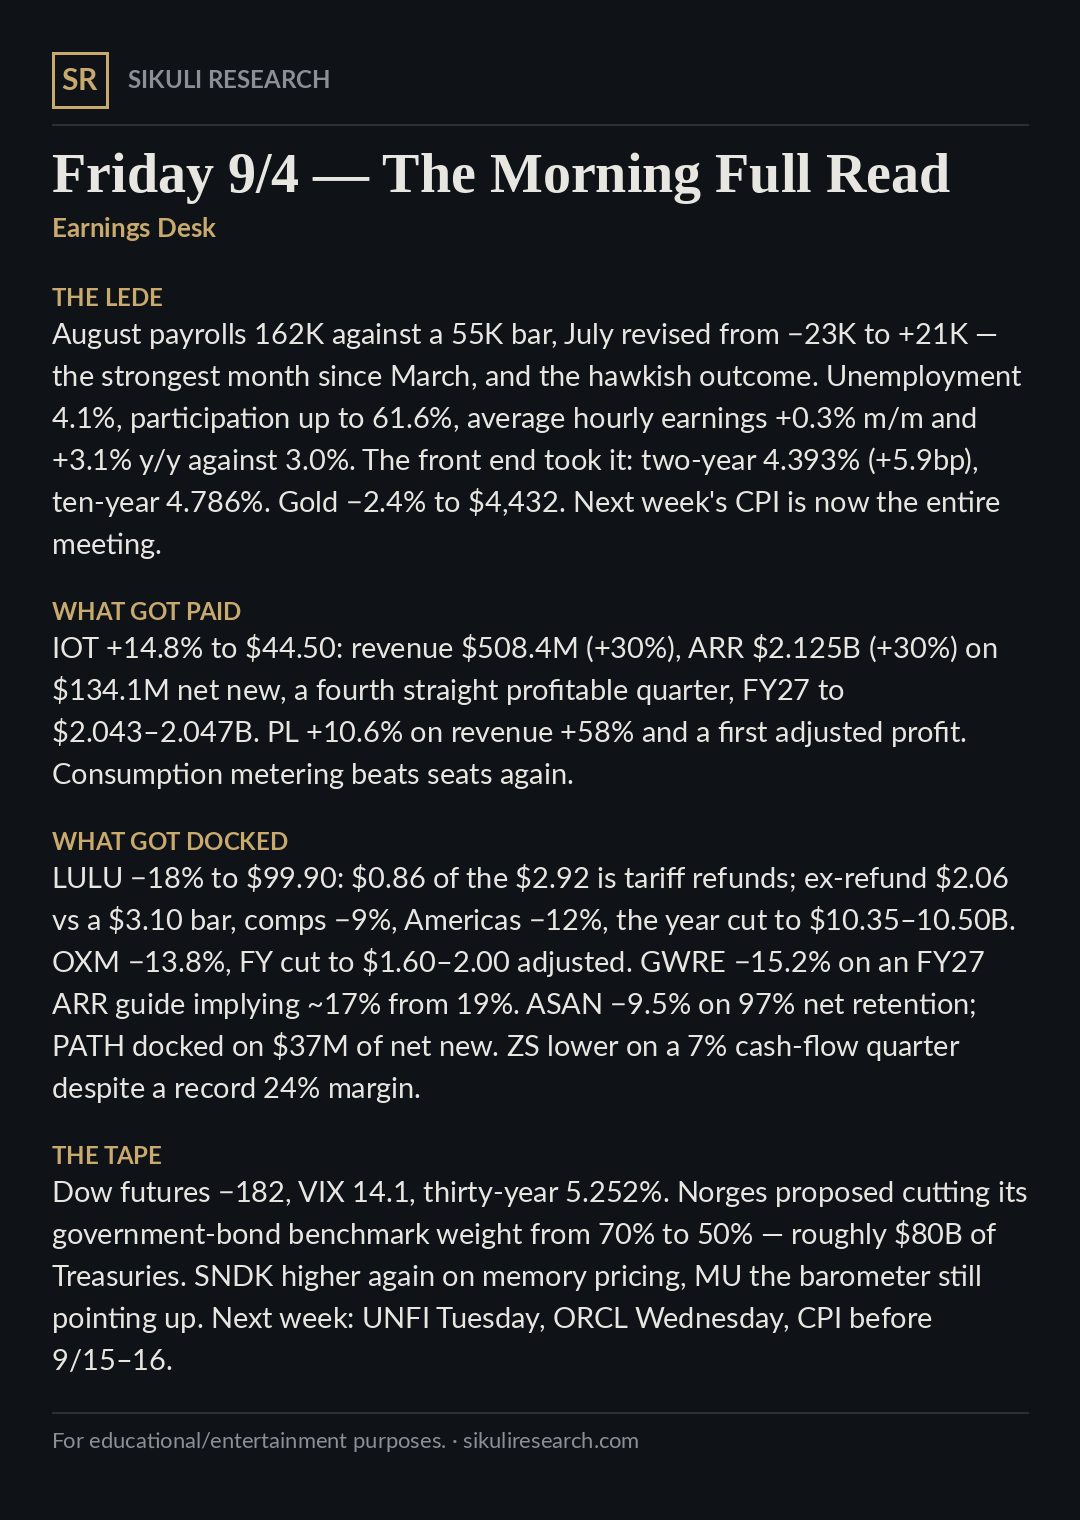
August payrolls 162K vs a 55K bar; the front end reprices toward a hike and gold sheds 2.4%. IOT +15% on consumption, LULU −18% on a refund-flattered quarter. Full read at Sikuli Research (link in bio)
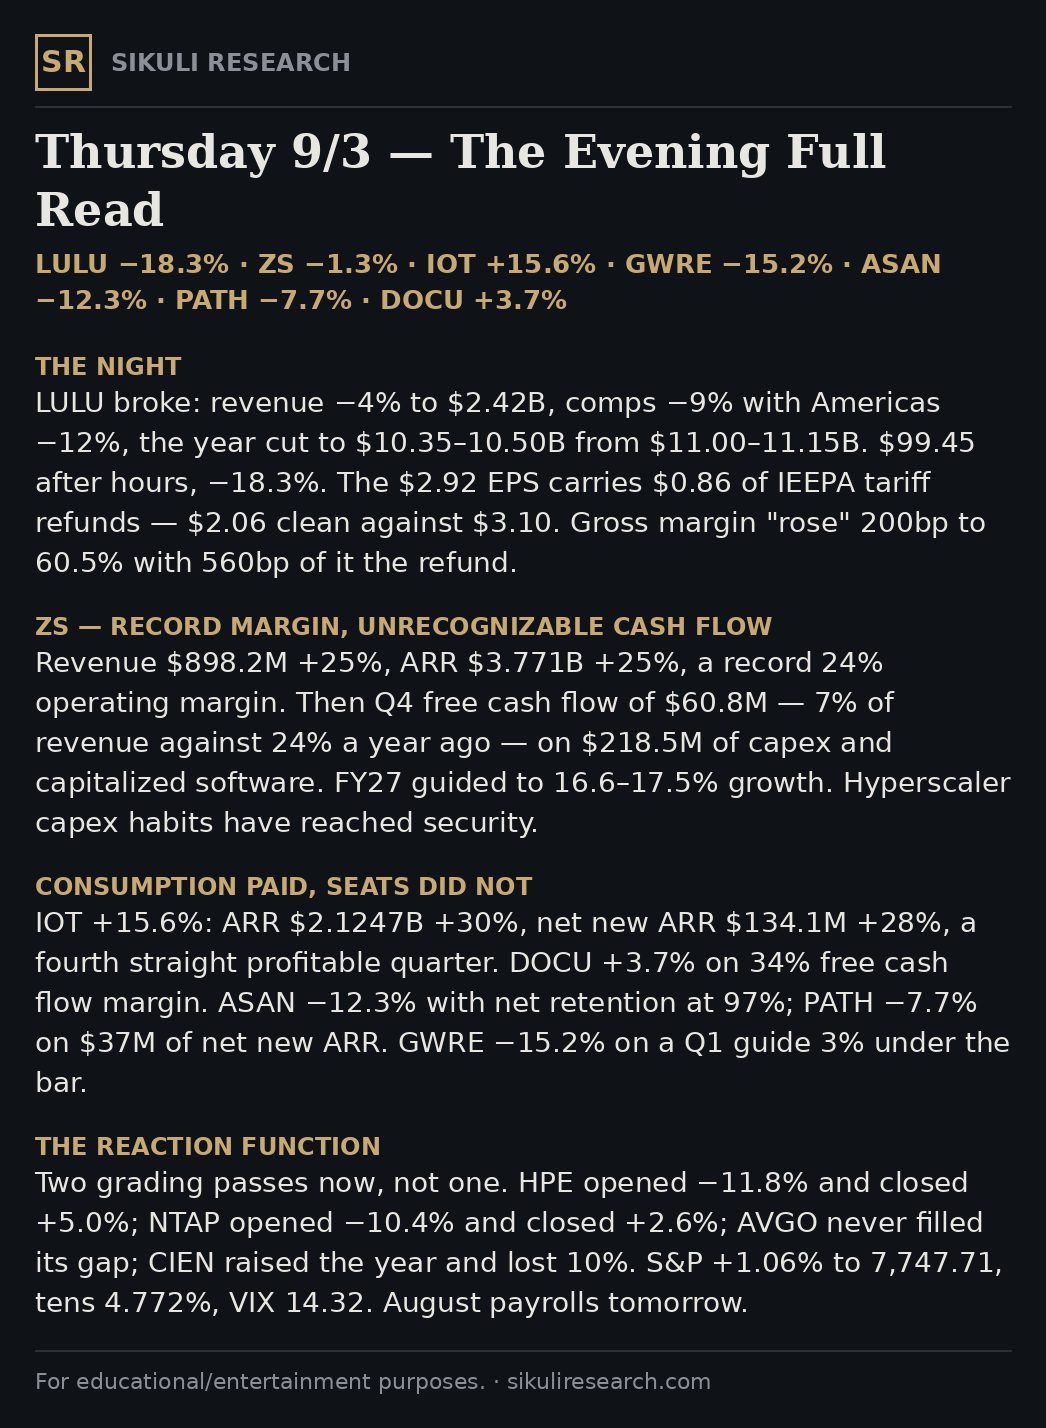
LULU -18% after hours: revenue -4%, comps -9%, the year cut — and $0.86 of the $2.92 EPS is tariff refunds. ZS beat at a record margin on 7% free cash flow. IOT +15.6%; ASAN and PATH sold on seats. Full read at Sikuli Research (link in bio)
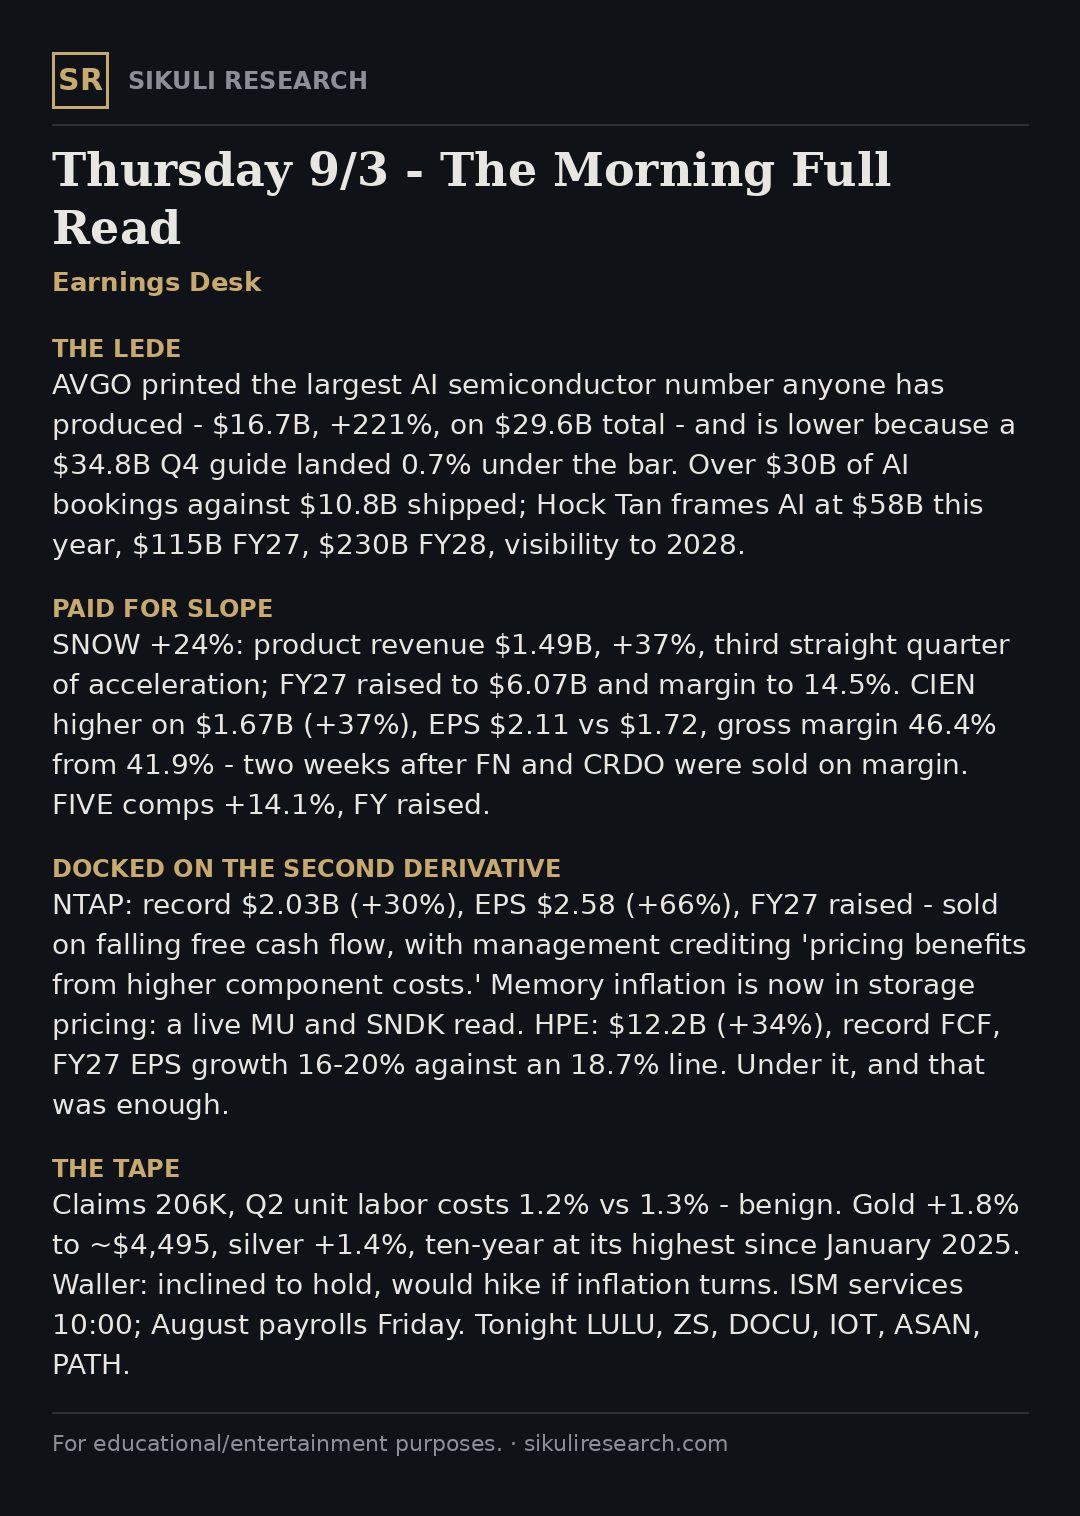
AVGO printed $16.7B of AI semis (+221%) and fell anyway — a $34.8B Q4 guide 0.7% light, against $30B of AI bookings. SNOW +24%; NTAP and HPE beat, raised, and got sold on the second derivative. Full read at Sikuli Research (link in bio)
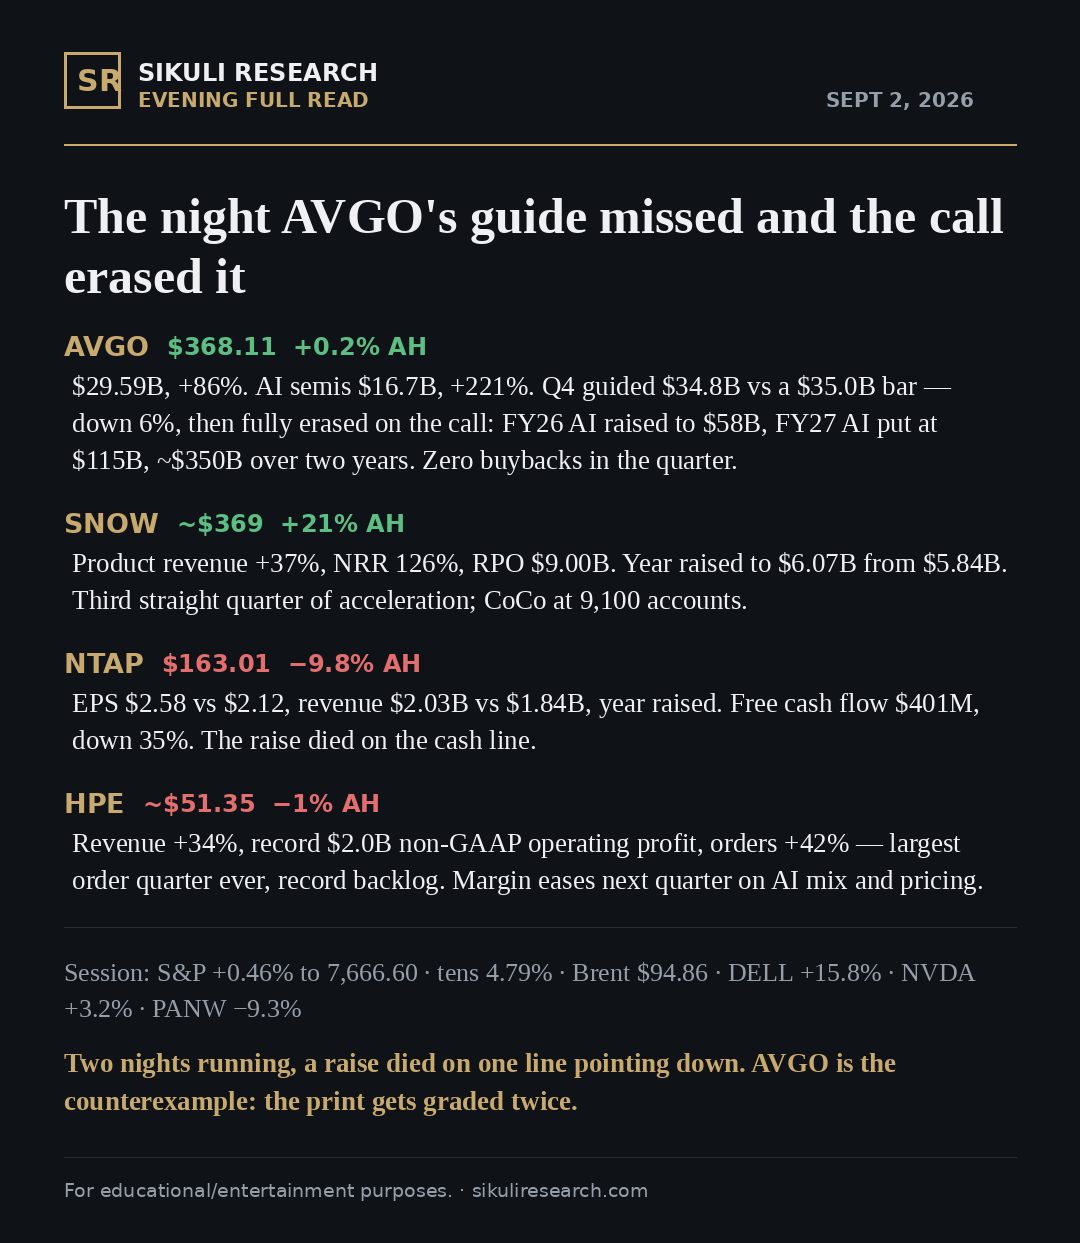
AVGO printed $29.59B (+86%) with AI semis +221%, guided Q4 light, fell 6% — then erased all of it on the call: FY26 AI to $58B, FY27 AI $115B. SNOW +21%. NTAP -9.8% on cash flow. Full read at Sikuli Research (link in bio)
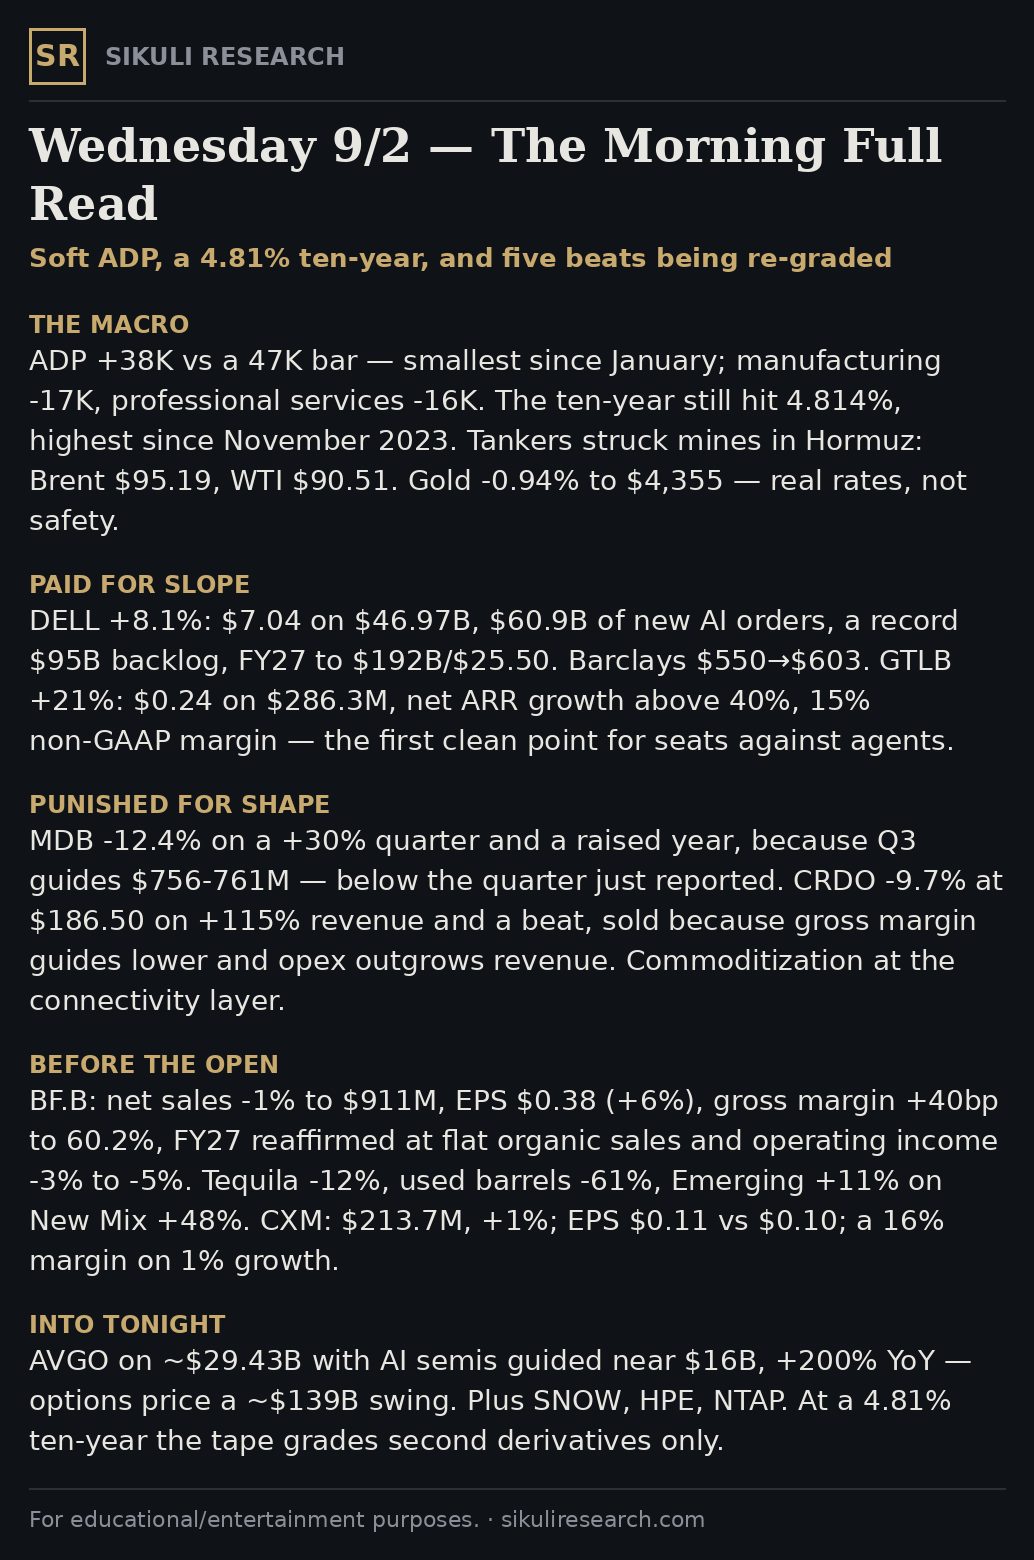
ADP misses at +38K and the ten-year still hits 4.814%. DELL +8% on a $95B AI backlog, GTLB +21%; MDB -12% and CRDO -10% on beats. AVGO tonight. Full read at Sikuli Research (link in bio)
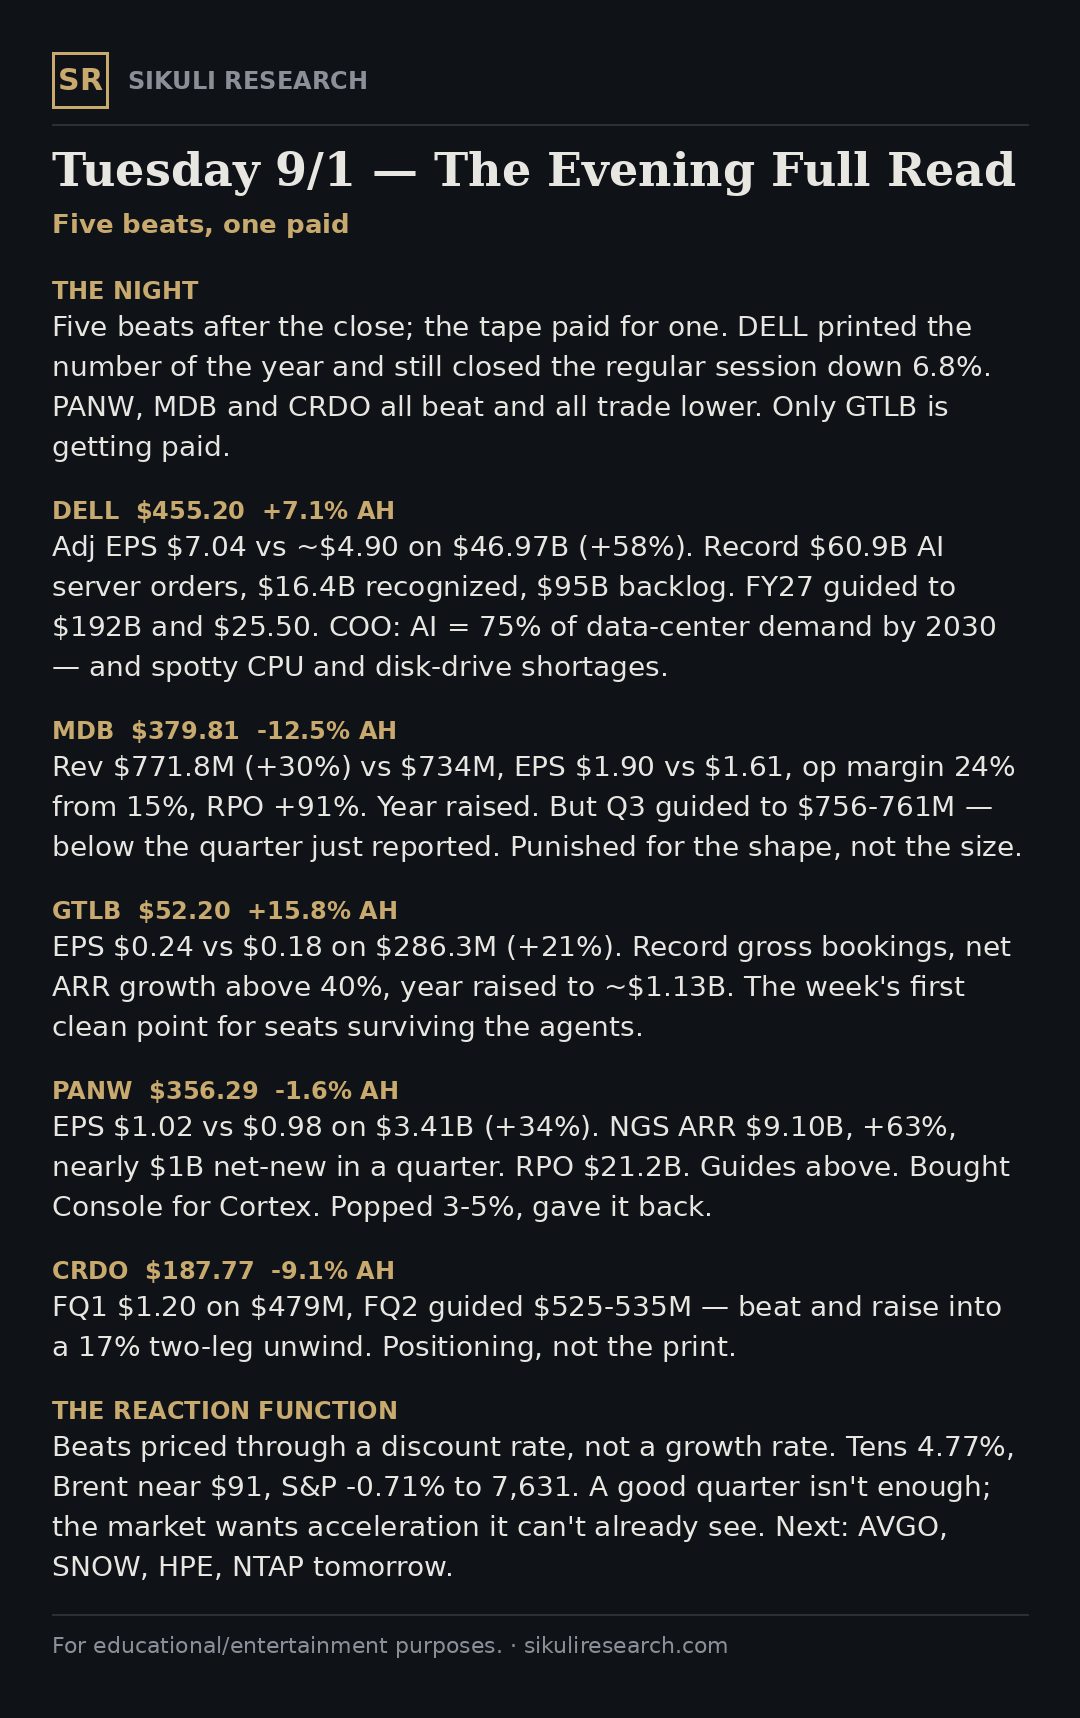
DELL printed the number of the year — $7.04, a record $60.9B in AI server orders, a $95B backlog — and still closed the session down 6.8%. Five beats after the close; only GTLB got paid. Full read at Sikuli Research (link in bio)
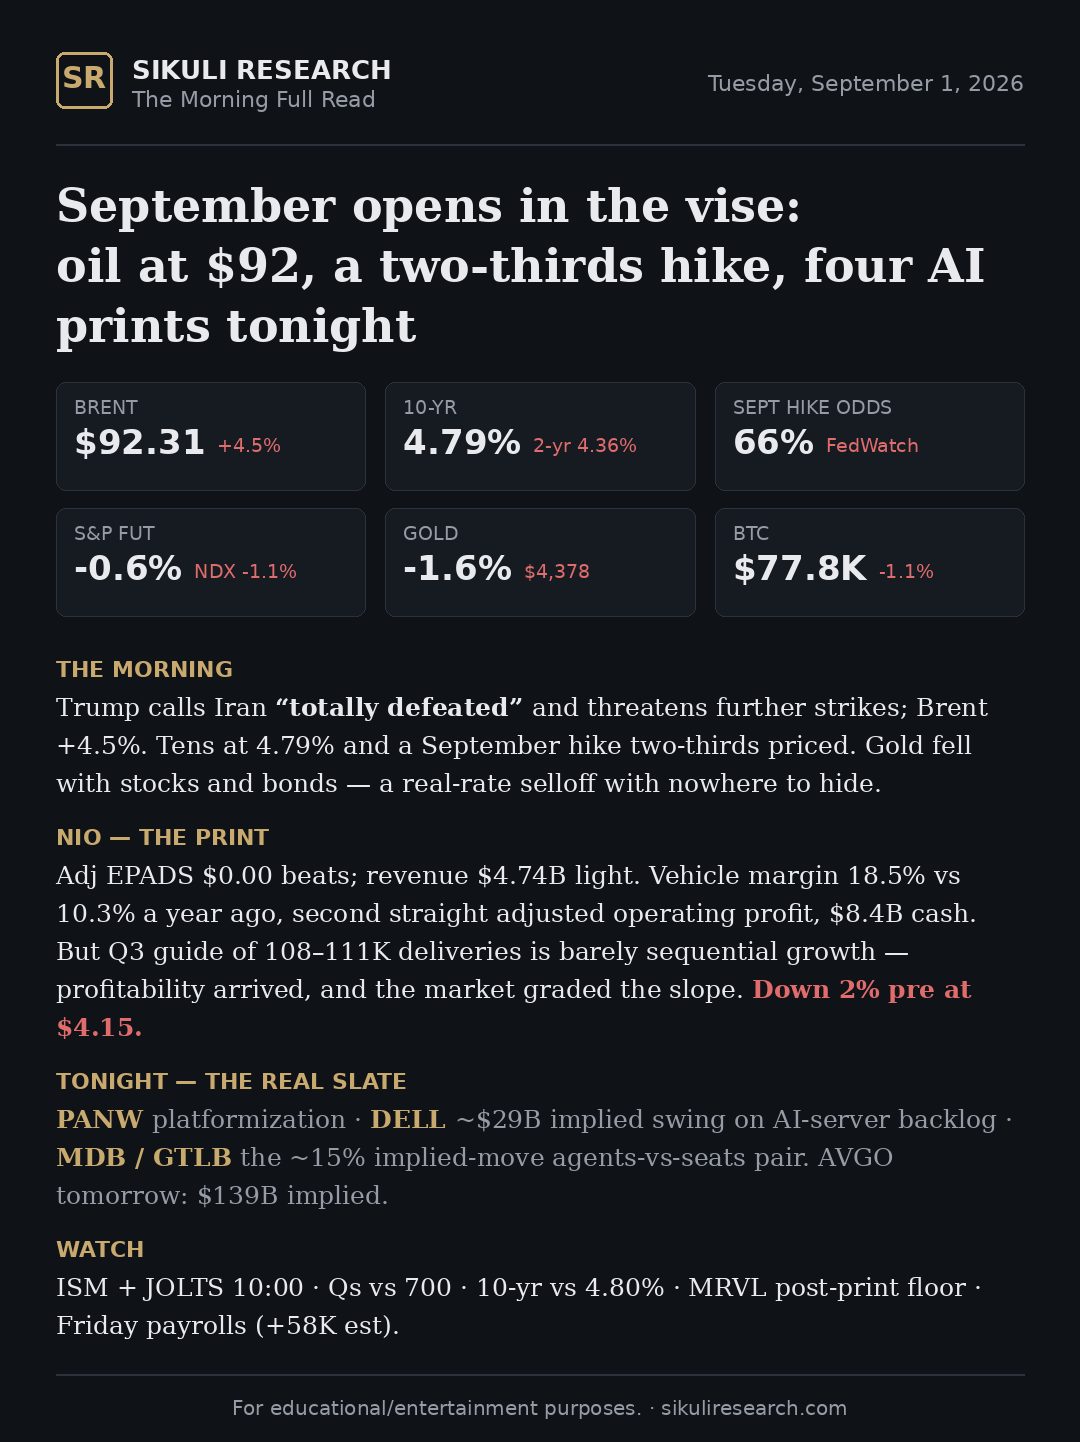
September opens in the vise: Brent at $92, a September hike two-thirds priced, and NIO's first back-to-back profits sold on slope. PANW, DELL, MDB, GTLB report tonight. Full read at Sikuli Research (link in bio)
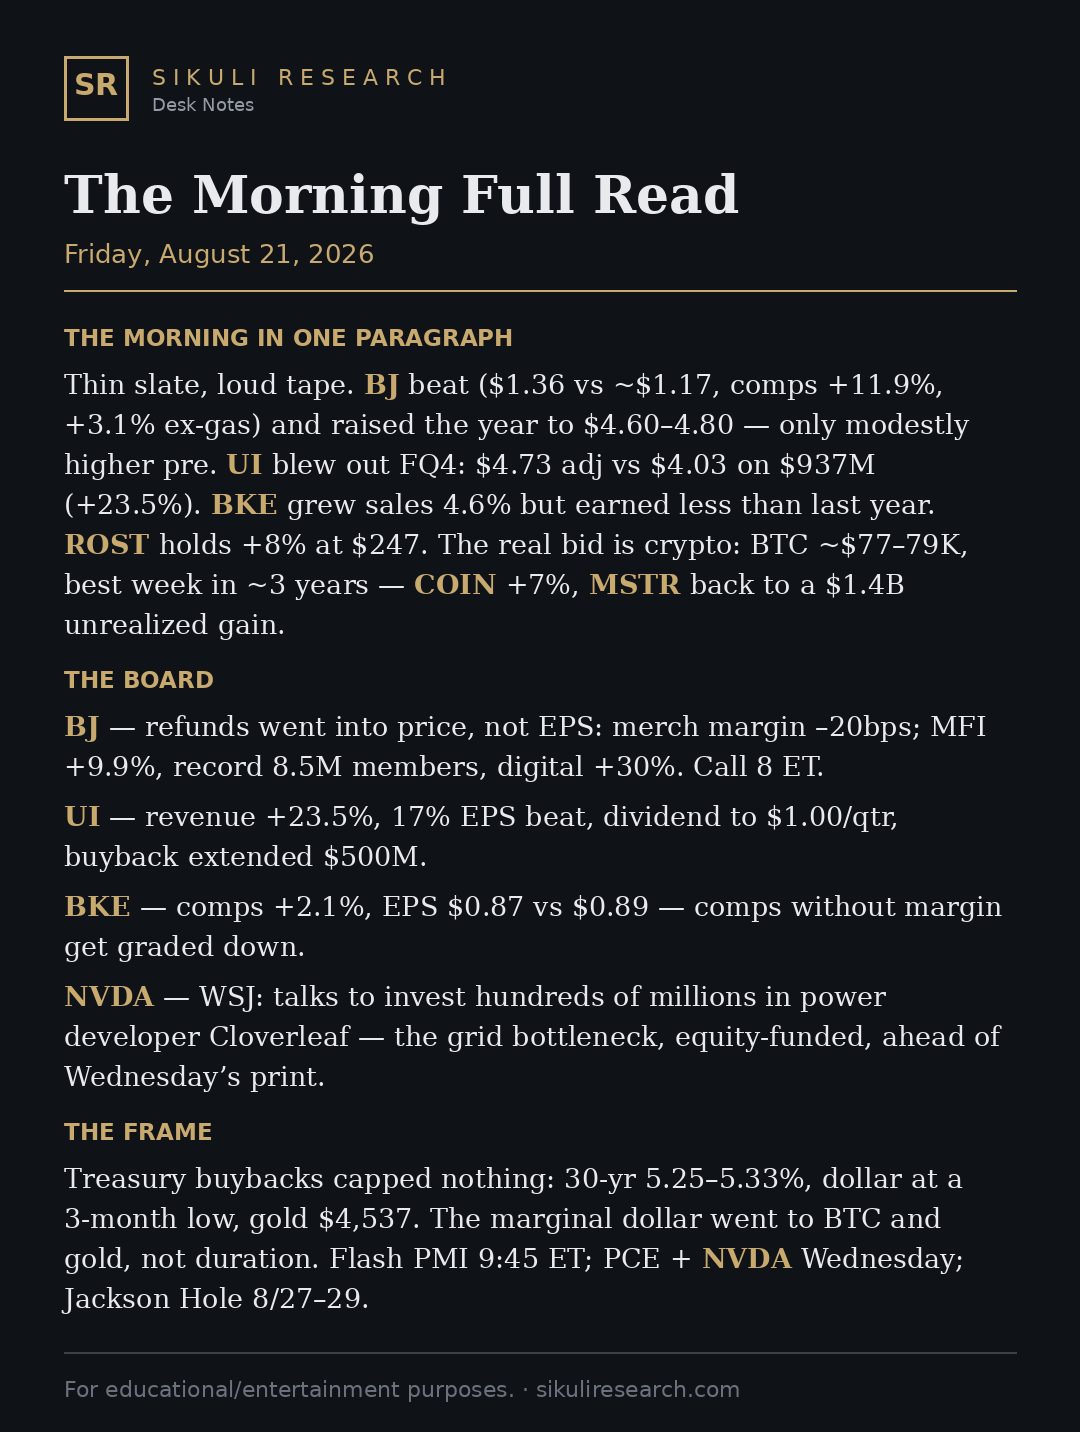
BJ beats and raises but the tape shrugs; UI prints a 17% blowout; the real bid is crypto — BTC's best week in ~3 years while the 30-yr holds above 5.25%. Full read at Sikuli Research (link in bio)
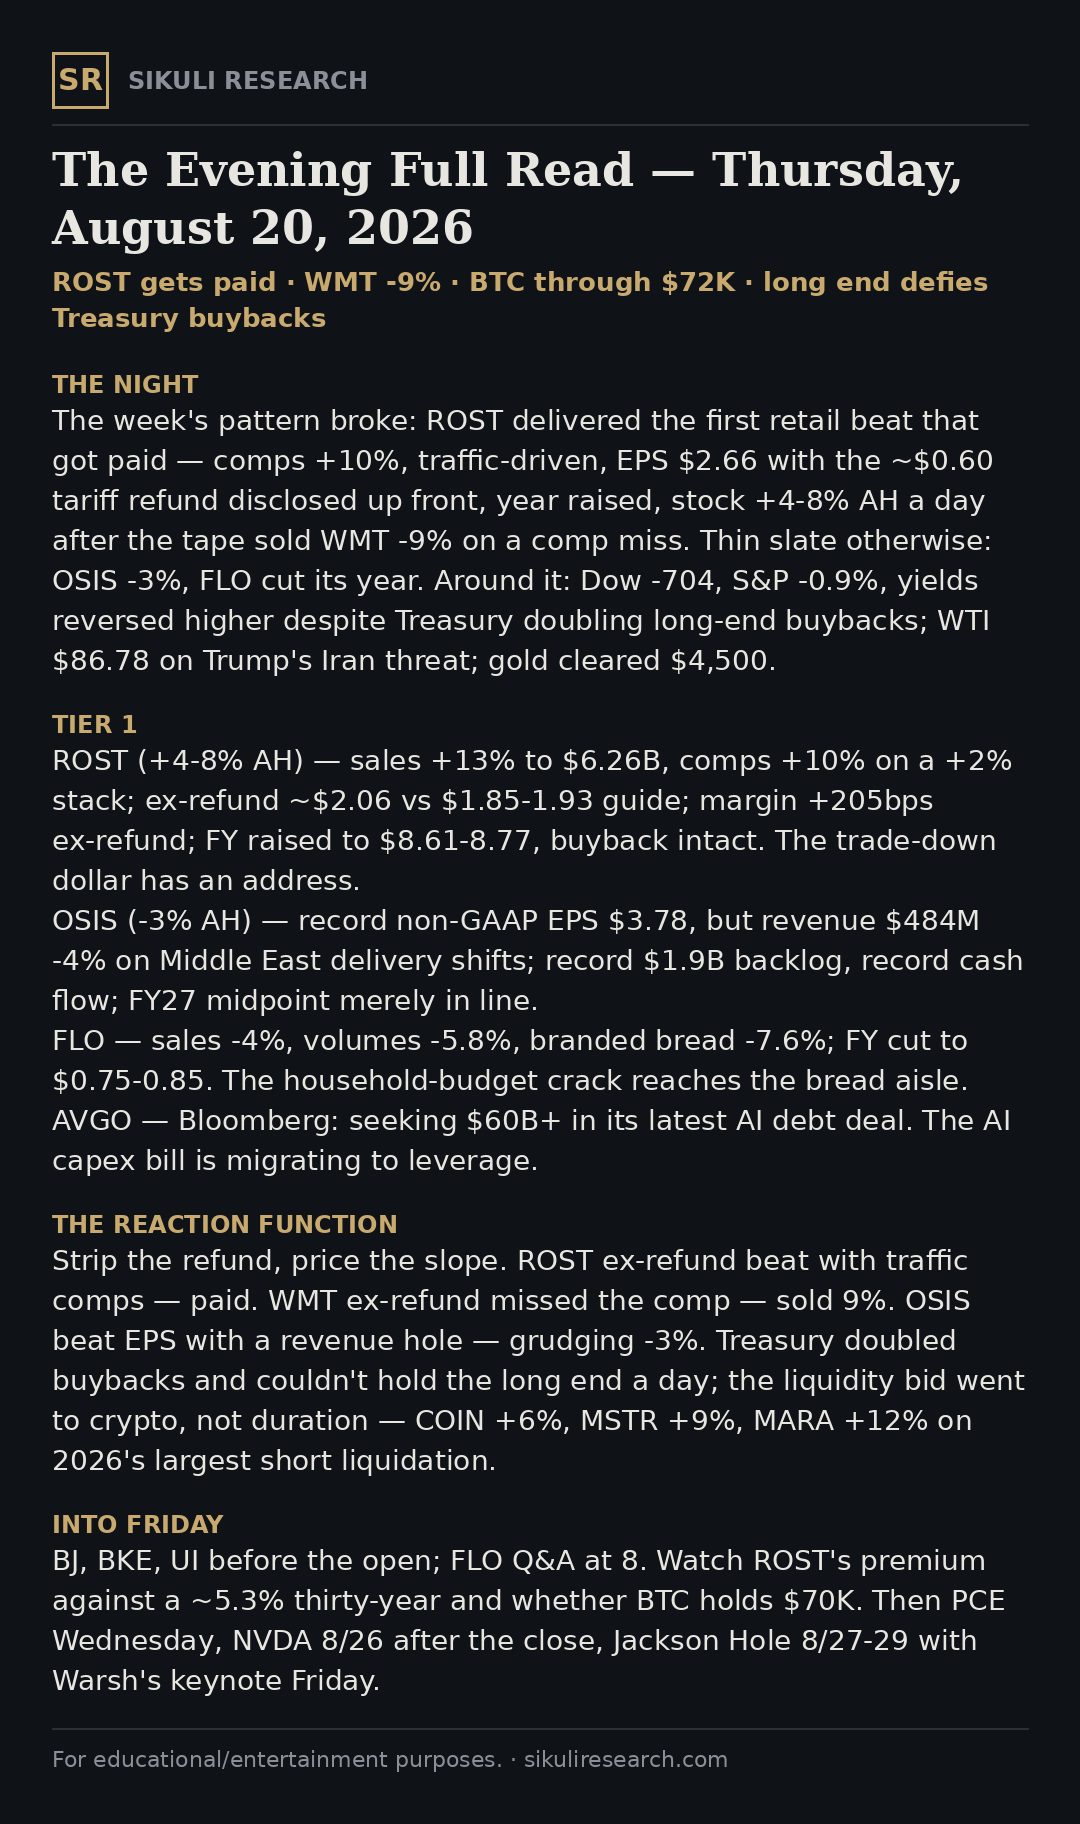
ROST +10% comps — the first retail beat this week that got paid, a day after WMT -9%. BTC through $72K on the year's biggest short squeeze; the long end shrugged off doubled Treasury buybacks. Full read at Sikuli Research (link in bio)
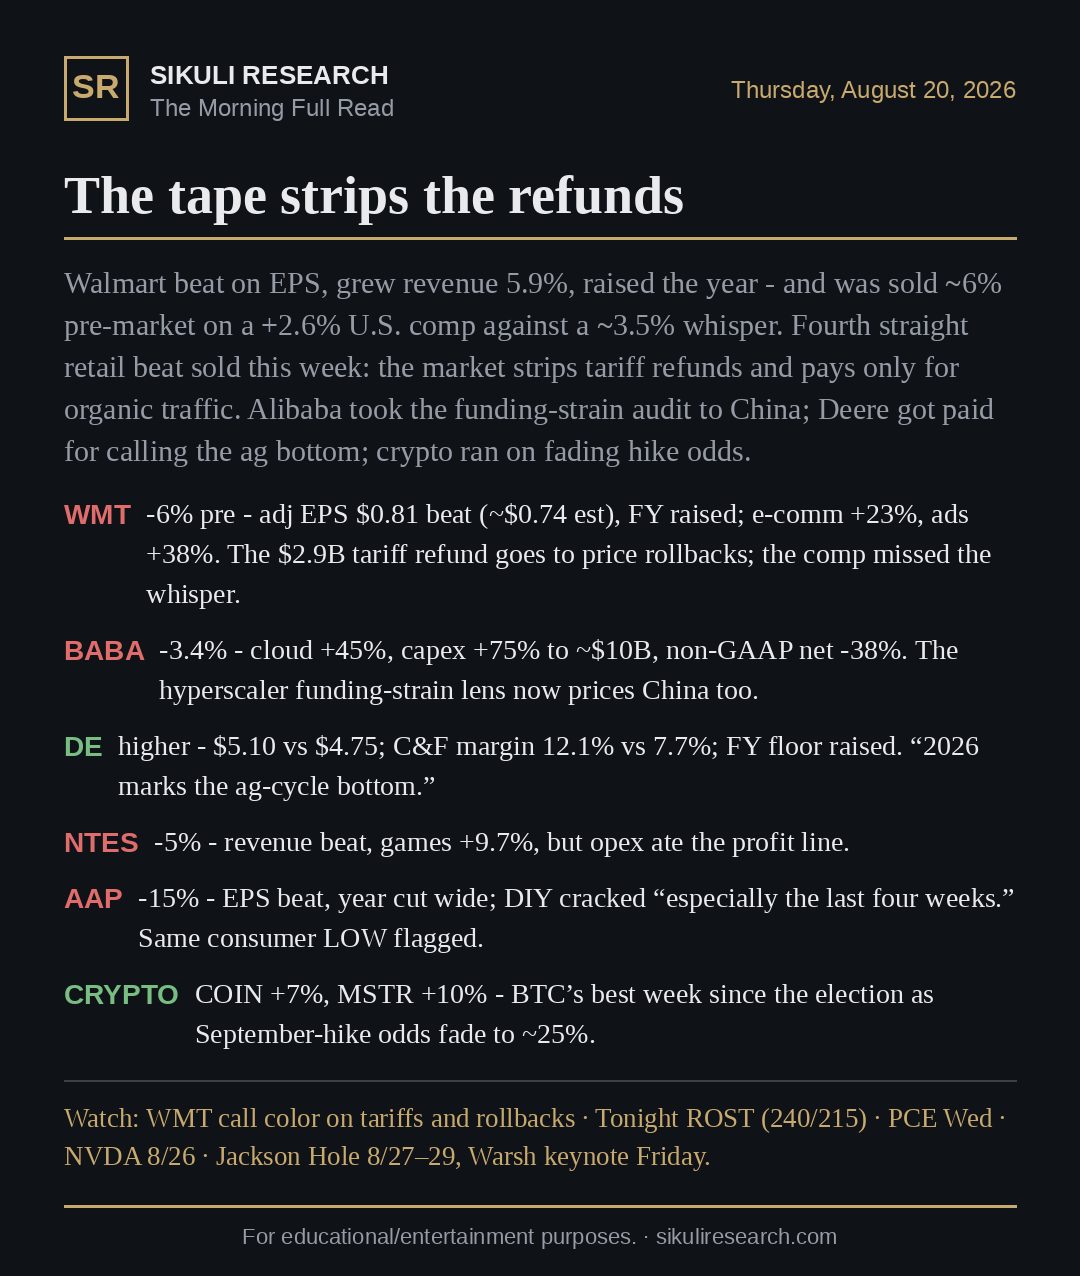
WMT beat, raised the year, got sold — the tape strips tariff refunds and pays only for organic traffic. BABA takes the funding-strain audit to China; DE calls the ag bottom; crypto runs on fading hike odds. Full read at Sikuli Research (link in bio)
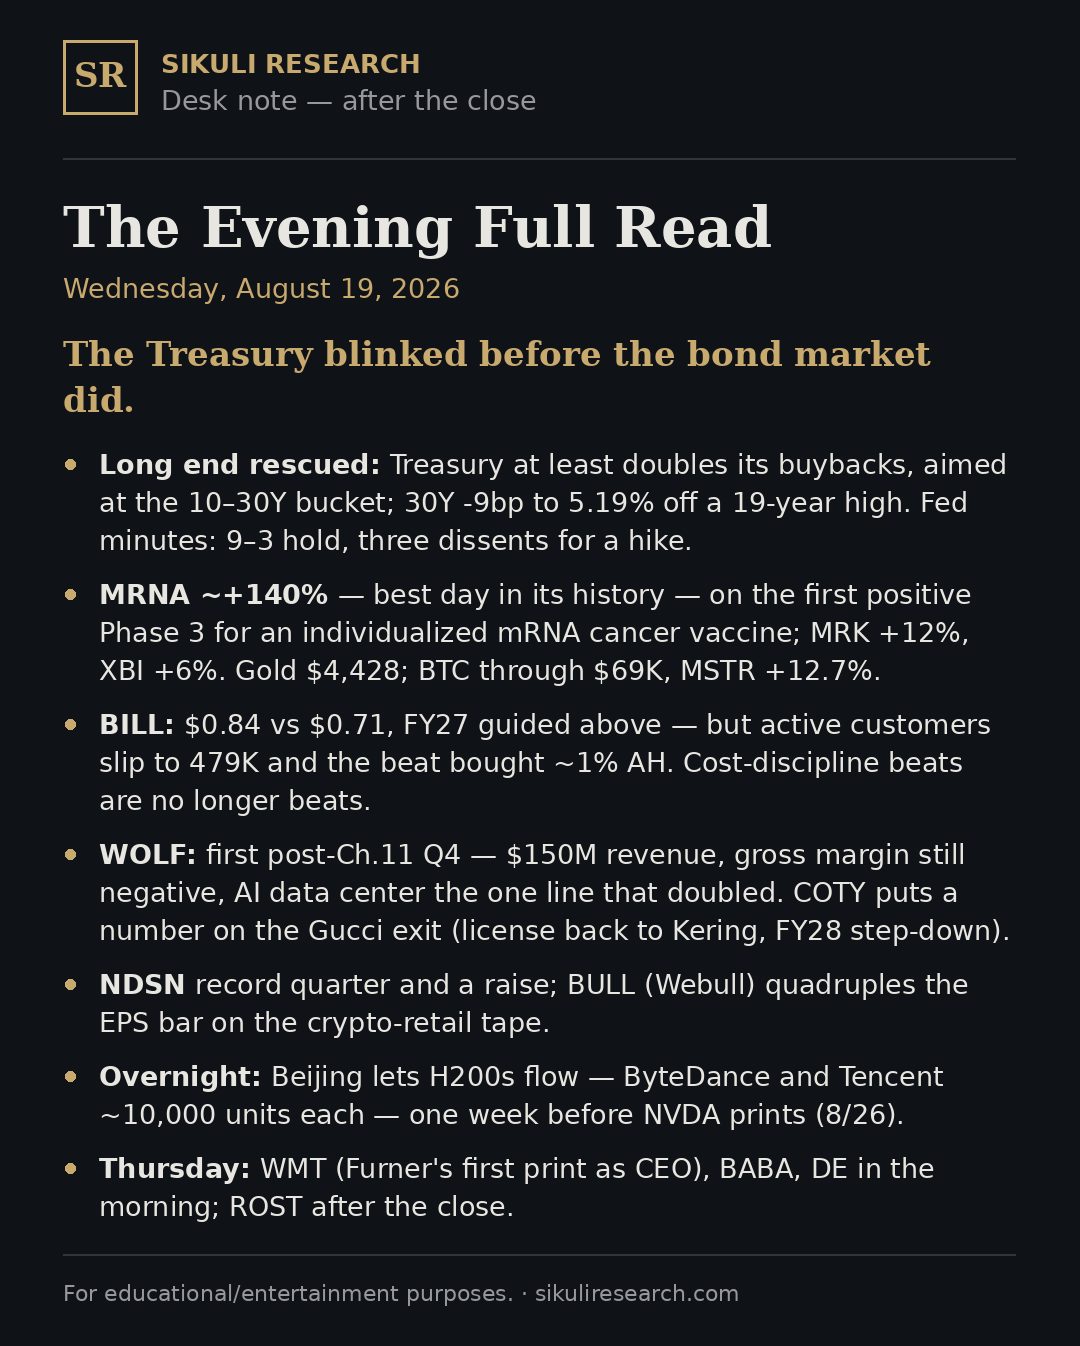
The Treasury blinks first: long-end buybacks doubled, 30Y off a 19-year high. MRNA's best day ever. BILL beats but customers slip. Beijing lets H200s flow a week before NVDA. Full read at Sikuli Research (link in bio)
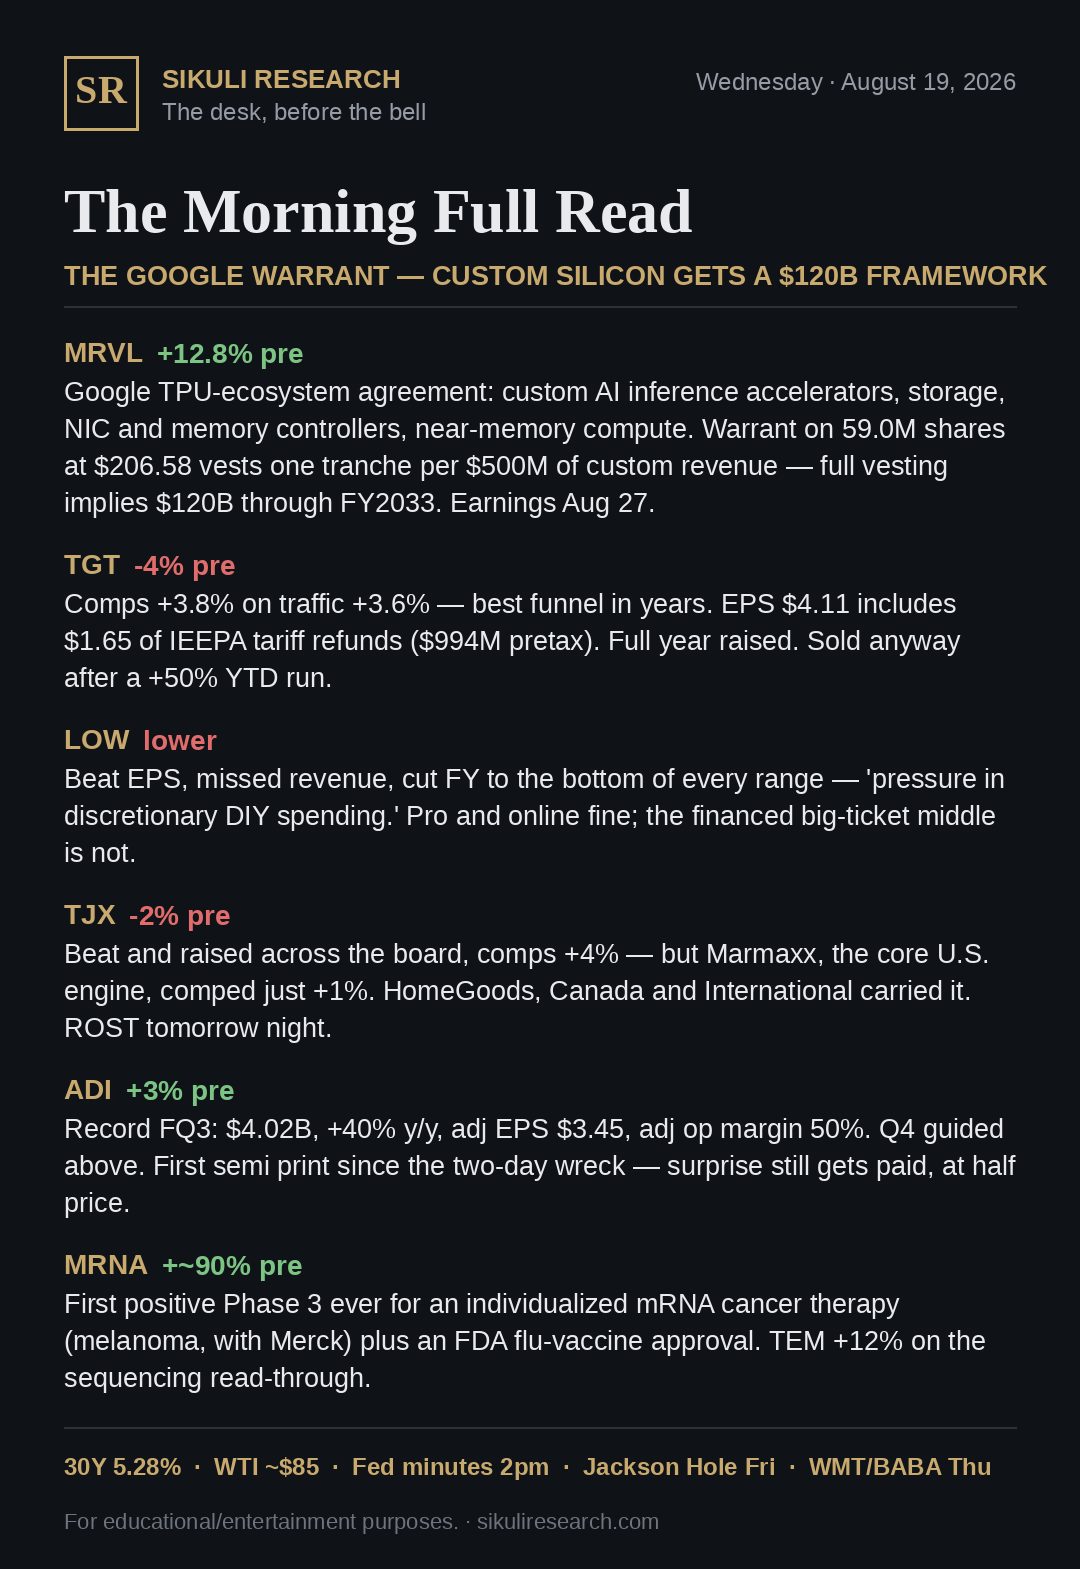
Marvell sells Google a piece of itself: a warrant vesting against $120B of custom silicon through FY33. MRVL +13% pre. TGT and TJX beat, raised — sold. MRNA +90% on the melanoma Phase 3. Full read at Sikuli Research (link in bio)
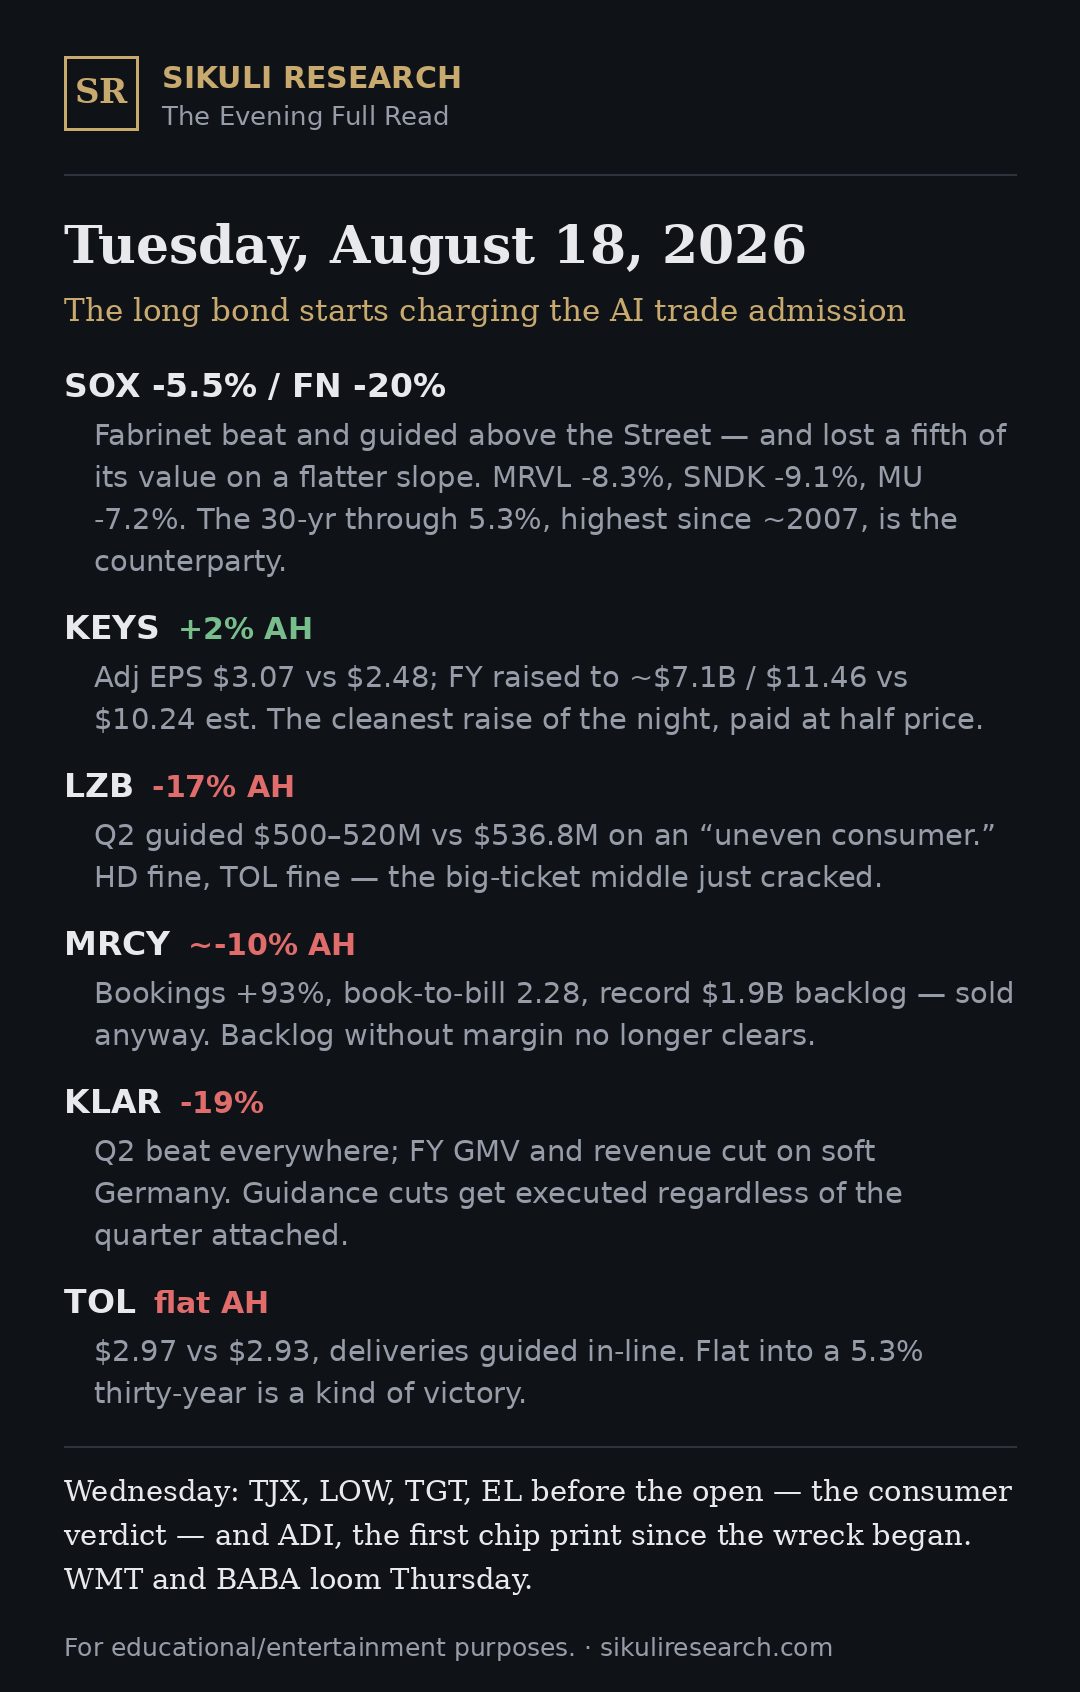
The long bond starts charging the AI trade admission: SOX -5.5%, FN -20% after a beat. KEYS raises FY and gets +2%; LZB -17% cracks the big-ticket consumer; MRCY's record backlog sold anyway. Full read at Sikuli Research (link in bio)
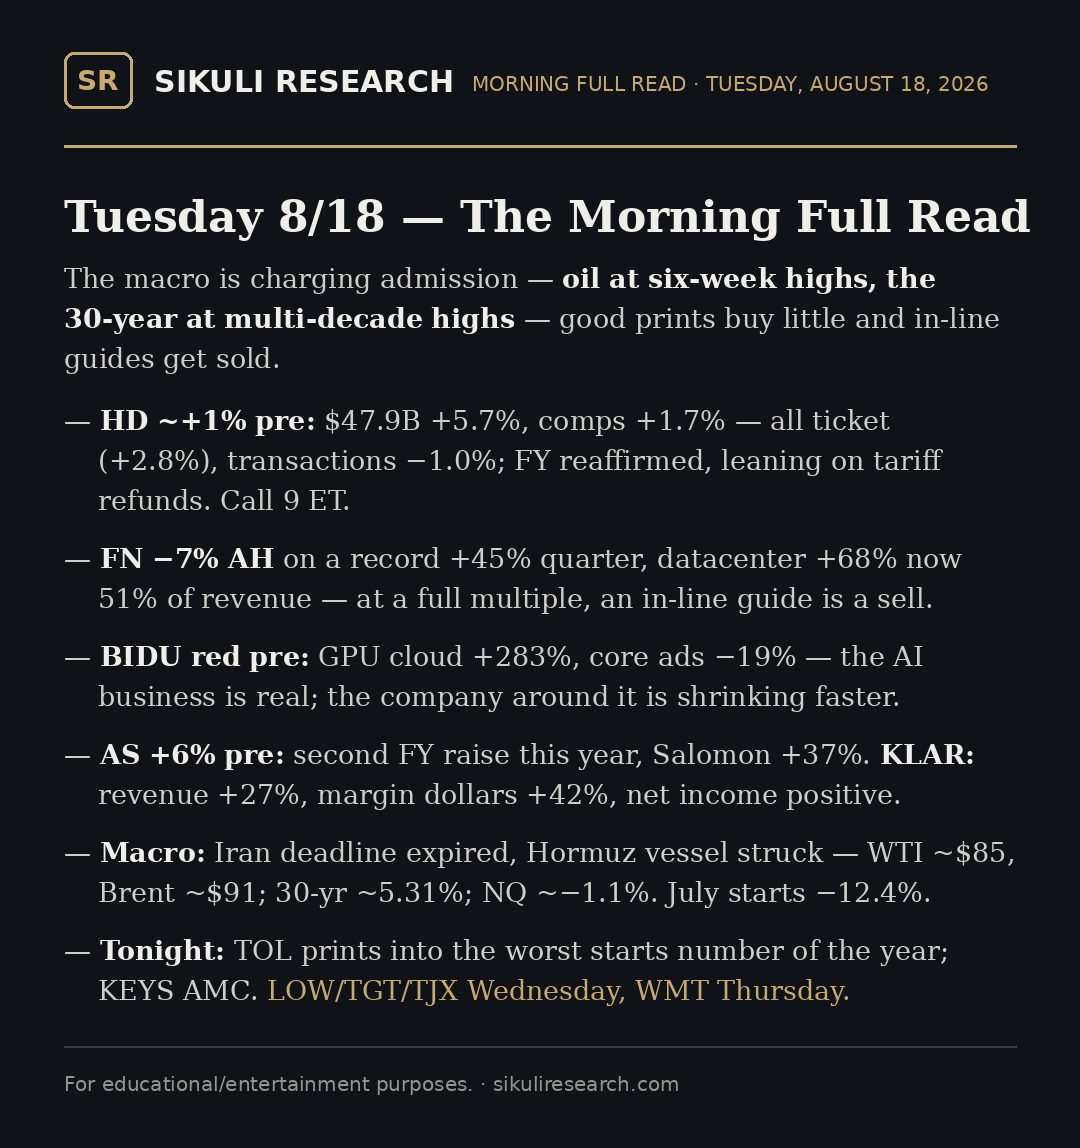
Oil at six-week highs, the 30-year at multi-decade highs — HD beats and reaffirms, Fabrinet's record +45% quarter gets sold anyway. Good news keeps getting cheaper. Full read at Sikuli Research (link in bio)
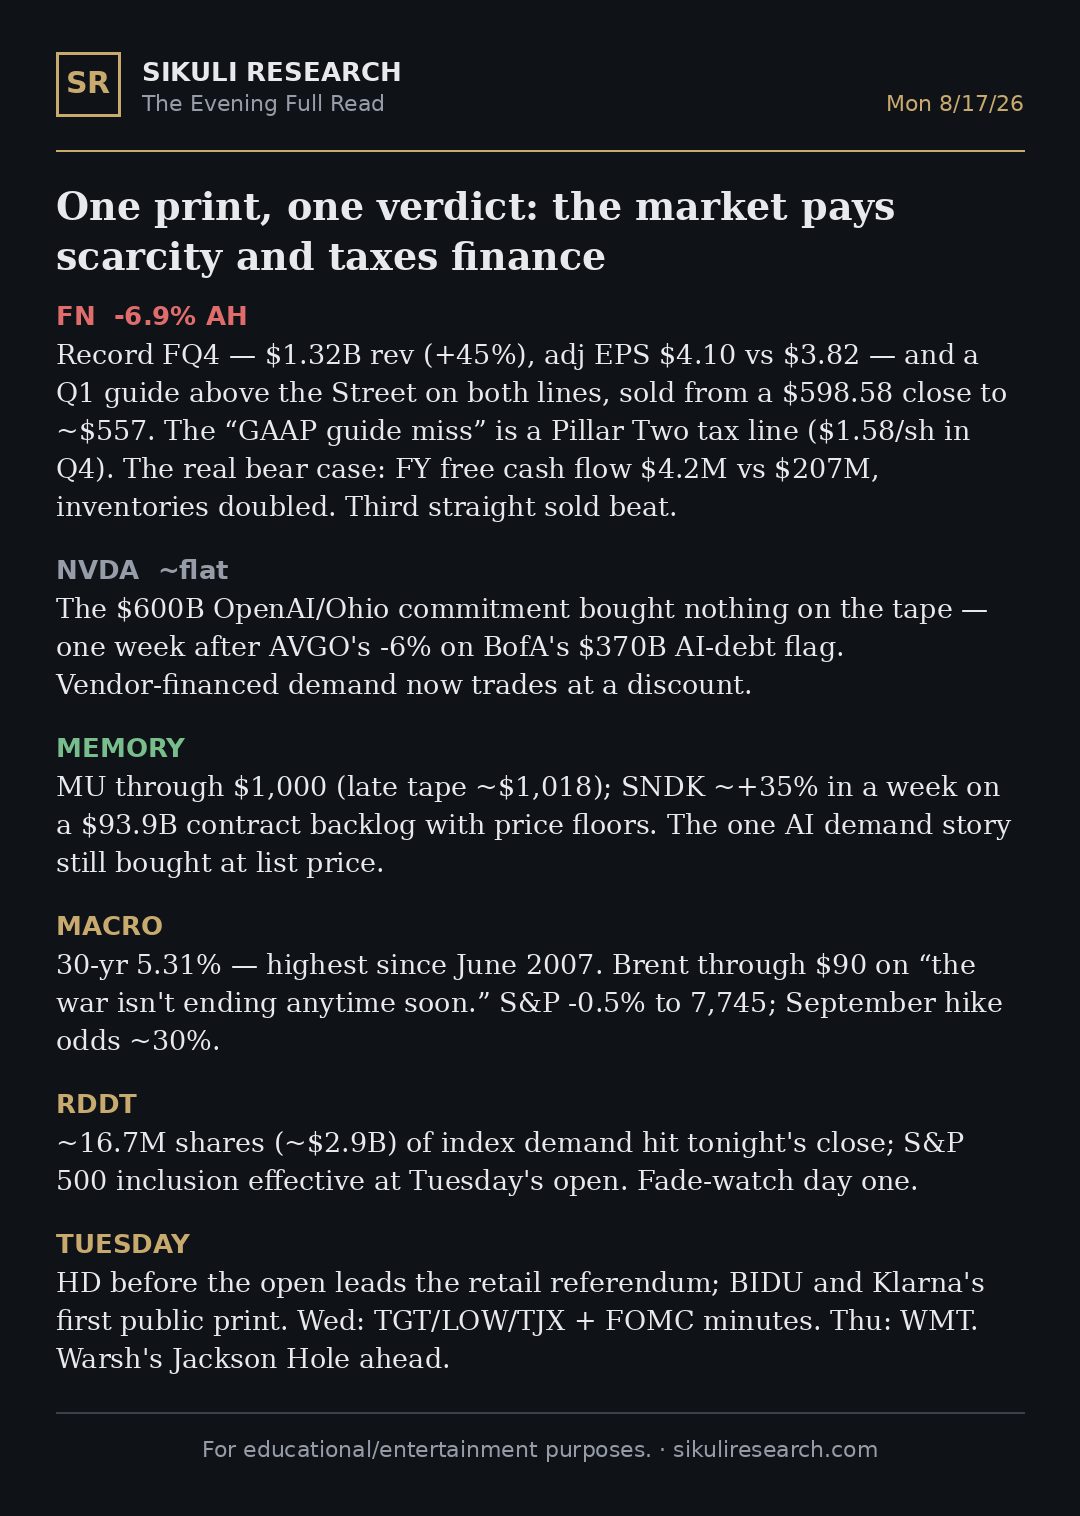
Fabrinet's record quarter sold -7% after hours on a tax-line optical illusion, while Nvidia's $600B OpenAI commitment closed flat. The tape pays memory scarcity and taxes financed demand. Full read at Sikuli Research (link in bio)
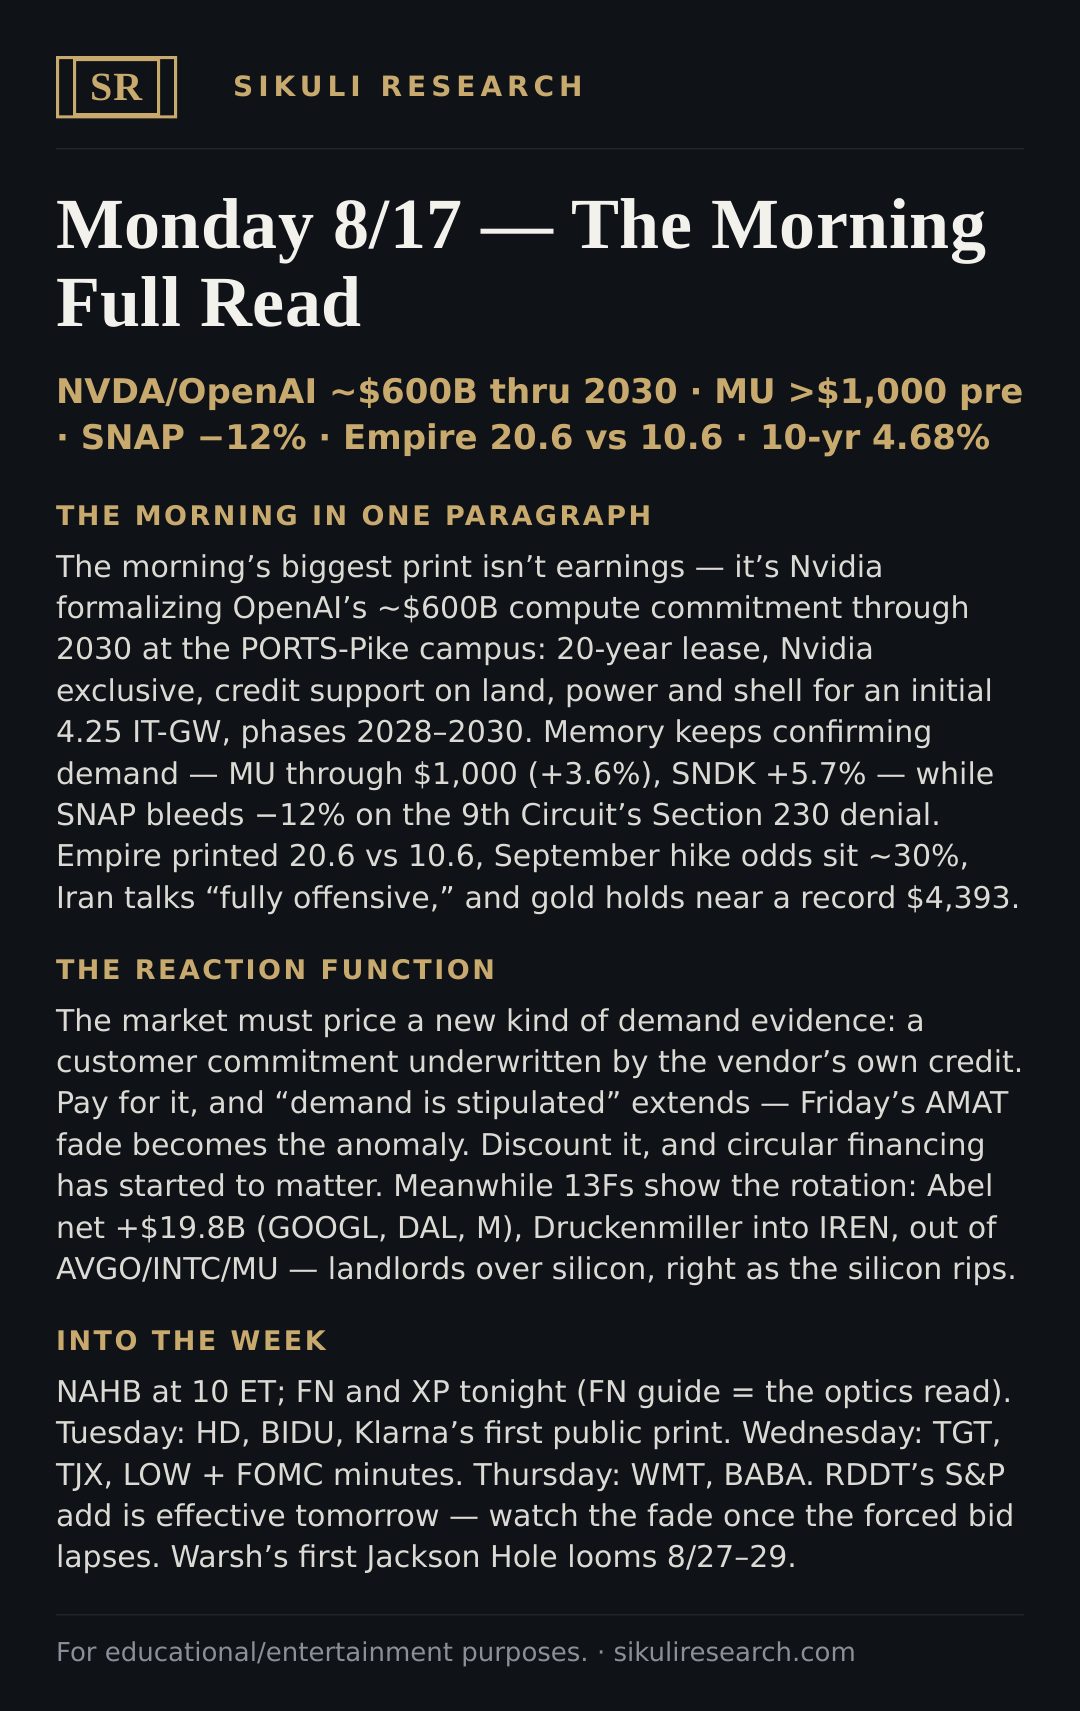
Nvidia formalizes OpenAI's ~$600B compute commitment through 2030 — demand evidence, underwritten by the vendor's own credit. Micron clears $1,000 as memory melts up. Full read at Sikuli Research (link in bio)
New research note: Bloom Energy (BE). Dated Aug 2026.
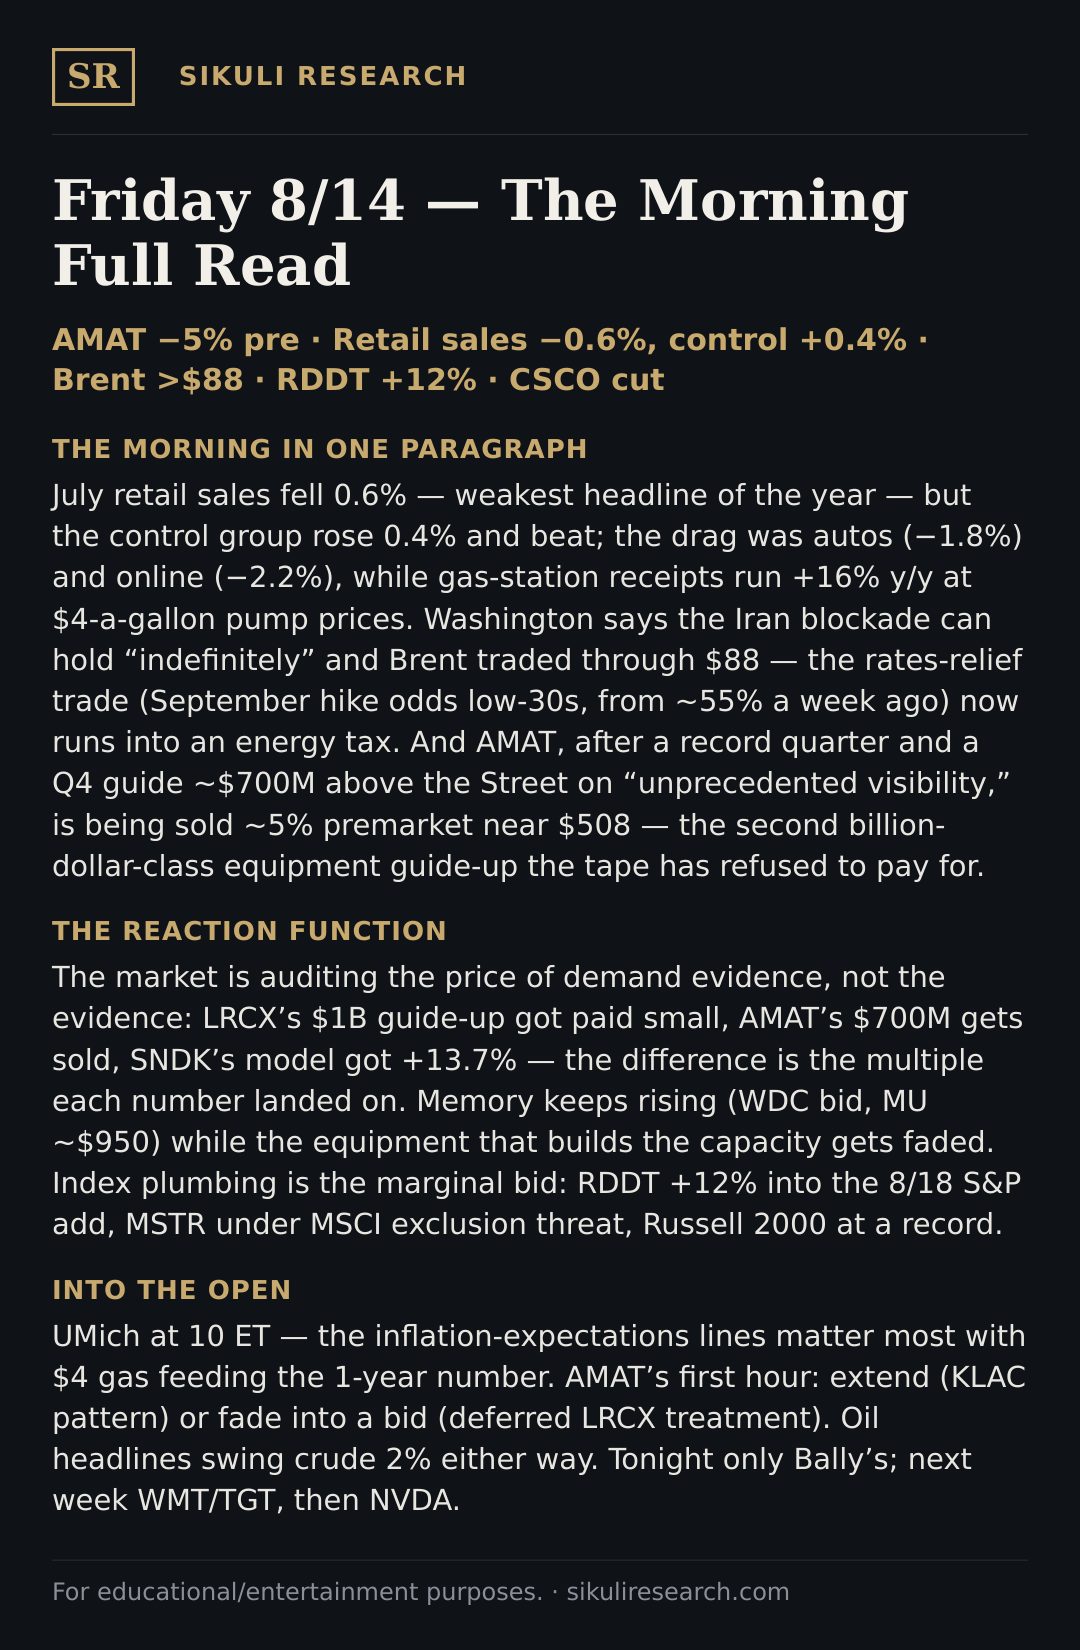
AMAT guided ~$700M above the Street; sold 5% premarket anyway — the second big equipment guide-up the tape won't pay for. Retail sales -0.6%, control +0.4% beat. Oil bid as the Iran blockade hardens. Full read at Sikuli Research (link in bio)
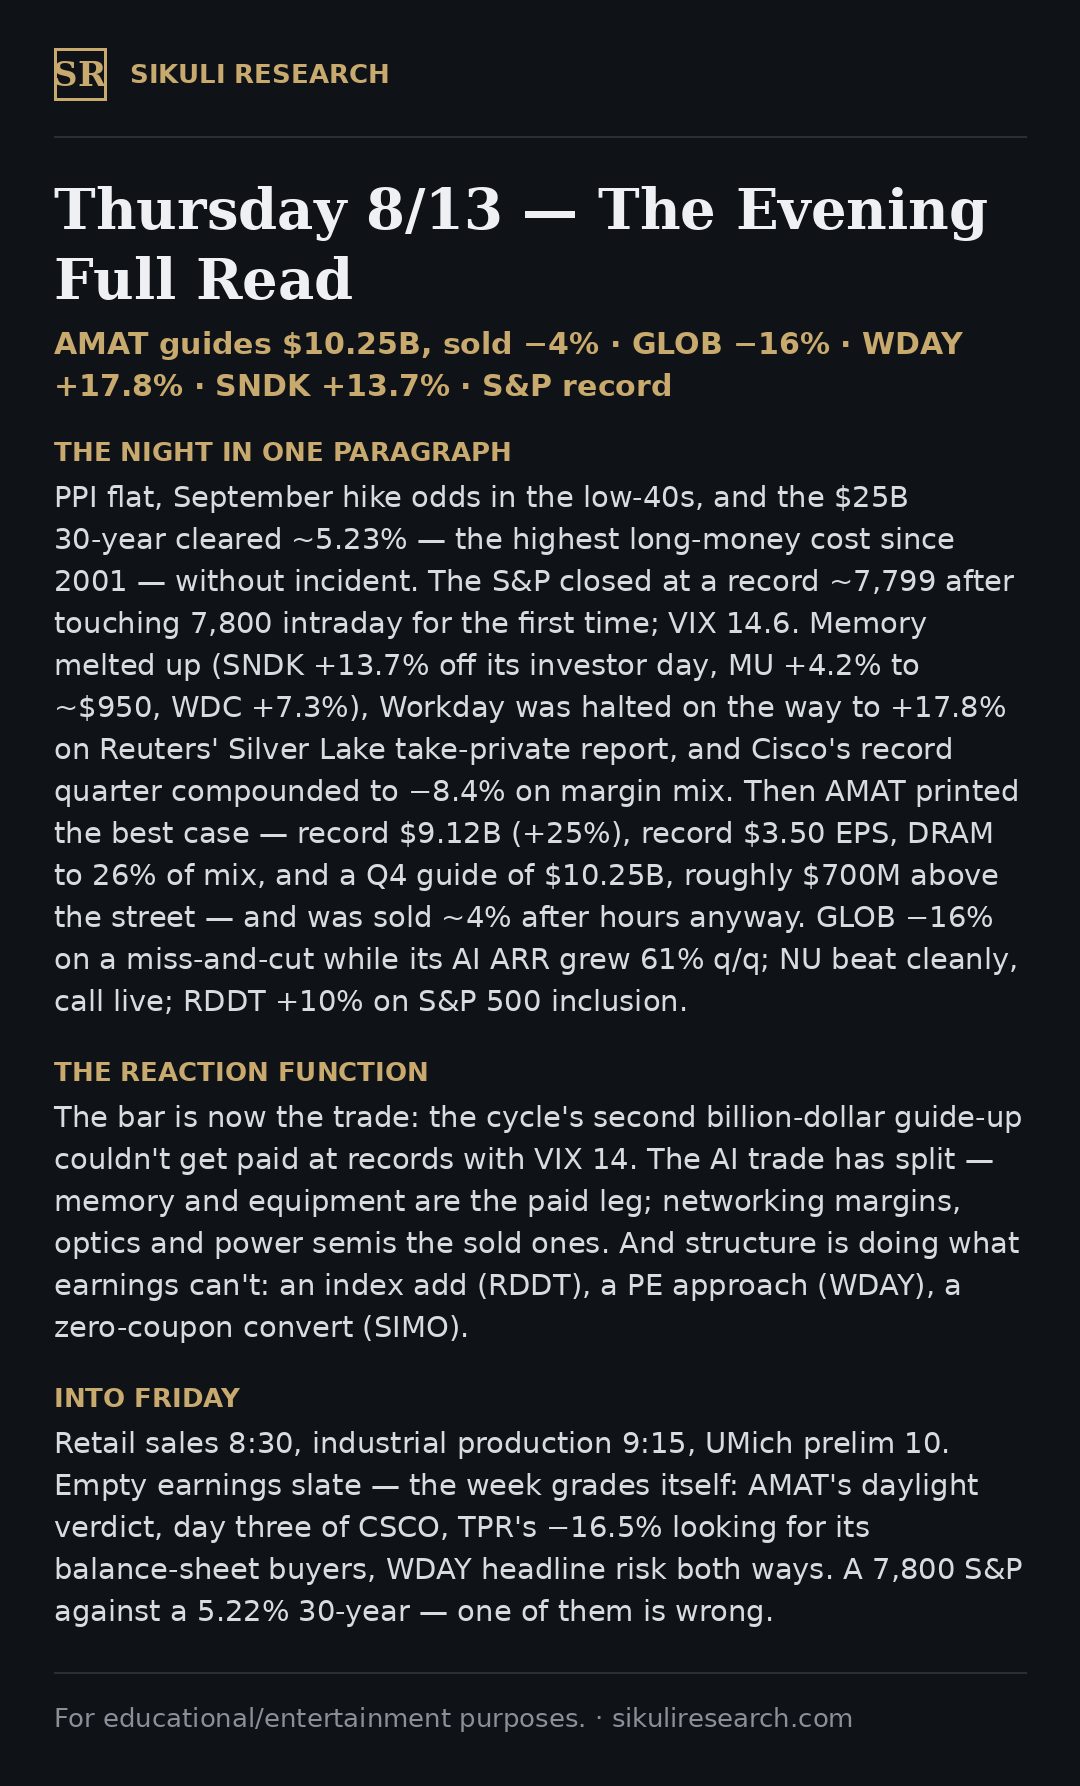
AMAT guides Q4 $700M above the Street and still gets sold. Memory melts up — SNDK +14%, MU ~$950 — while Silver Lake circles Workday. Records at 7,800 with the 30-year at 5.22%. Full read at Sikuli Research (link in bio)
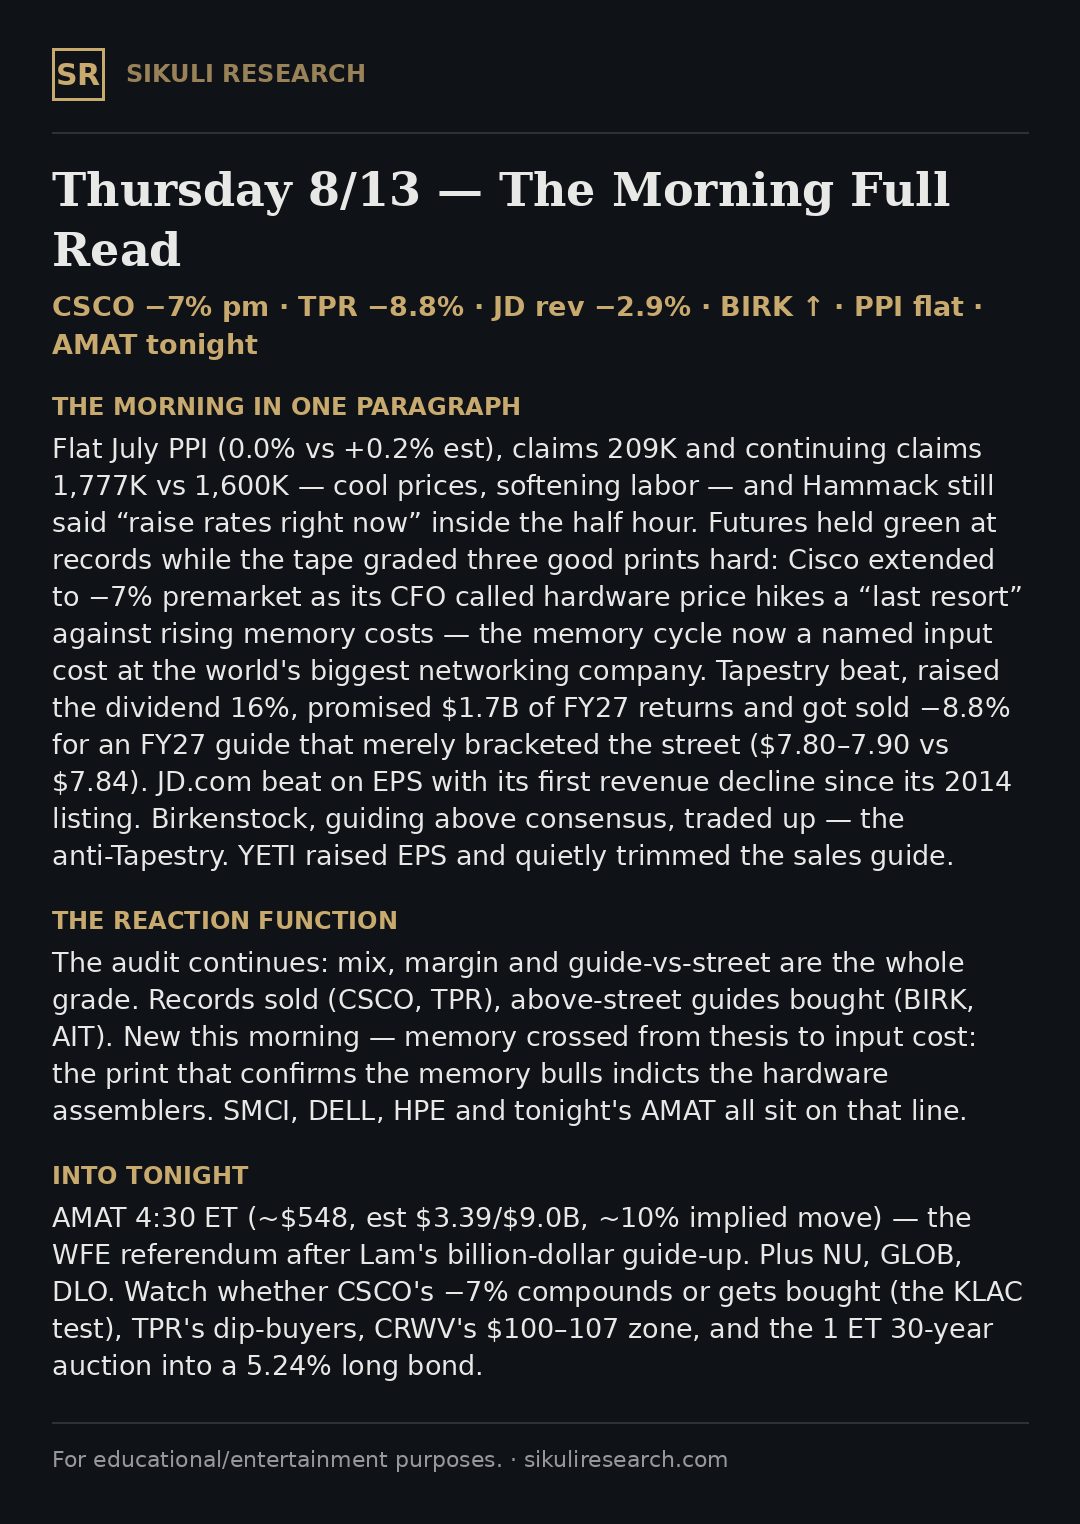
Flat PPI, rising claims — and the tape sold three record prints anyway: CSCO −7% on memory costs, TPR −8.8% on an in-line guide. BIRK, guiding above the street, traded up. AMAT tonight. Full read at Sikuli Research (link in bio)
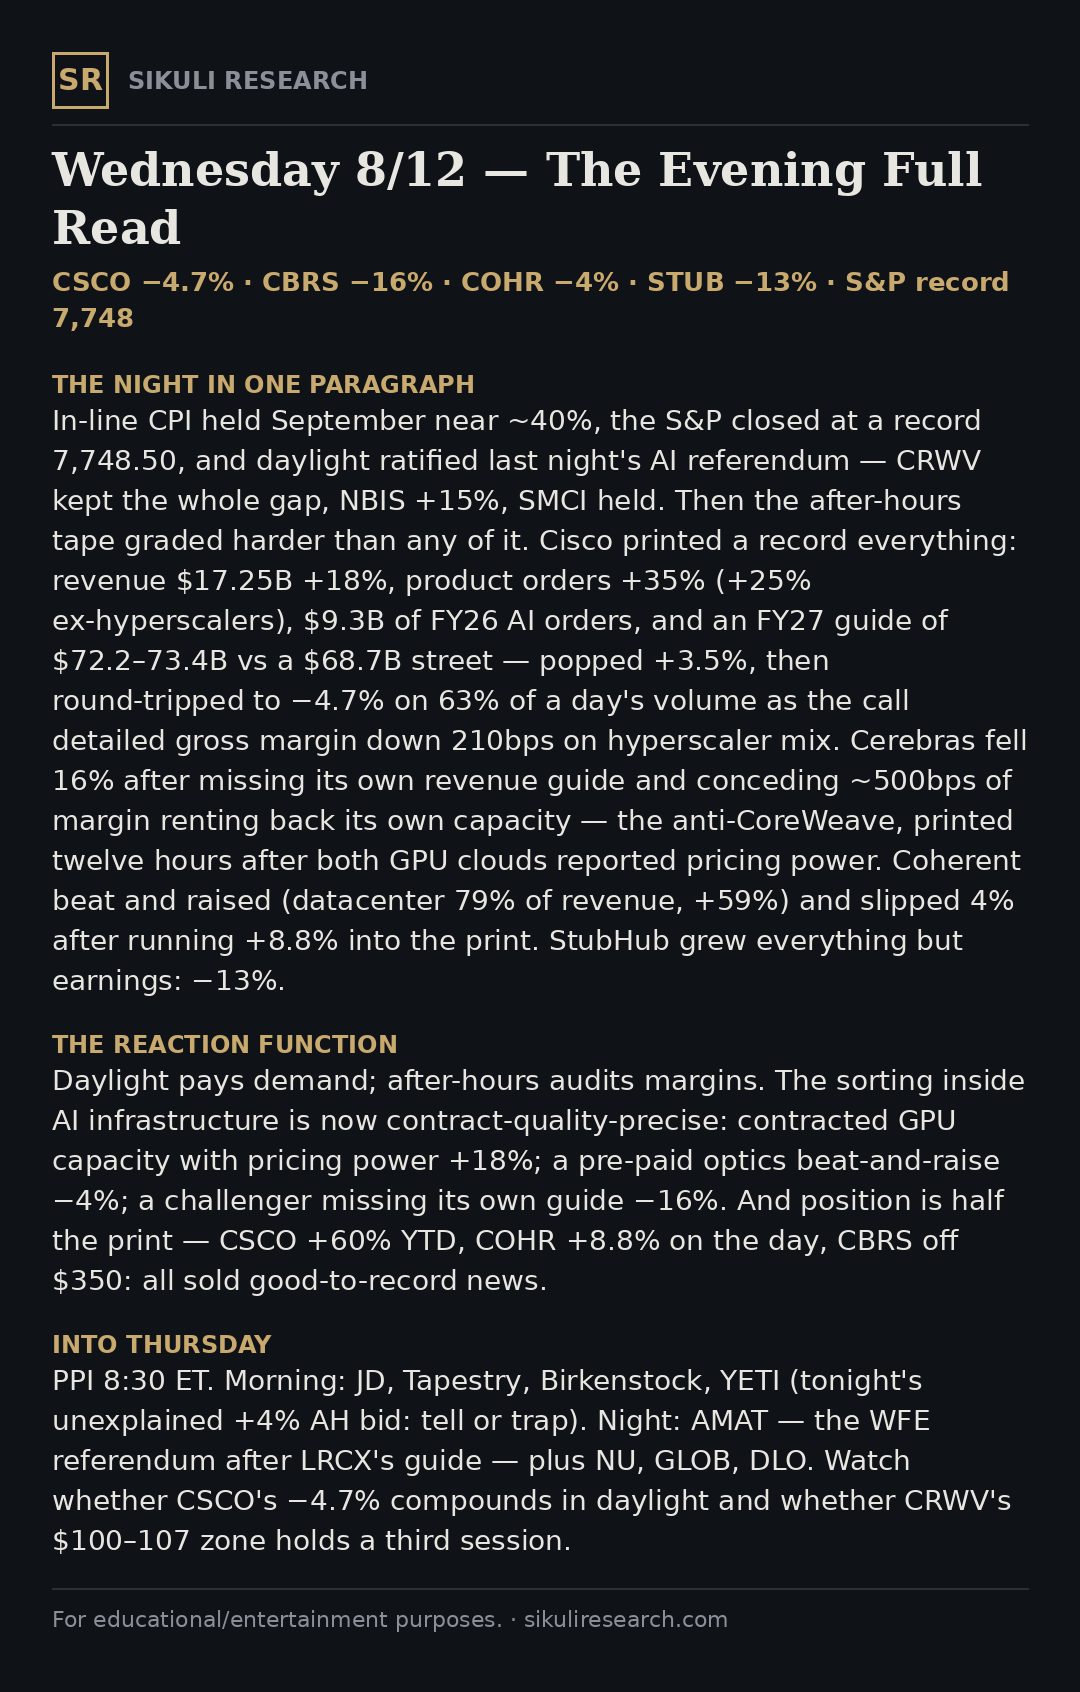
Cisco printed a record year, $9.3B of AI orders, a 14%-growth guide — and sold off 4.7% as the call priced the hyperscaler margin mix. Cerebras −16% on a self-guide miss. Full read at Sikuli Research (link in bio)
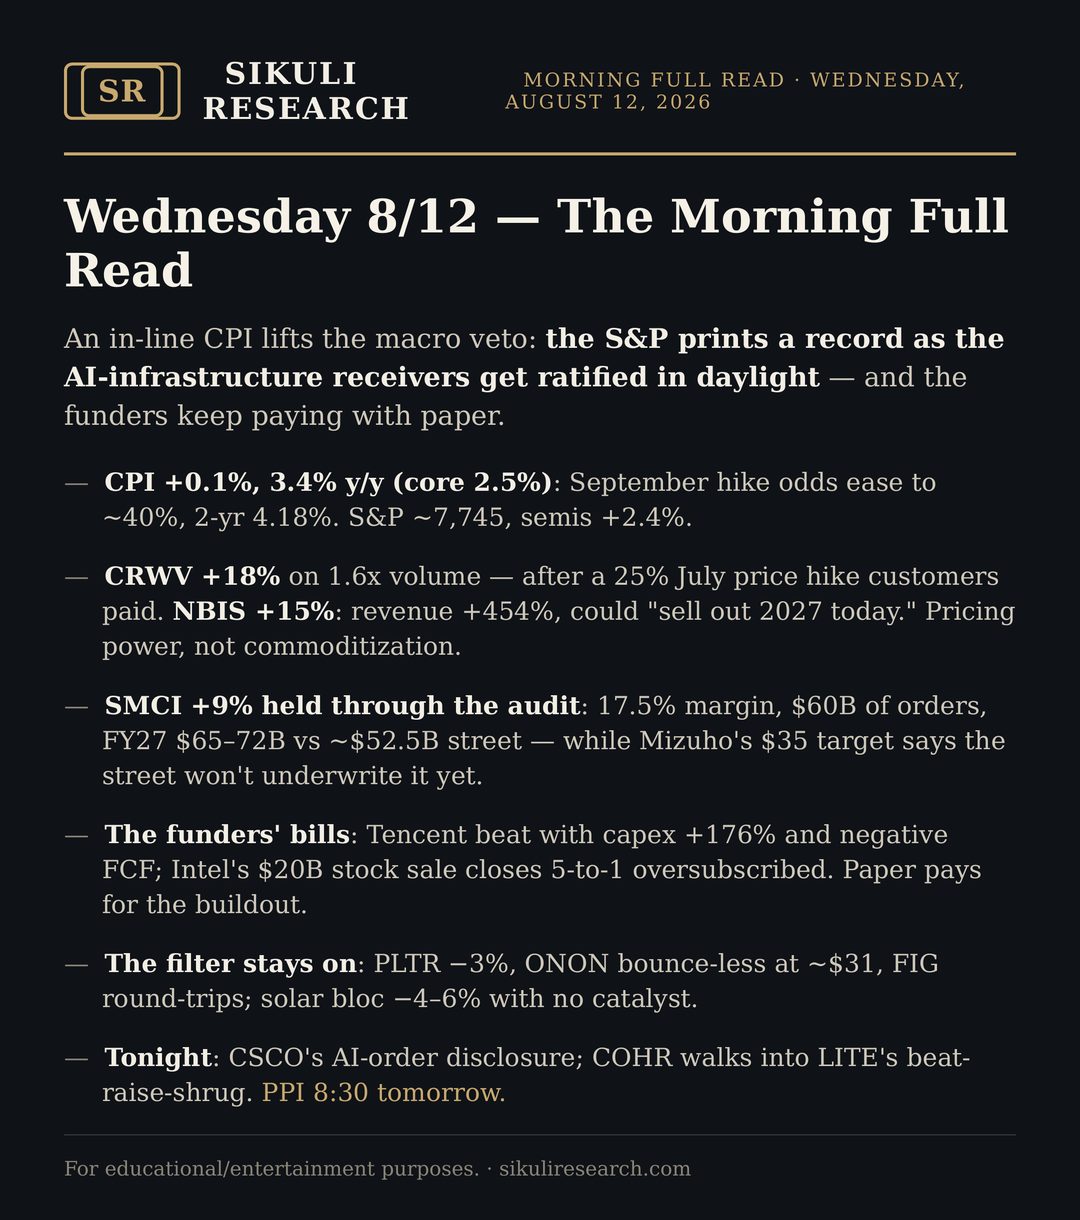
In-line CPI lifts the veto: S&P prints a record as CRWV +18%, NBIS +15%, SMCI +9% — the AI receivers get paid in daylight while Tencent and Intel pay with paper. Full read at Sikuli Research (link in bio)
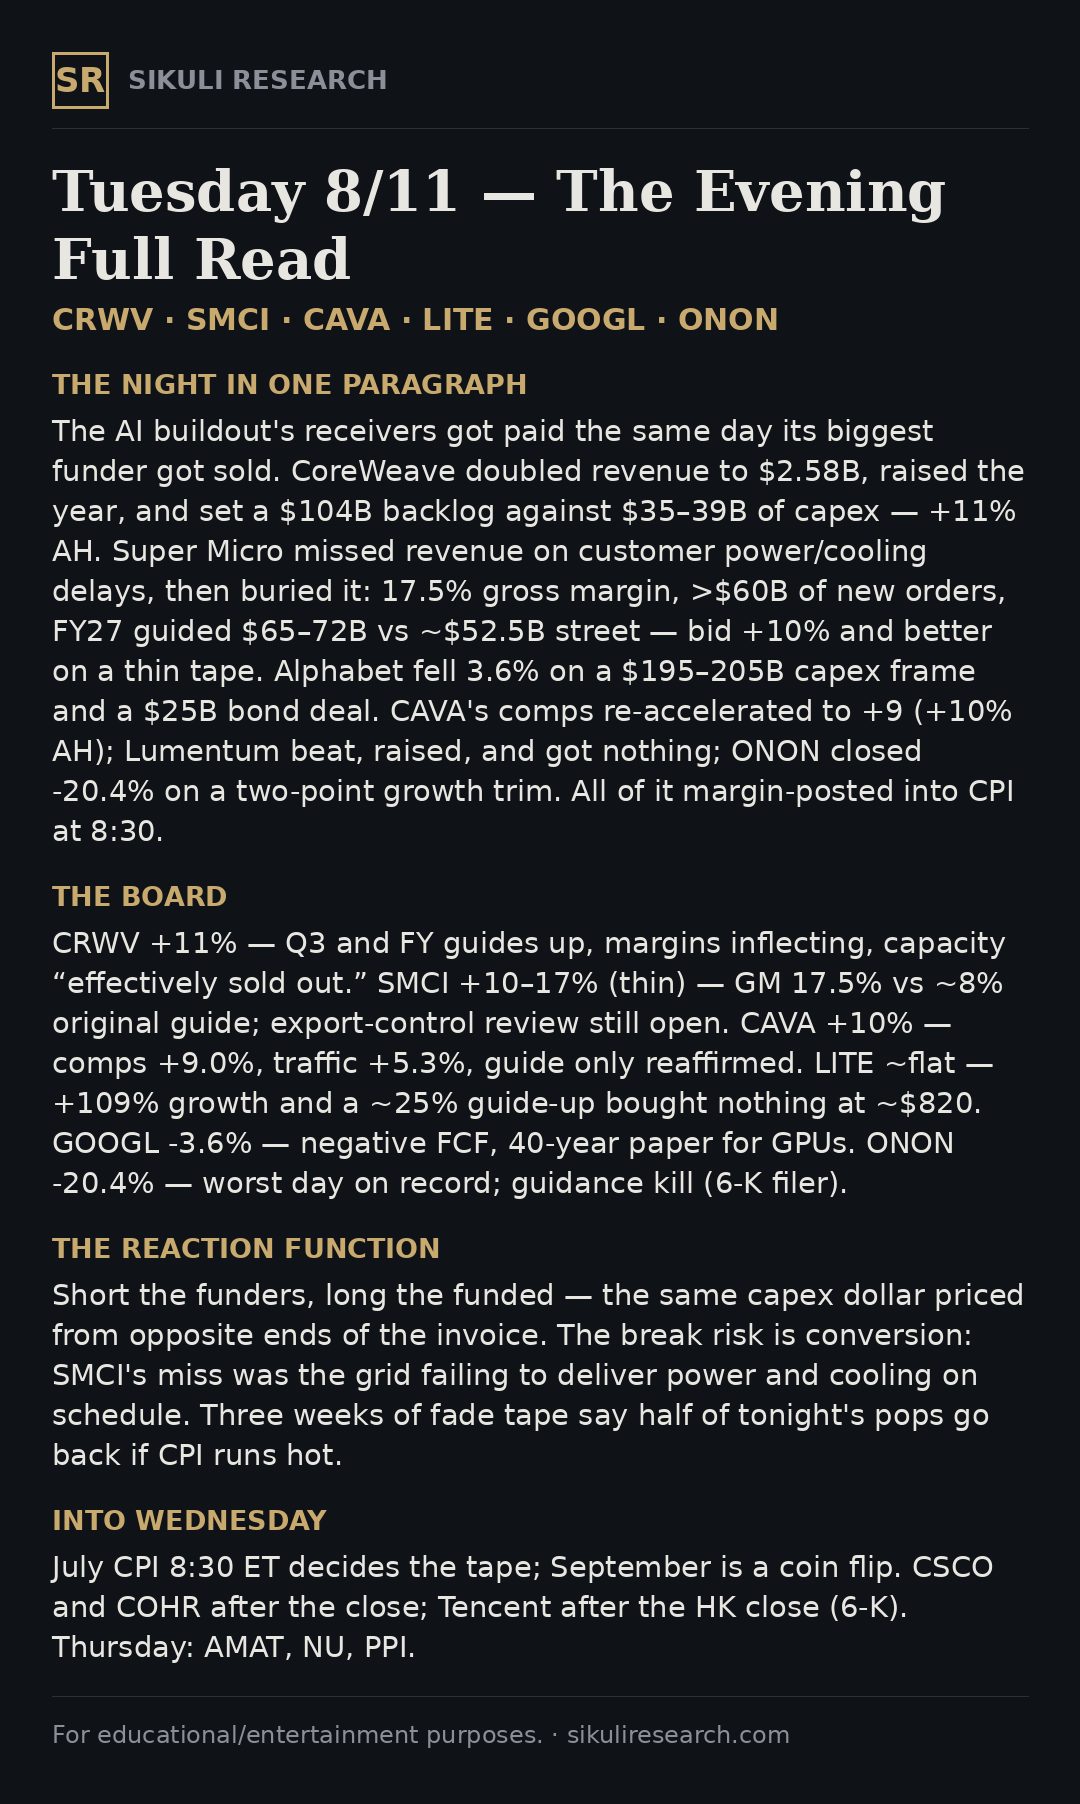
CoreWeave +11% AH on a $104B backlog; Super Micro guides FY27 to $65–72B on >$60B of new orders. The AI buildout's receivers got paid the day its funders got sold. CPI at 8:30 decides how much sticks. Full read at Sikuli Research (link in bio)
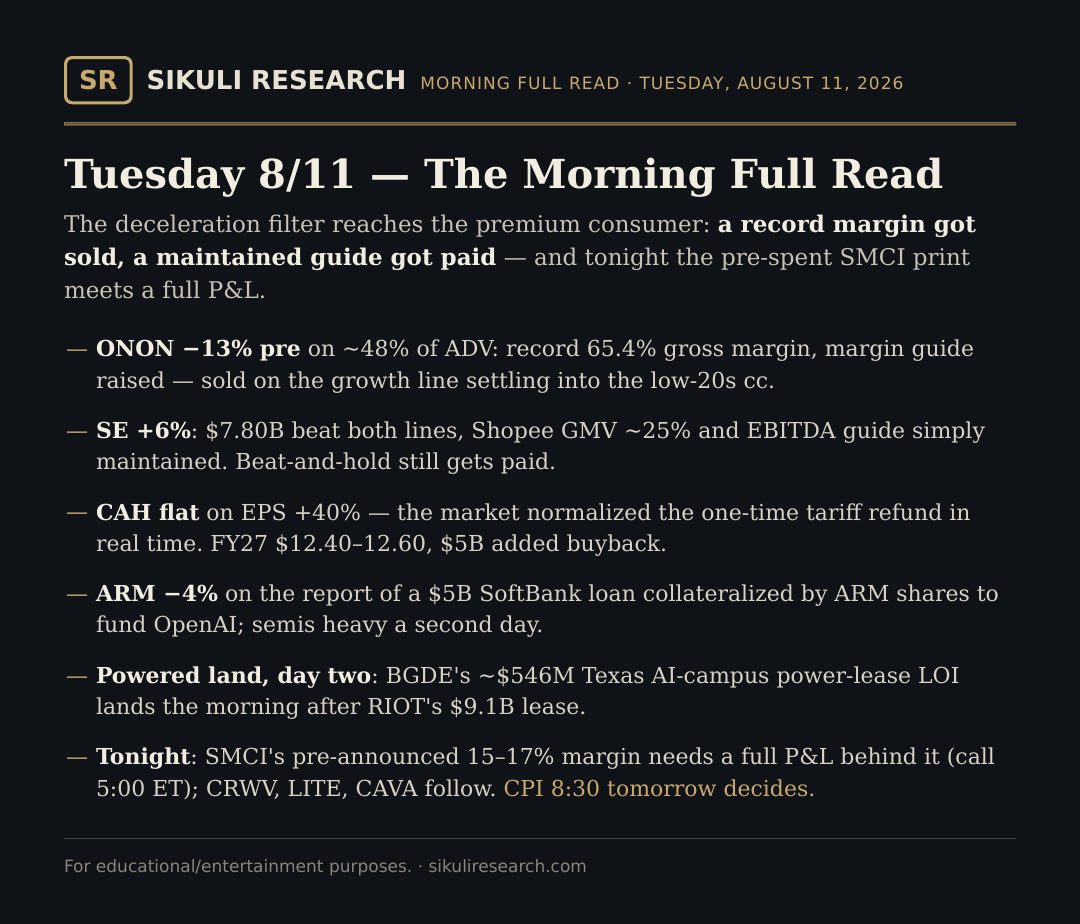
ONON printed a record margin and got sold 13% pre — the deceleration filter reaches the premium consumer. SE paid for beat-and-maintain. Tonight: SMCI's pre-announced margin meets the full P&L. Full read at Sikuli Research (link in bio)
★★★☆☆ No consensus staged. On Holding posted Q2 revenue of CHF 850M, up 14% reported and 22% constant currency, with gross margin expanding 390 basis points to a record 65%. #QQQ #SPX · Sikuli Research — educational, not advice.
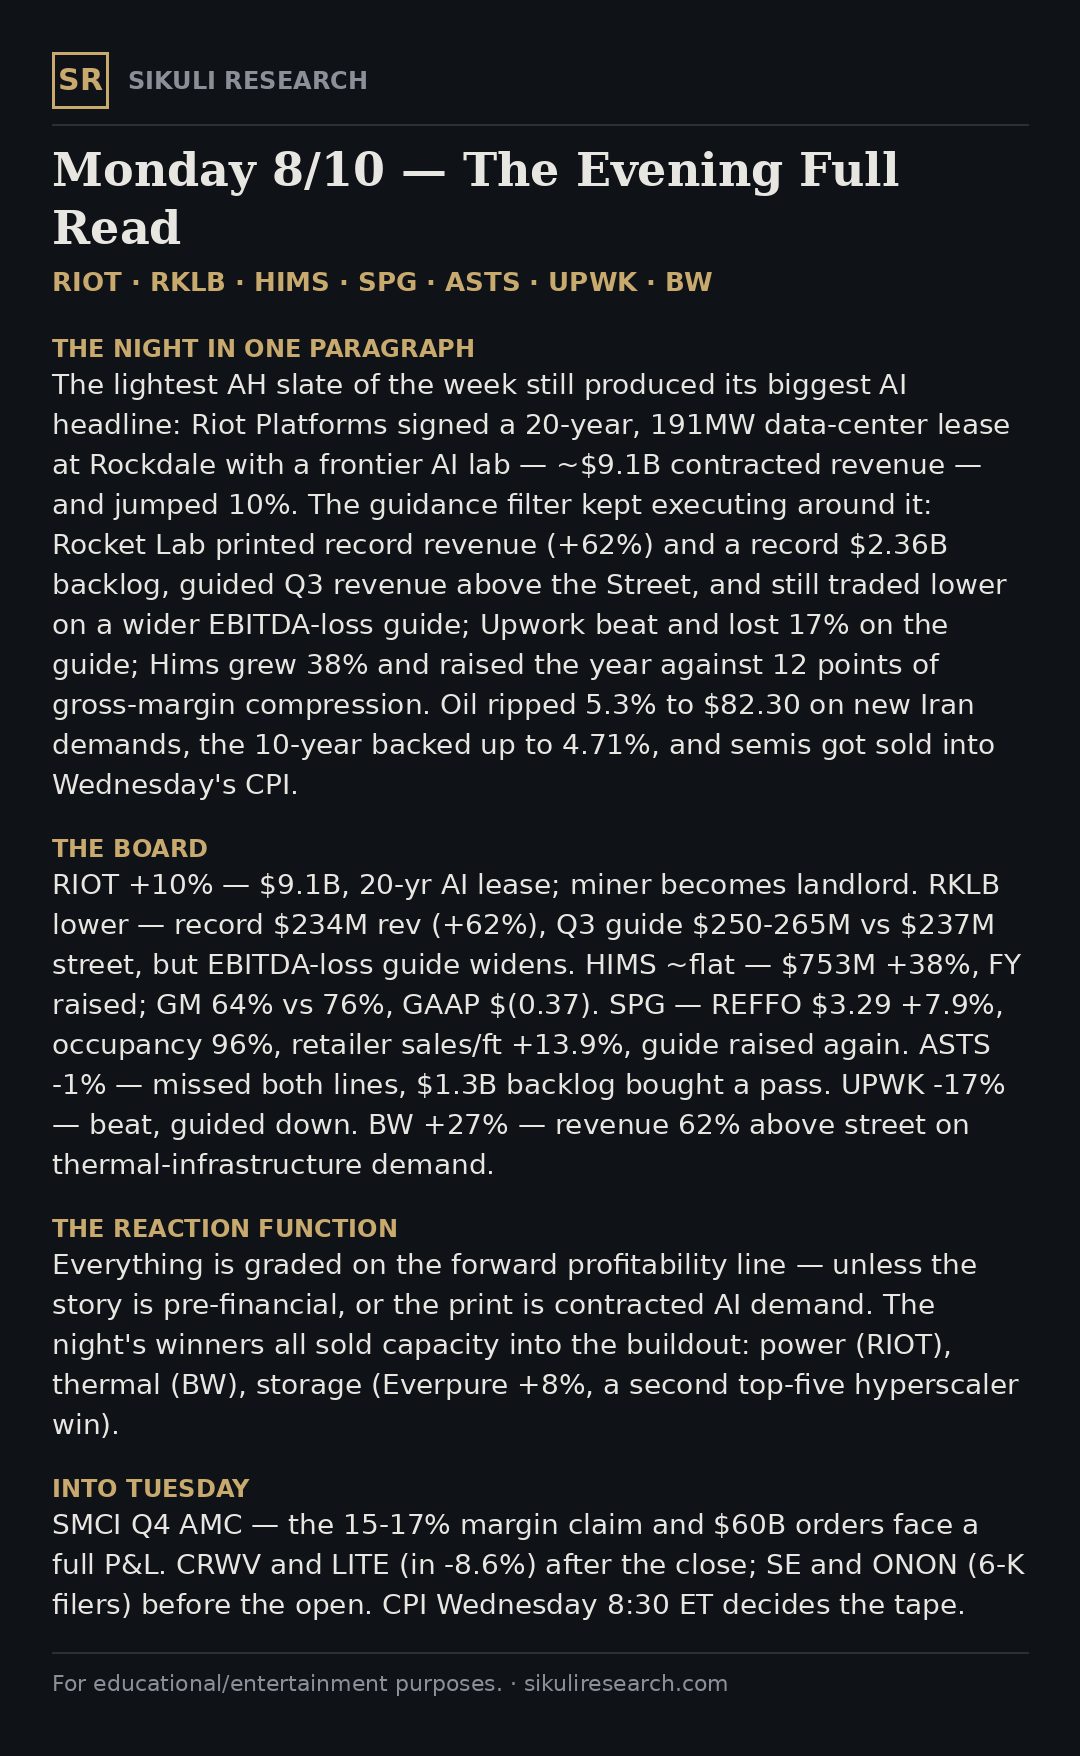
Riot signs a 20-year, 191MW lease with a frontier AI lab — ~$9.1B contracted. The miner becomes a landlord while the guidance filter clips Rocket Lab's record quarter and oil rips 5% into Wednesday's CPI. Full read at Sikuli Research (link in bio)
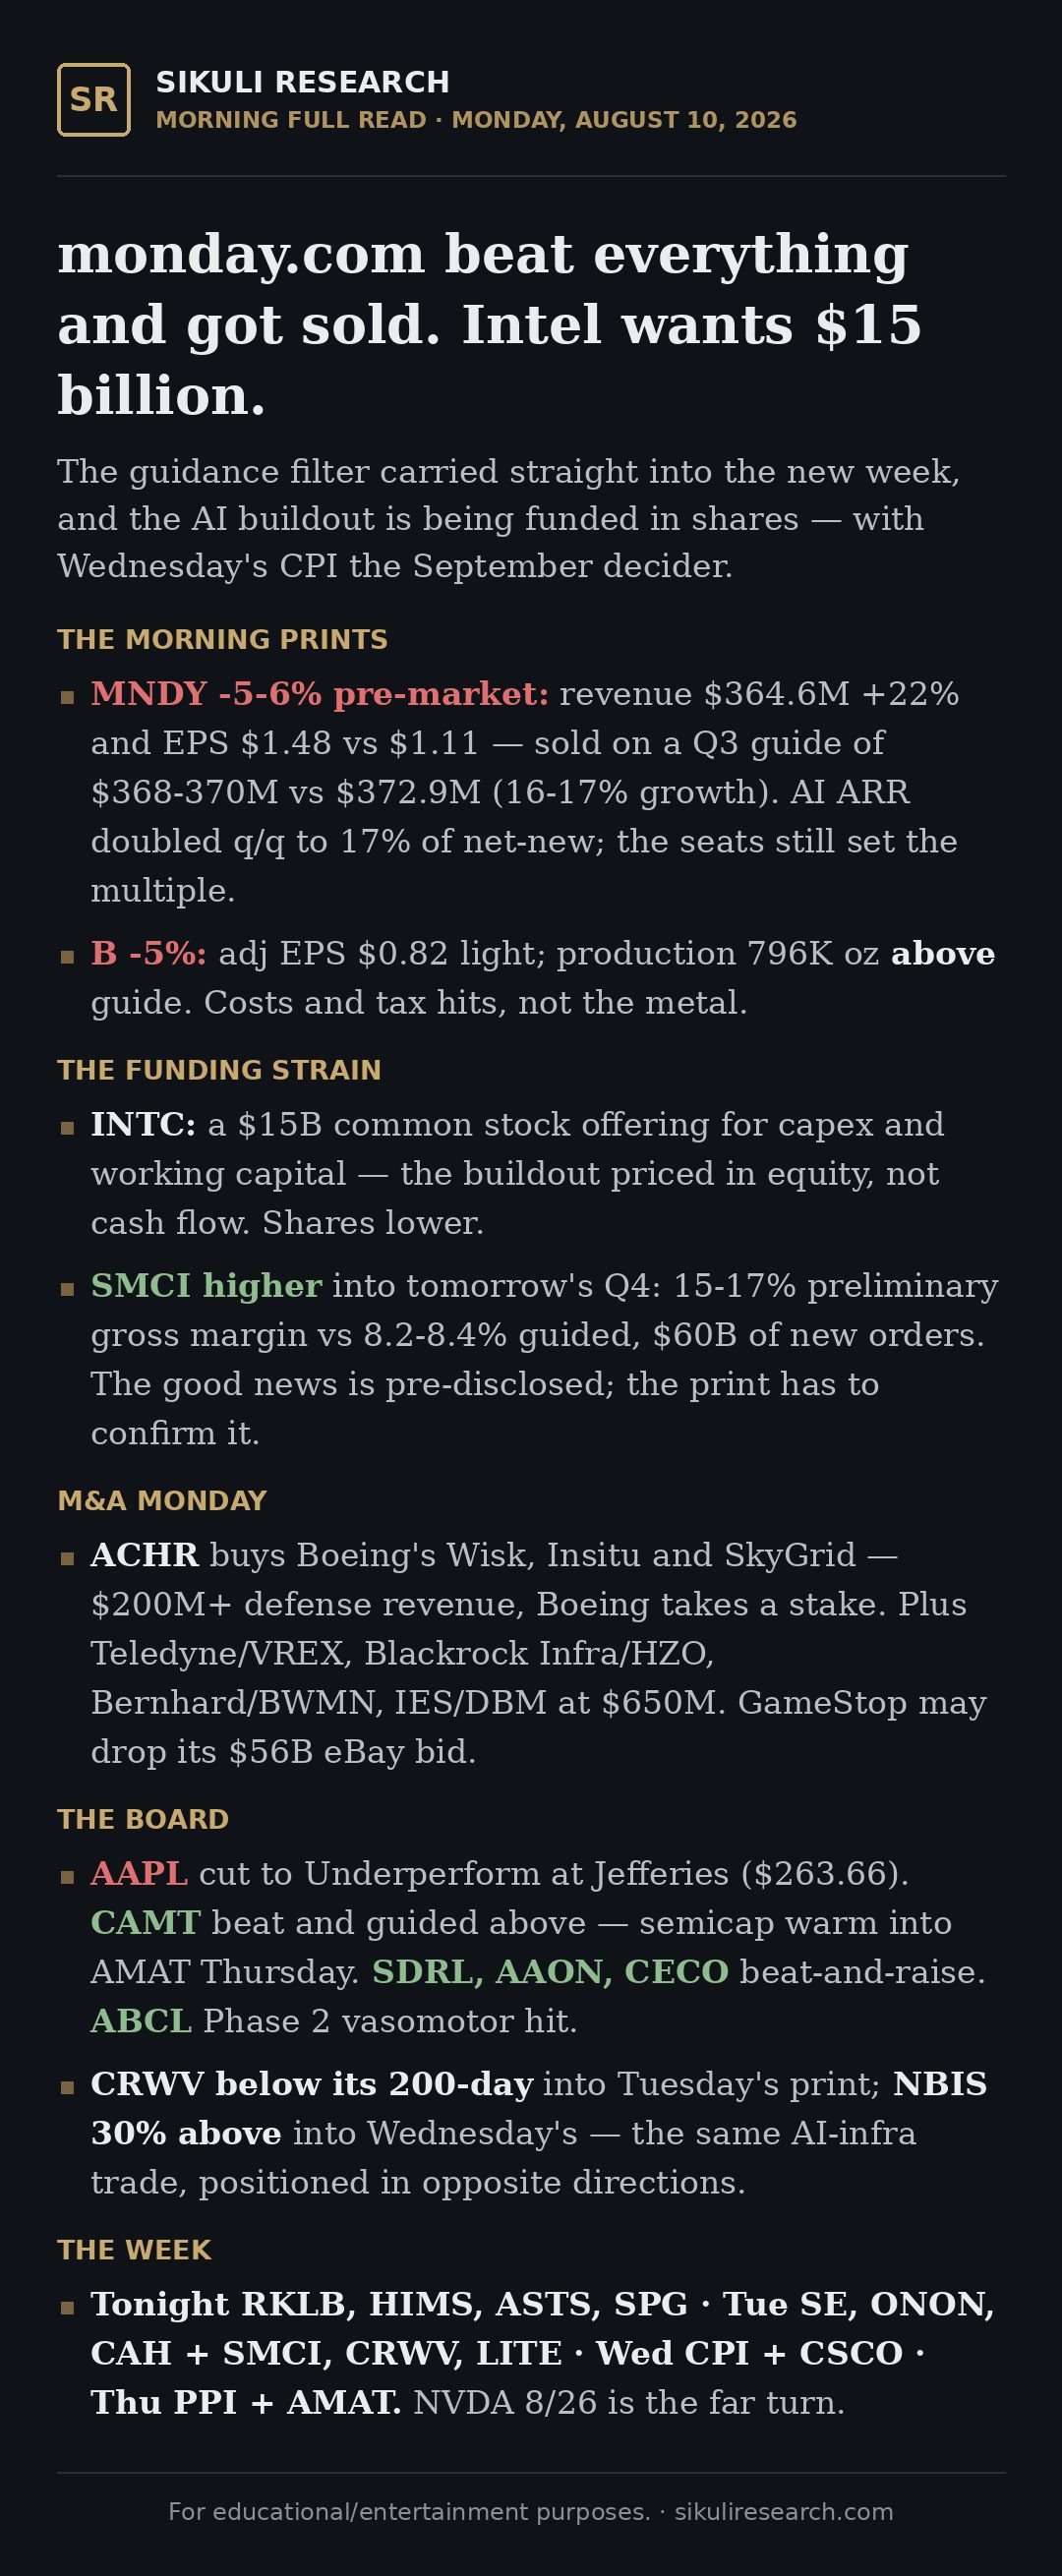
MNDY beat everything and got sold on the guide. Intel wants $15B of fresh equity to fund the buildout. SMCI paid into tomorrow's print, five deals before the bell — CPI Wednesday decides. Full read at Sikuli Research (link in bio)
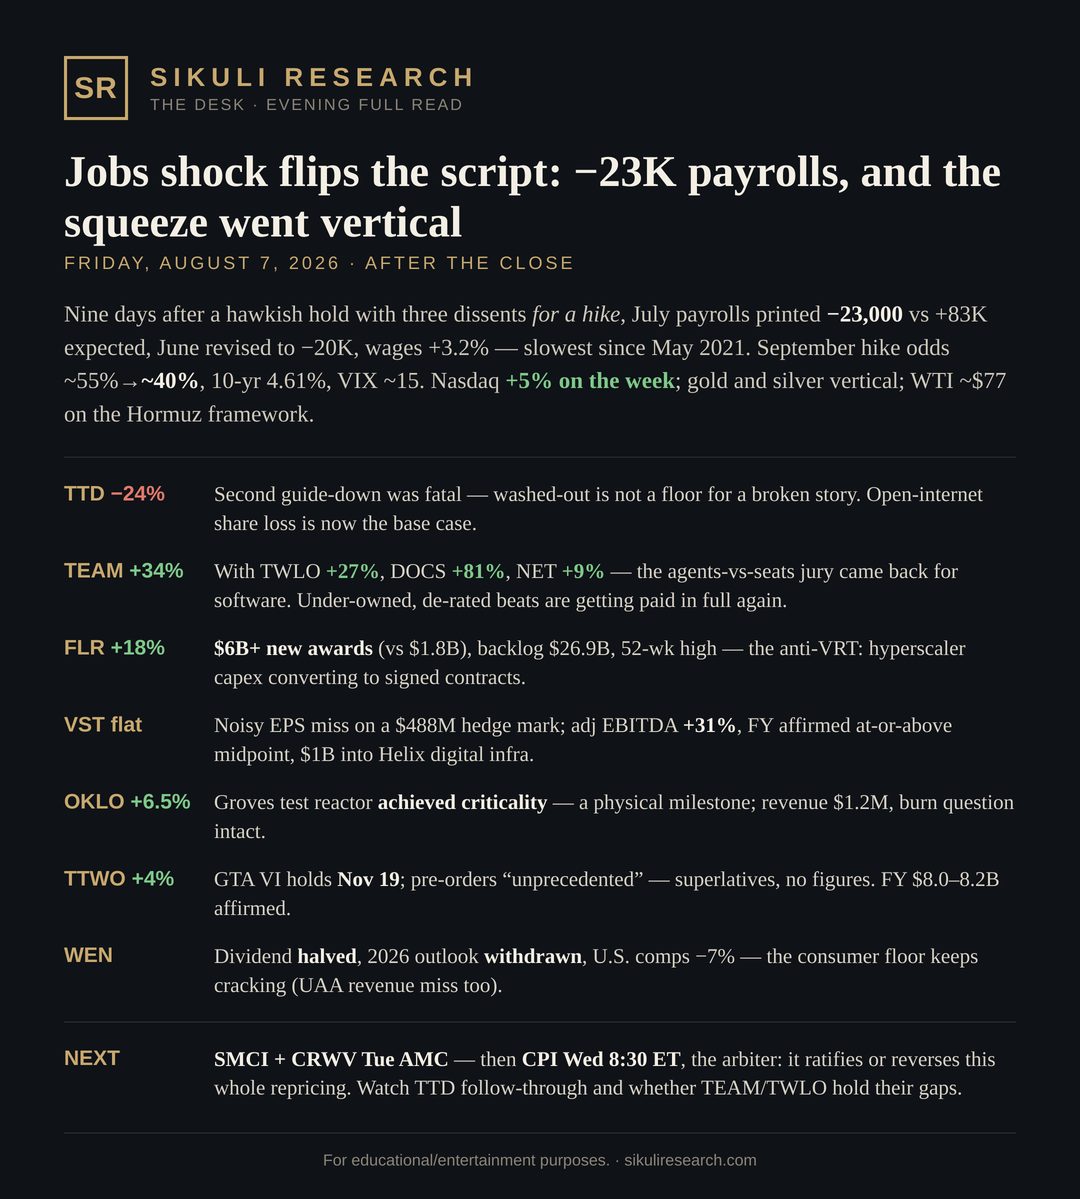
July payrolls −23K flipped the Fed script and the squeeze went vertical: TEAM +34%, TWLO +27%, DOCS +81% — while TTD gave up another 24%. FLR +18% on $6B of awards. CPI Wednesday is the arbiter. Full read at Sikuli Research (link in bio)
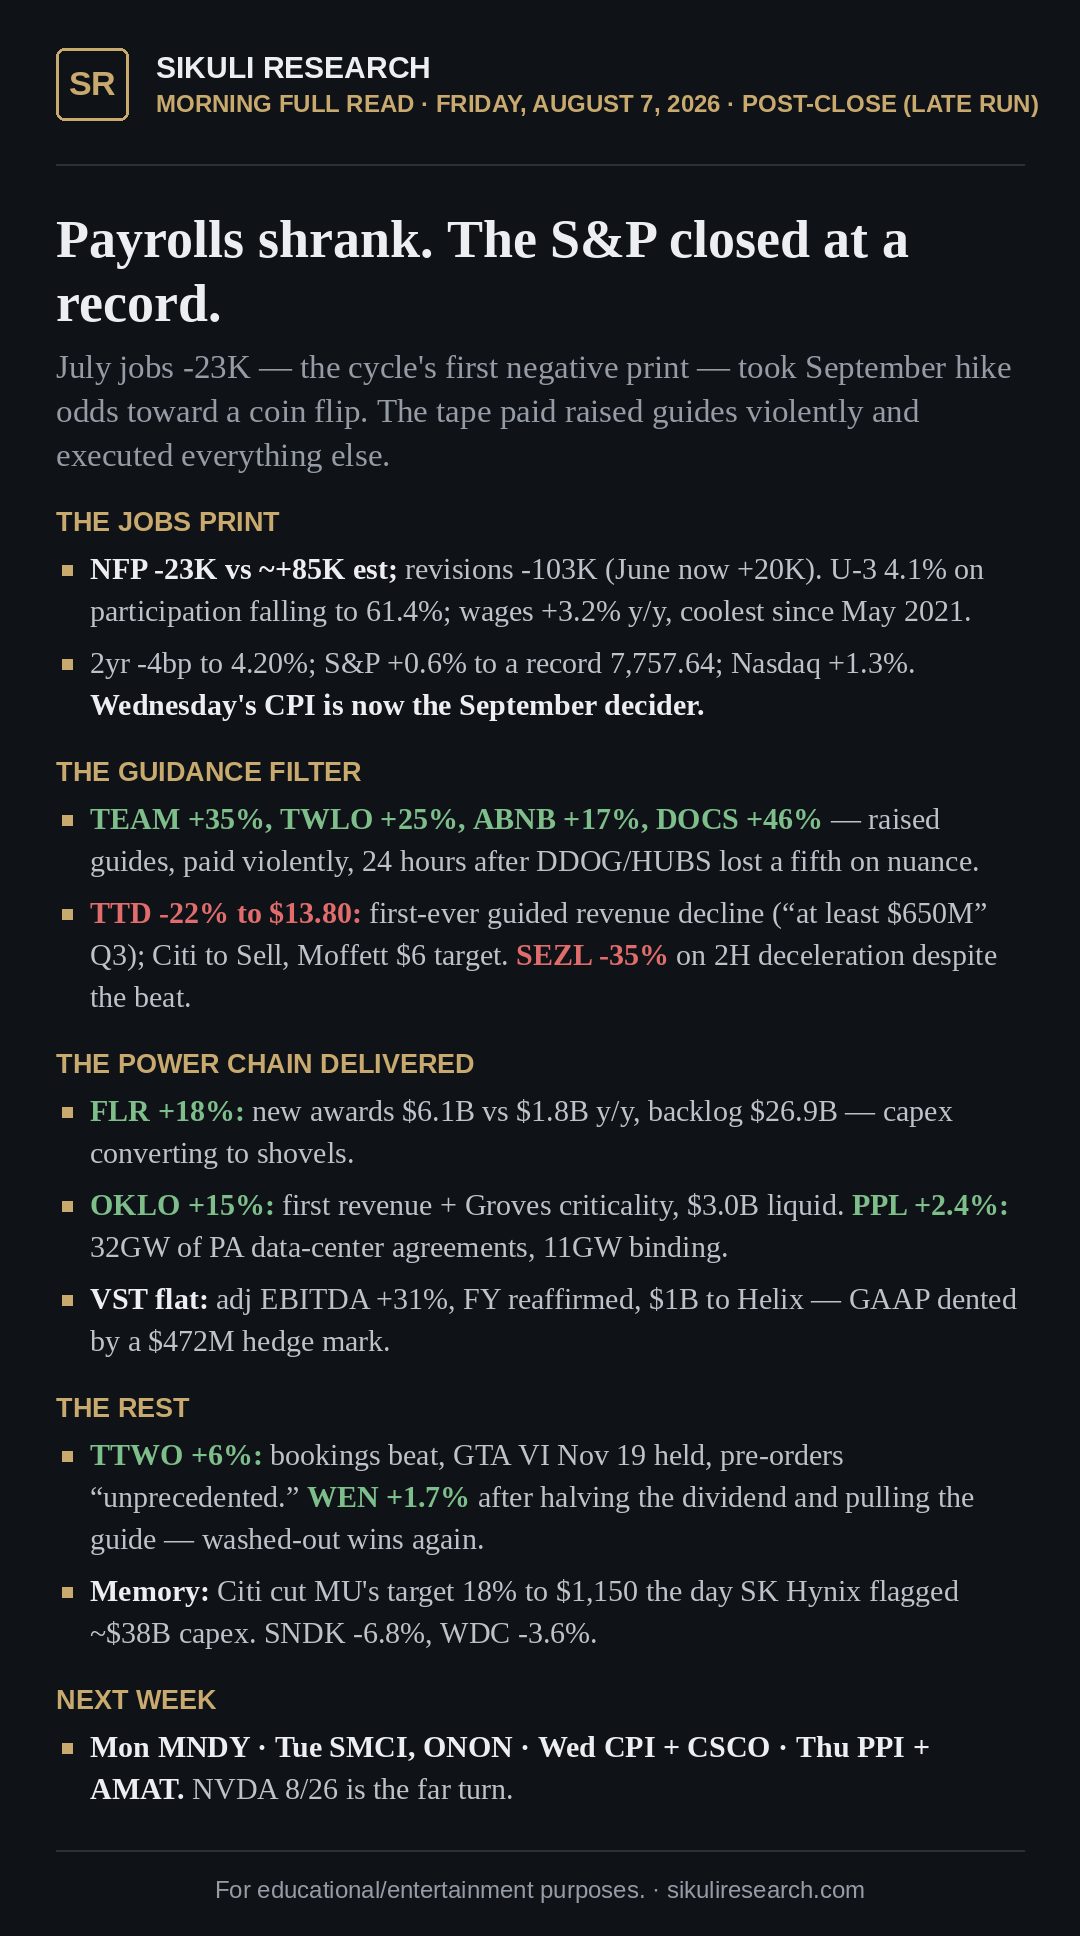
Payrolls shrank (-23K) and the S&P closed at a record. The tape paid raises — TEAM +35%, ABNB +17% — and executed misses: TTD -22%. FLR +18% led the power chain. CPI Wednesday decides September. Full read at Sikuli Research (link in bio)
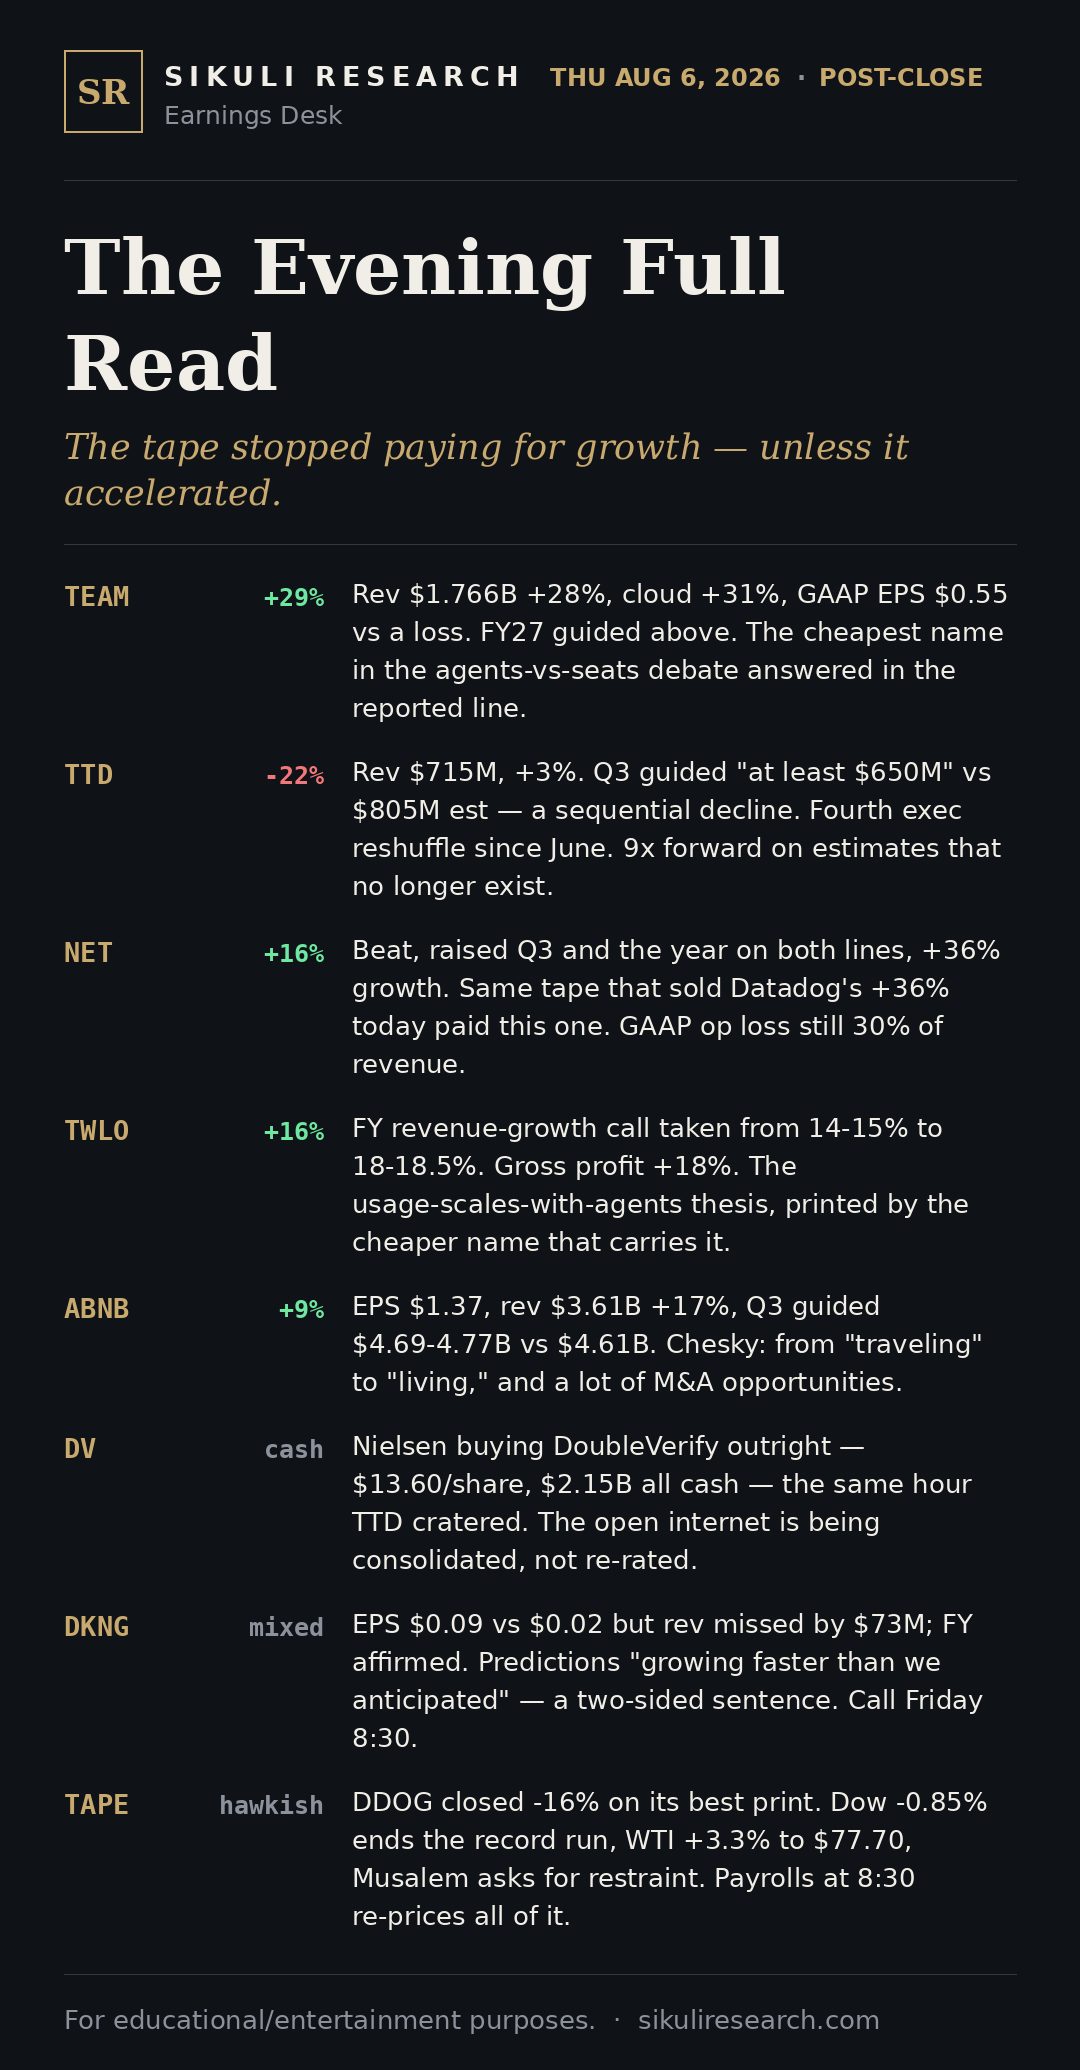
Atlassian +29% on 28% growth and a GAAP profit swing; Trade Desk -22% guiding to a sequential decline. The tape stopped paying for growth unless it accelerated. Full read at Sikuli Research (link in bio)
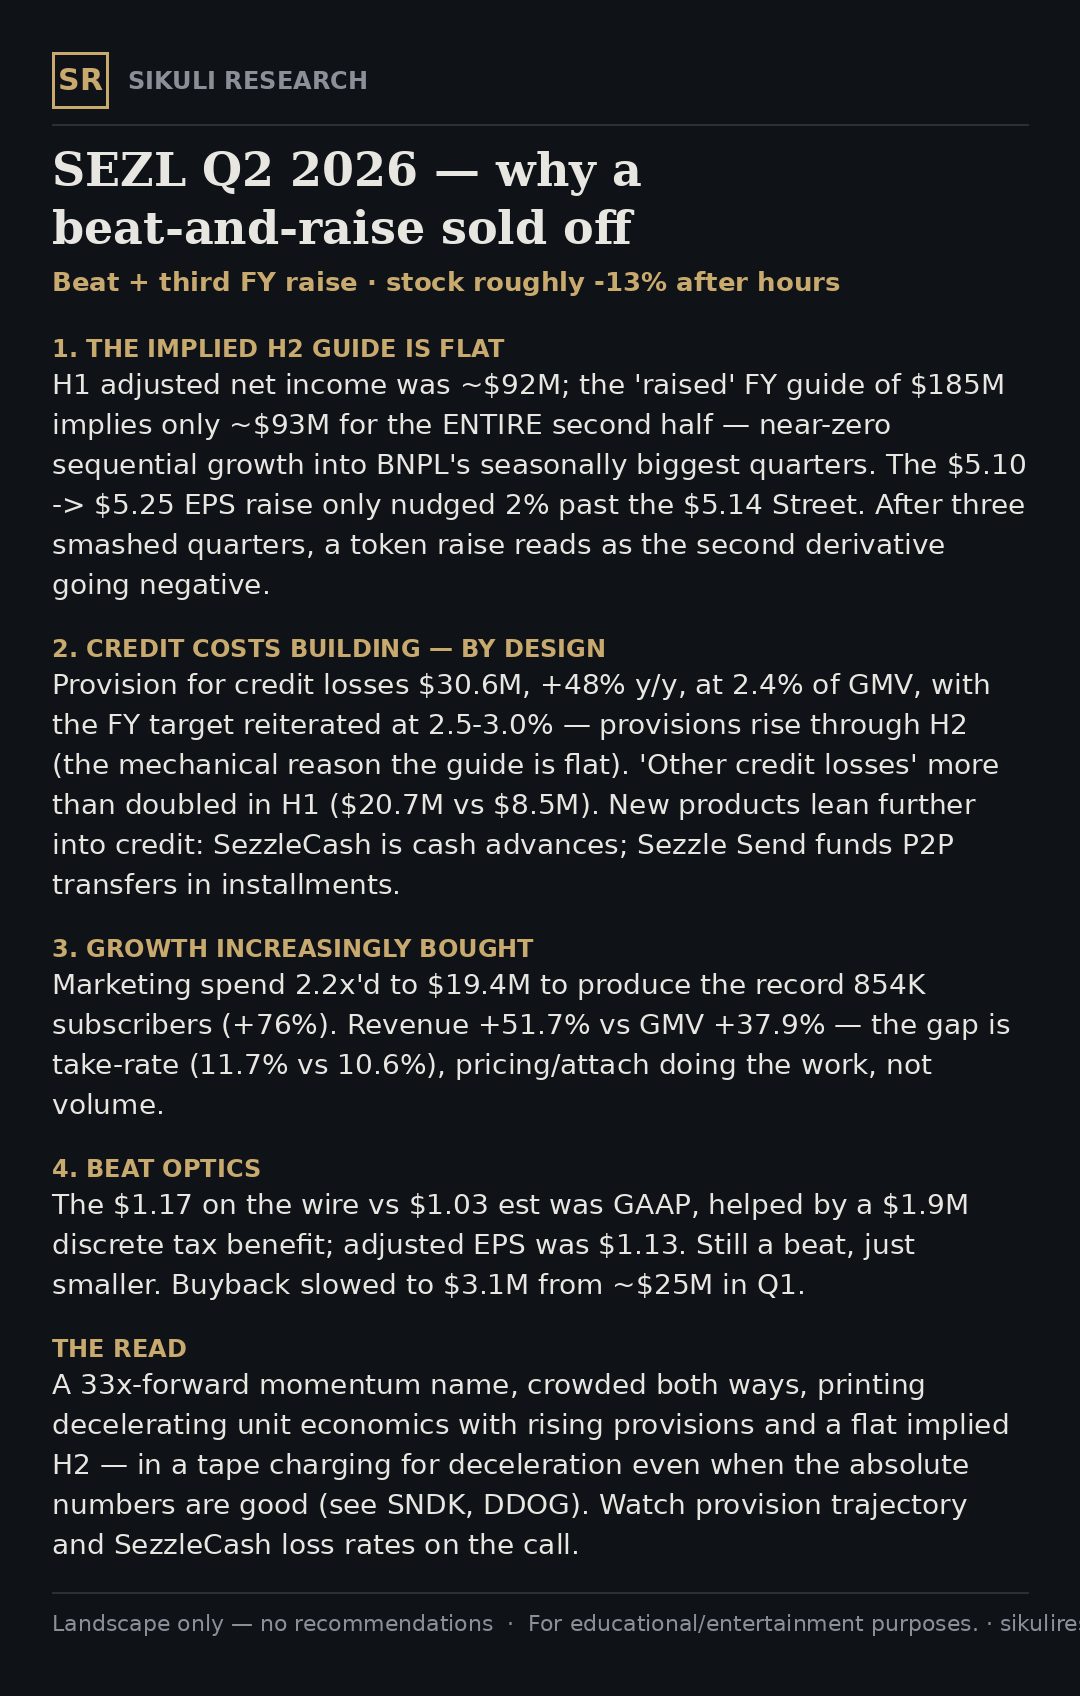
The raised FY guide implies a FLAT H2 (~$93M adj NI vs ~$92M H1), provisions building toward 2.5-3.0% of GMV, marketing 2.2x'd. Breakdown on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
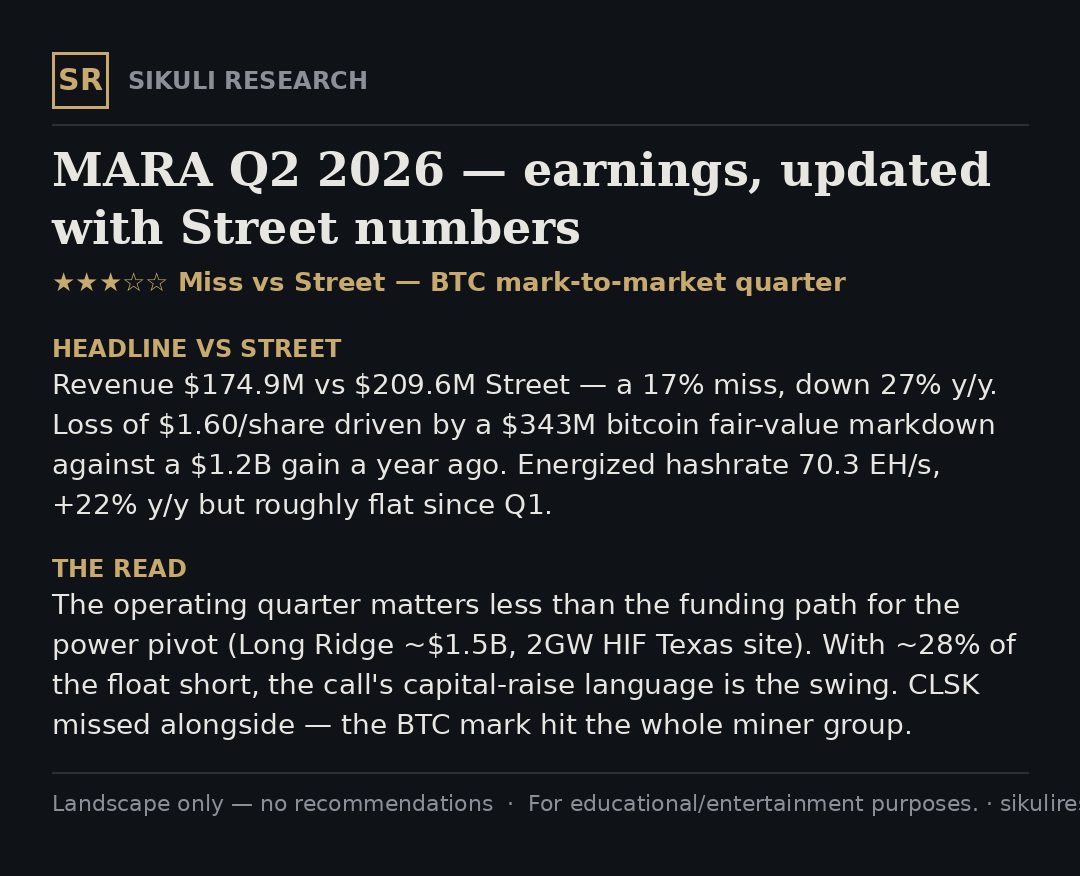
★★★☆☆ Rev $174.9M vs $209.6M Street (-27% y/y). Loss of $1.60/sh on a $343M BTC markdown vs +$1.2B a yr ago. Hashrate 70.3 EH/s +22%. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
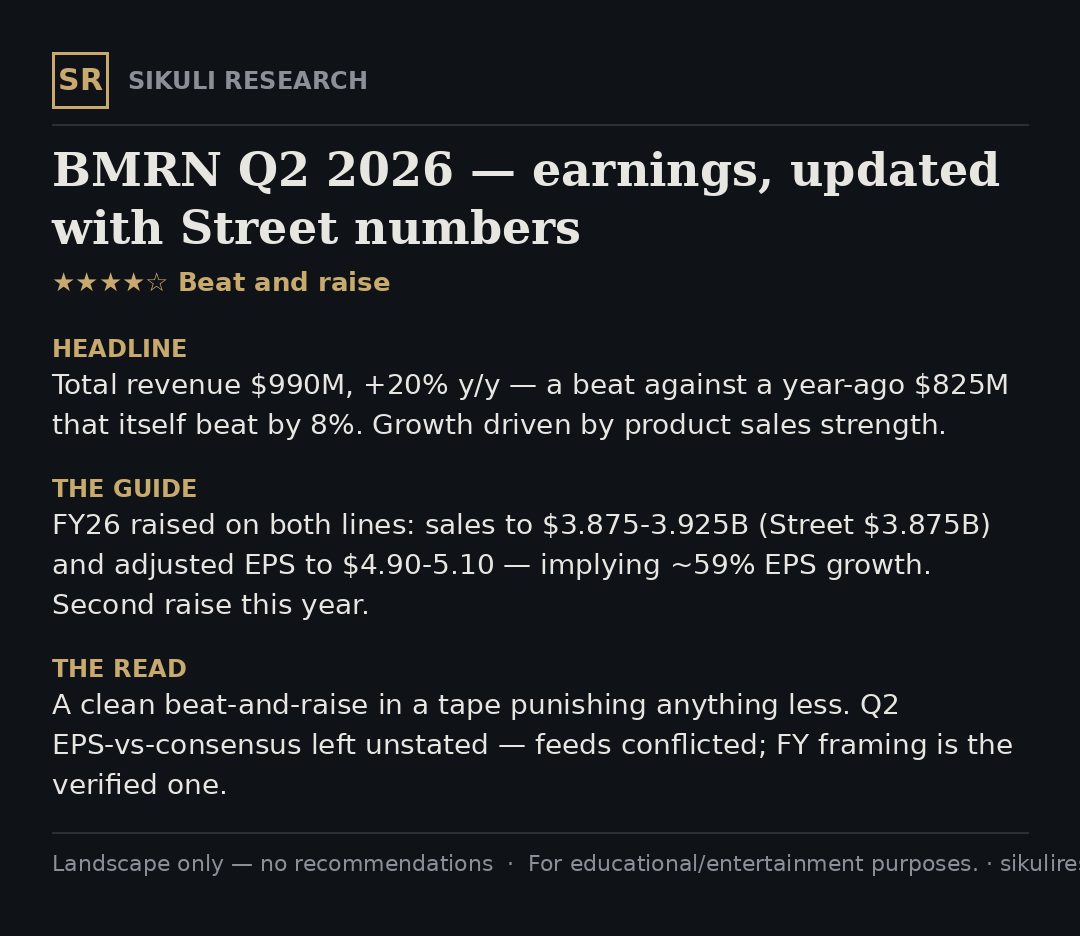
★★★★☆ Rev $990M +20% — beat. FY RAISED: sales $3.875-3.925B (Street $3.875B), adj EPS $4.90-5.10, ~59% growth. Clean beat-and-raise. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
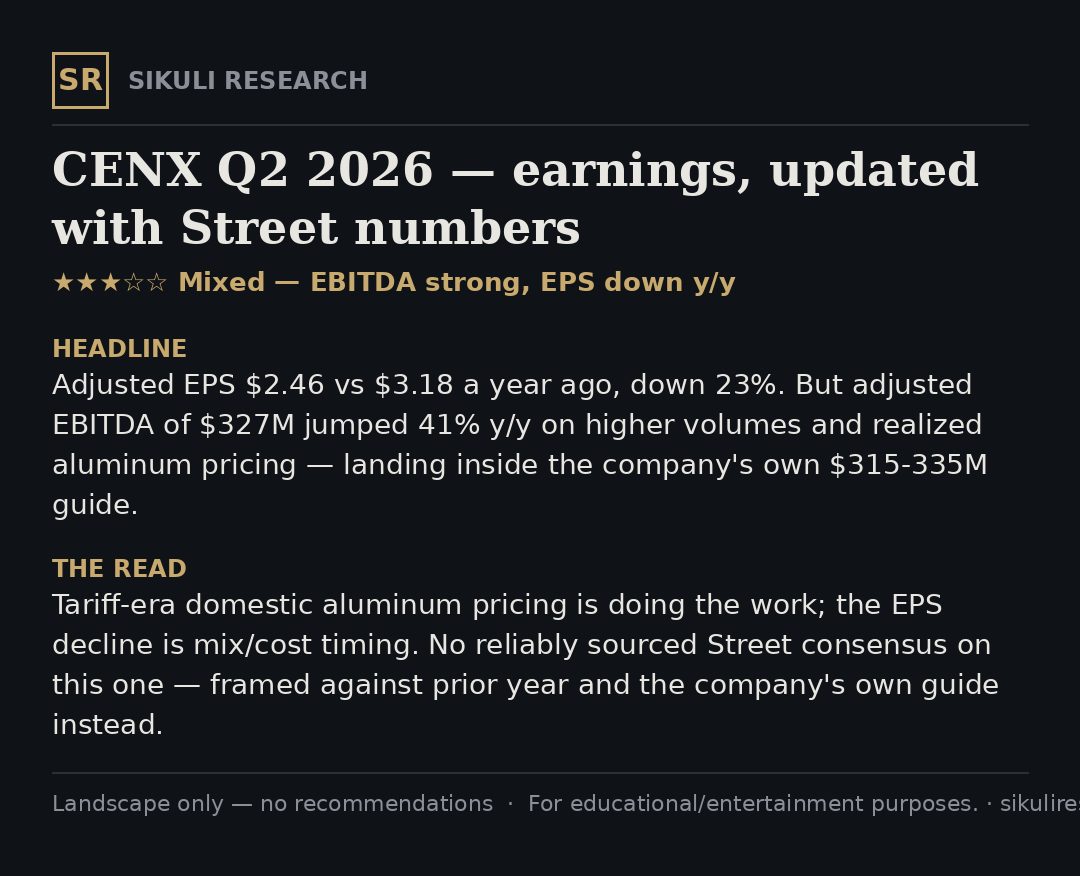
★★★☆☆ Adj EPS $2.46 vs $3.18 a yr ago (-23%); adj EBITDA $327M +41% y/y, inside its own $315-335M guide, on volumes + realized pricing. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
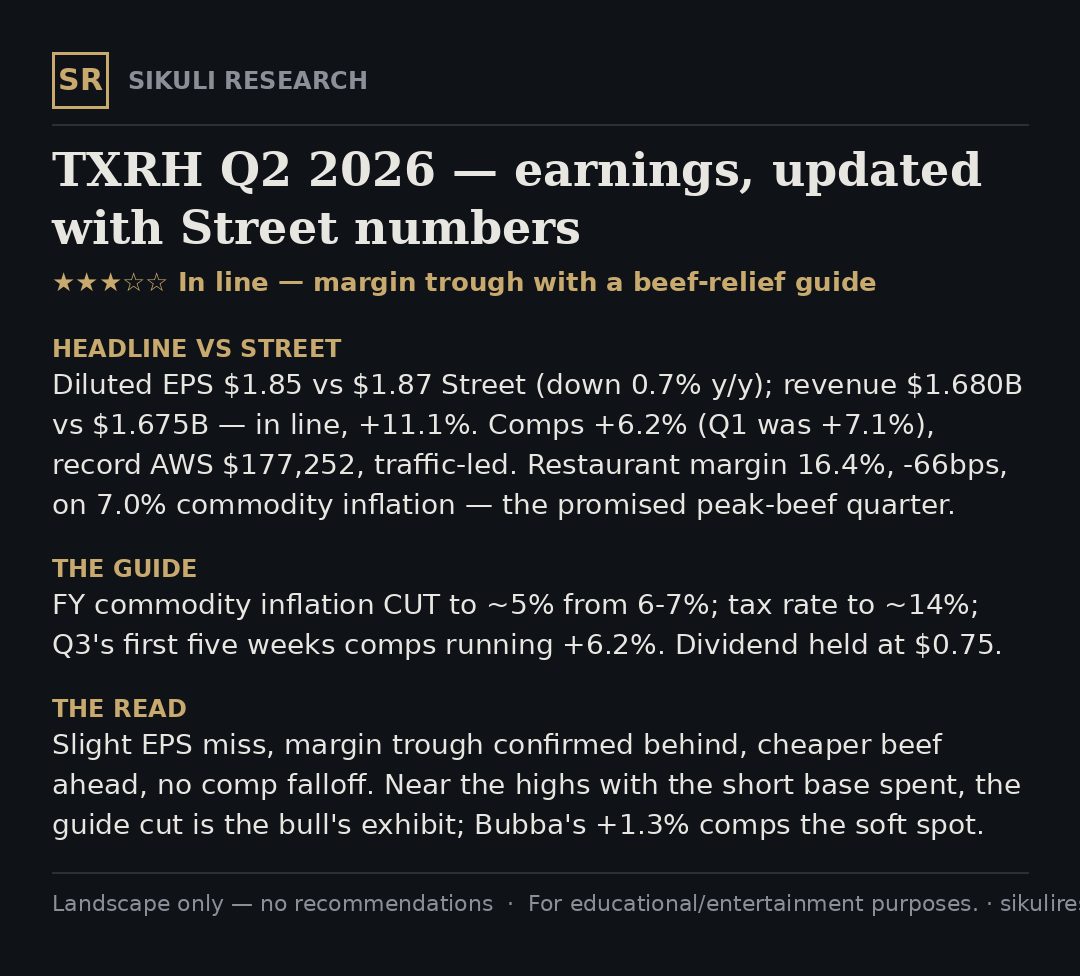
★★★☆☆ EPS $1.85 vs $1.87 Street; rev $1.68B in line (+11%). Comps +6.2%, record AWS. Beef peaked: FY commodity guide CUT to ~5%. Q3 comps +6.2%. Note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
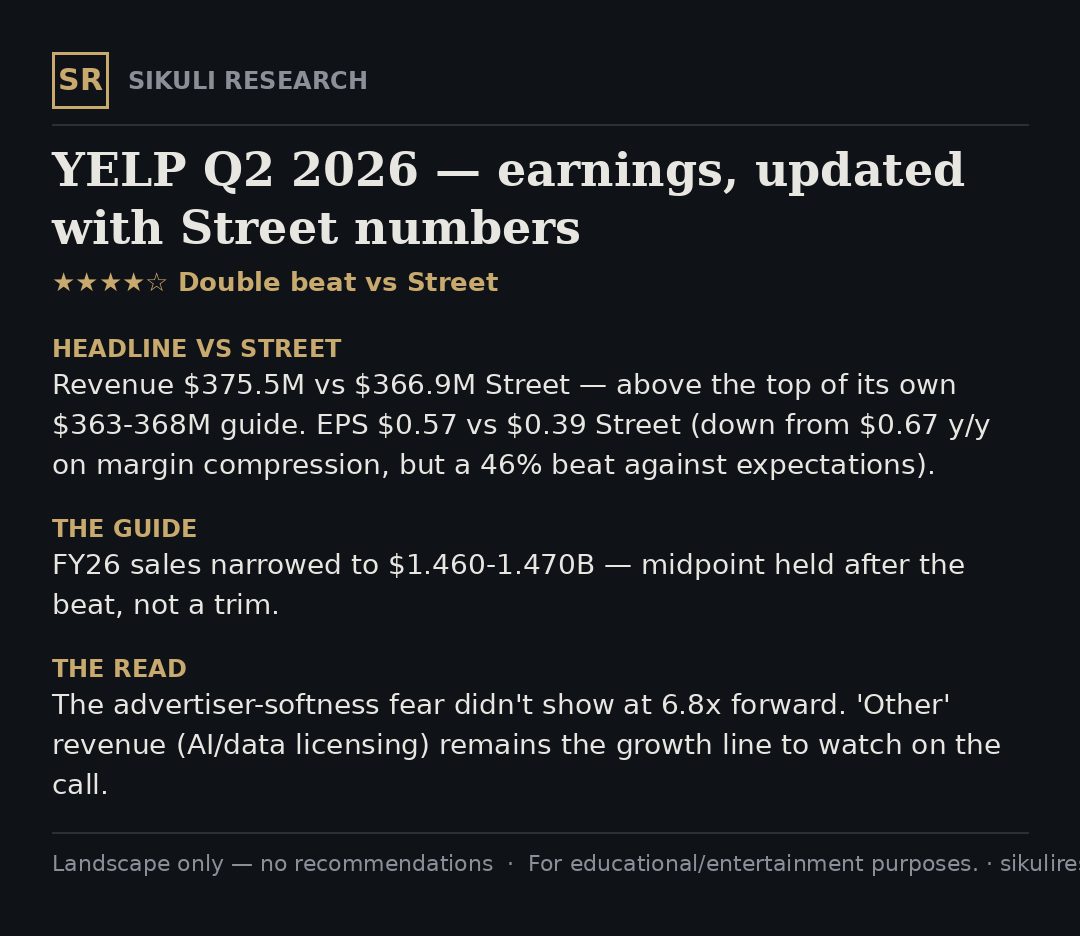
★★★★☆ Rev $375.5M vs $366.9M Street, above its own guide top; EPS $0.57 vs $0.39 Street. FY midpoint held. Ad-softness fear didn't show at 6.8x fwd. Note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
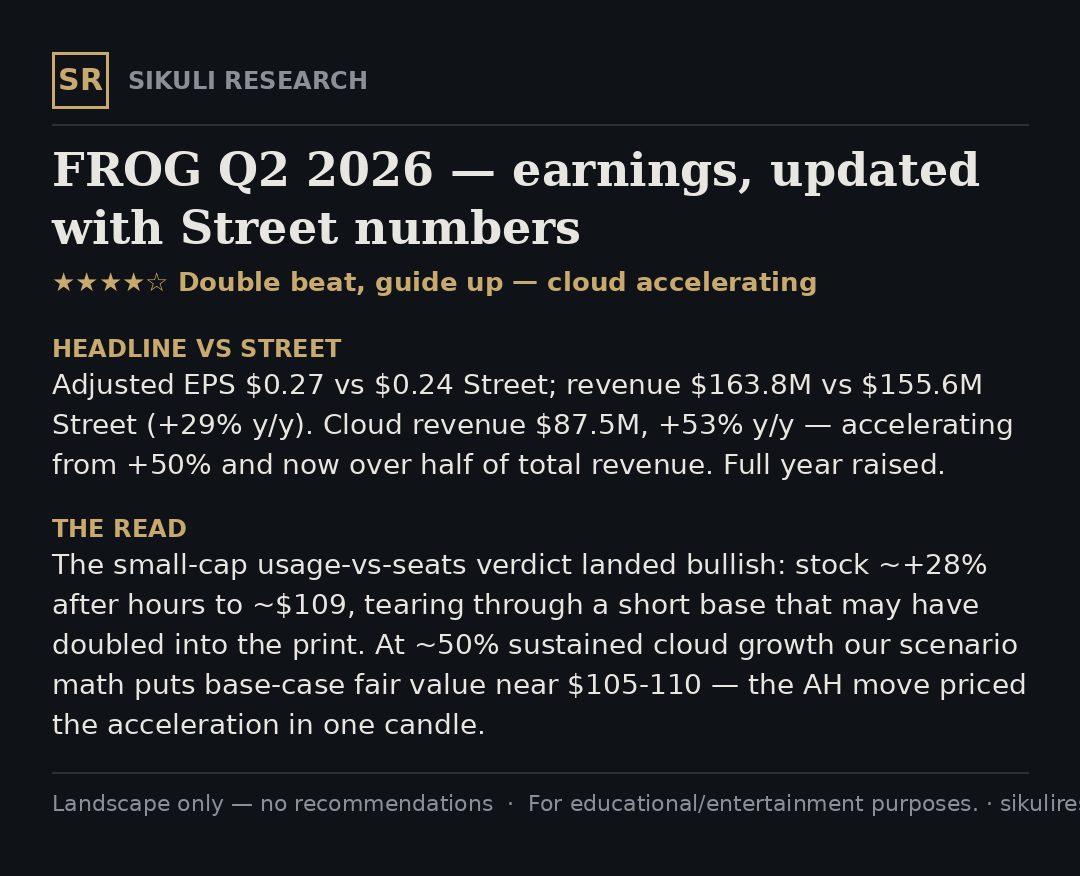
★★★★☆ $0.27 vs $0.24 Street; rev $163.8M vs $155.6M (+29%). Cloud +53%, now >51% of revenue. FY raised. ~+28% AH into a crowded short base. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
★★★★☆ Double Beat, Guide Held. Monster beat on revenue and earnings, with adjusted EPS of $0.60 up 15% year-over-year on strong international growth of 35%. #QQQ #SPX · Sikuli Research — educational, not advice.
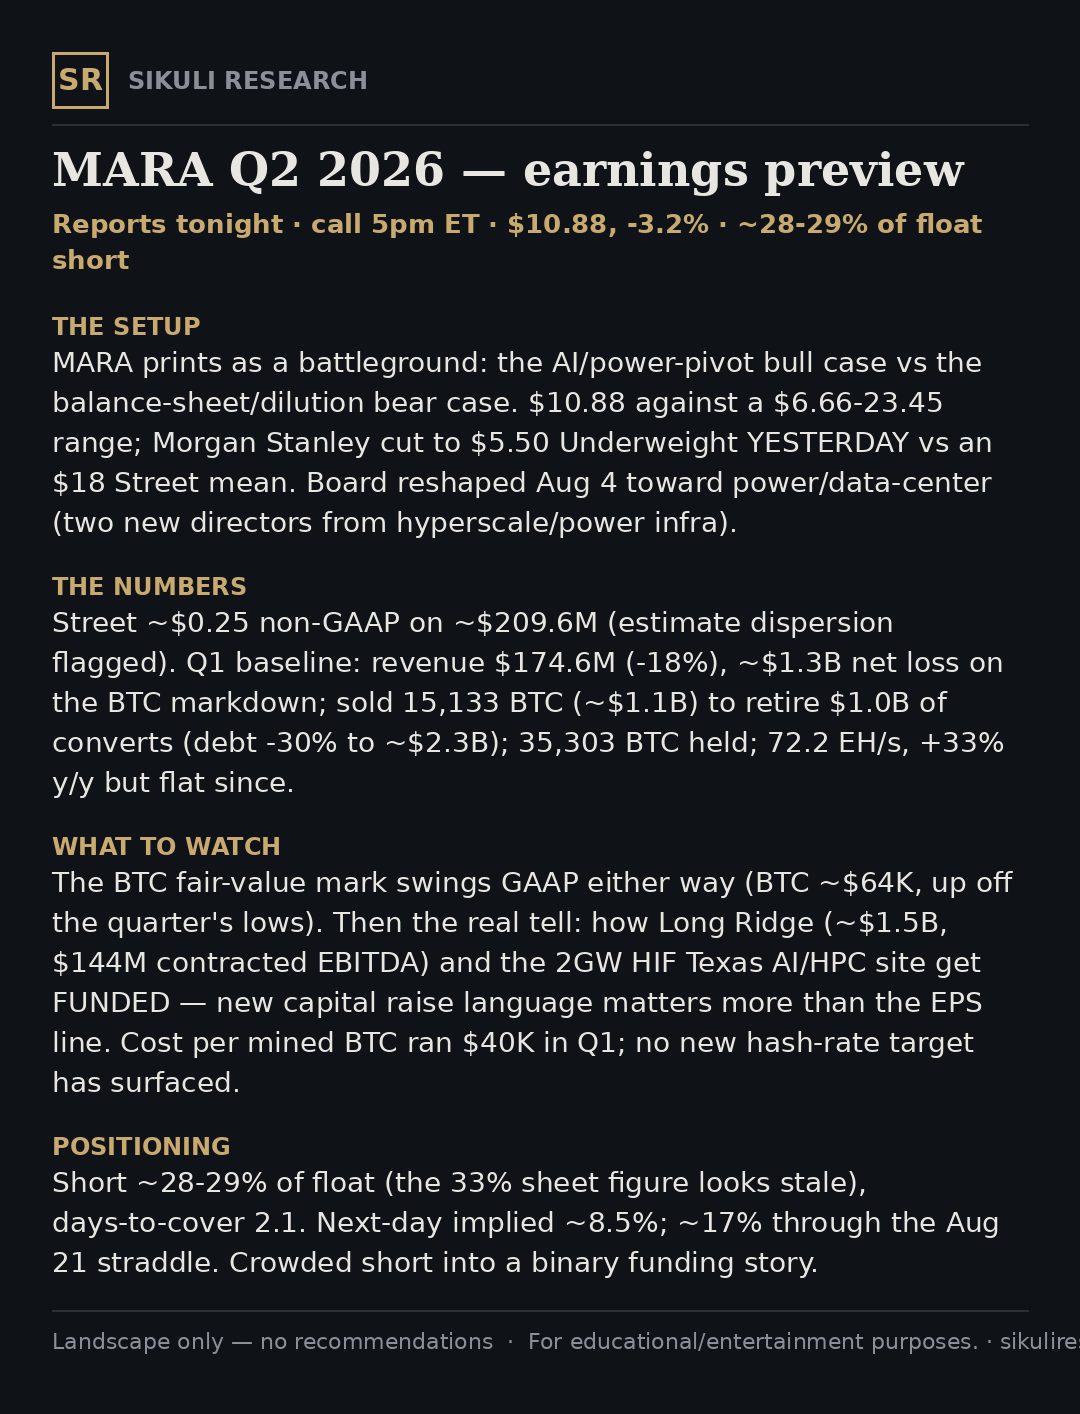
Street ~$0.25 / $210M — but the print is the BTC mark + funding for the Long Ridge/HIF AI-power pivot. MS cut to $5.50 yesterday vs $18 Street mean; ~28% short. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
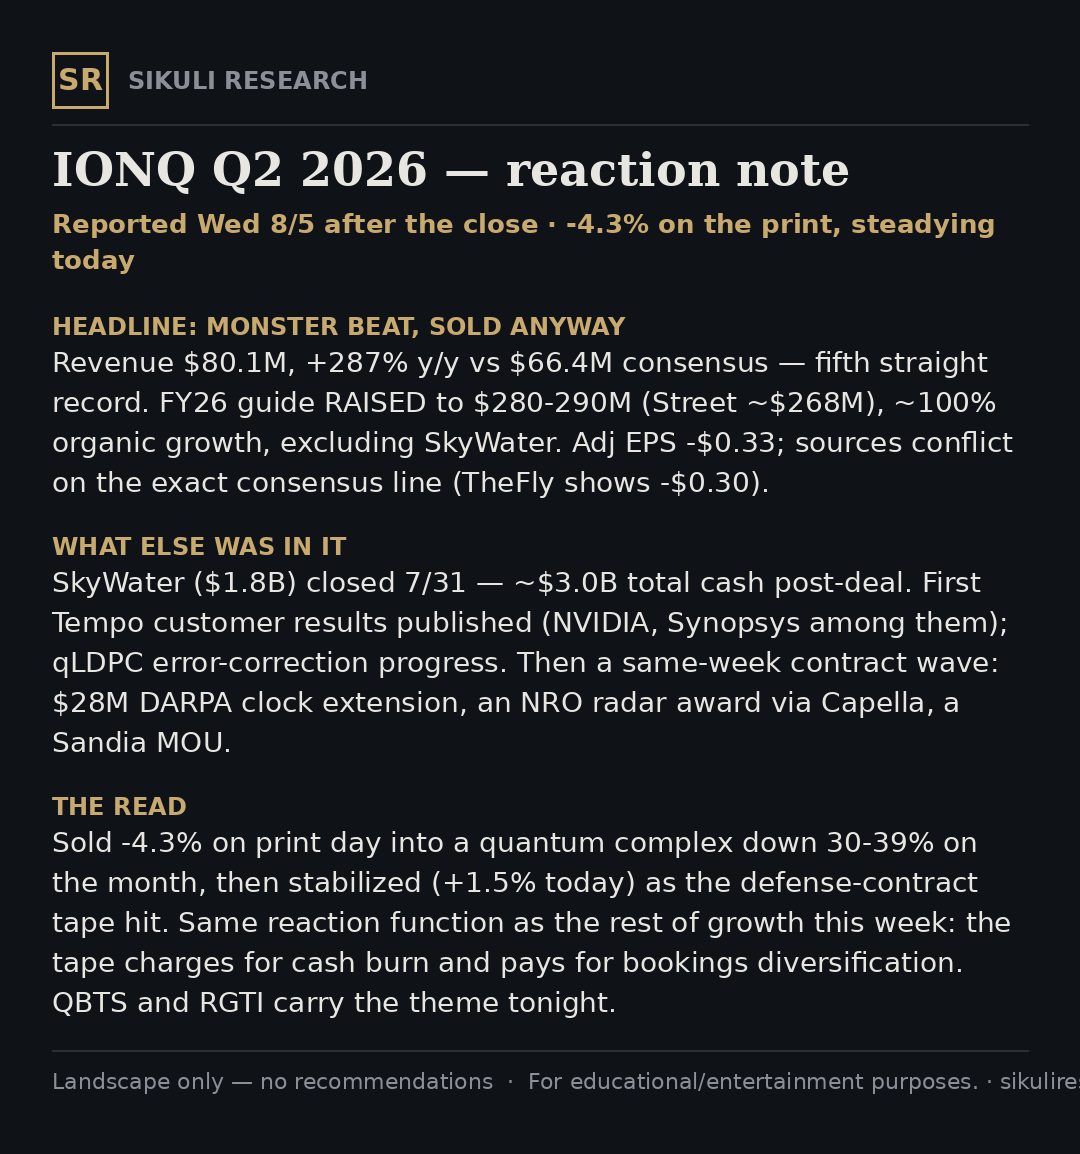
Rev $80.1M +287% vs $66.4M est; FY raised to $280-290M. Sold -4.3% anyway, then steadied on DARPA/NRO wins. QBTS + RGTI carry the quantum theme tonight. Note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
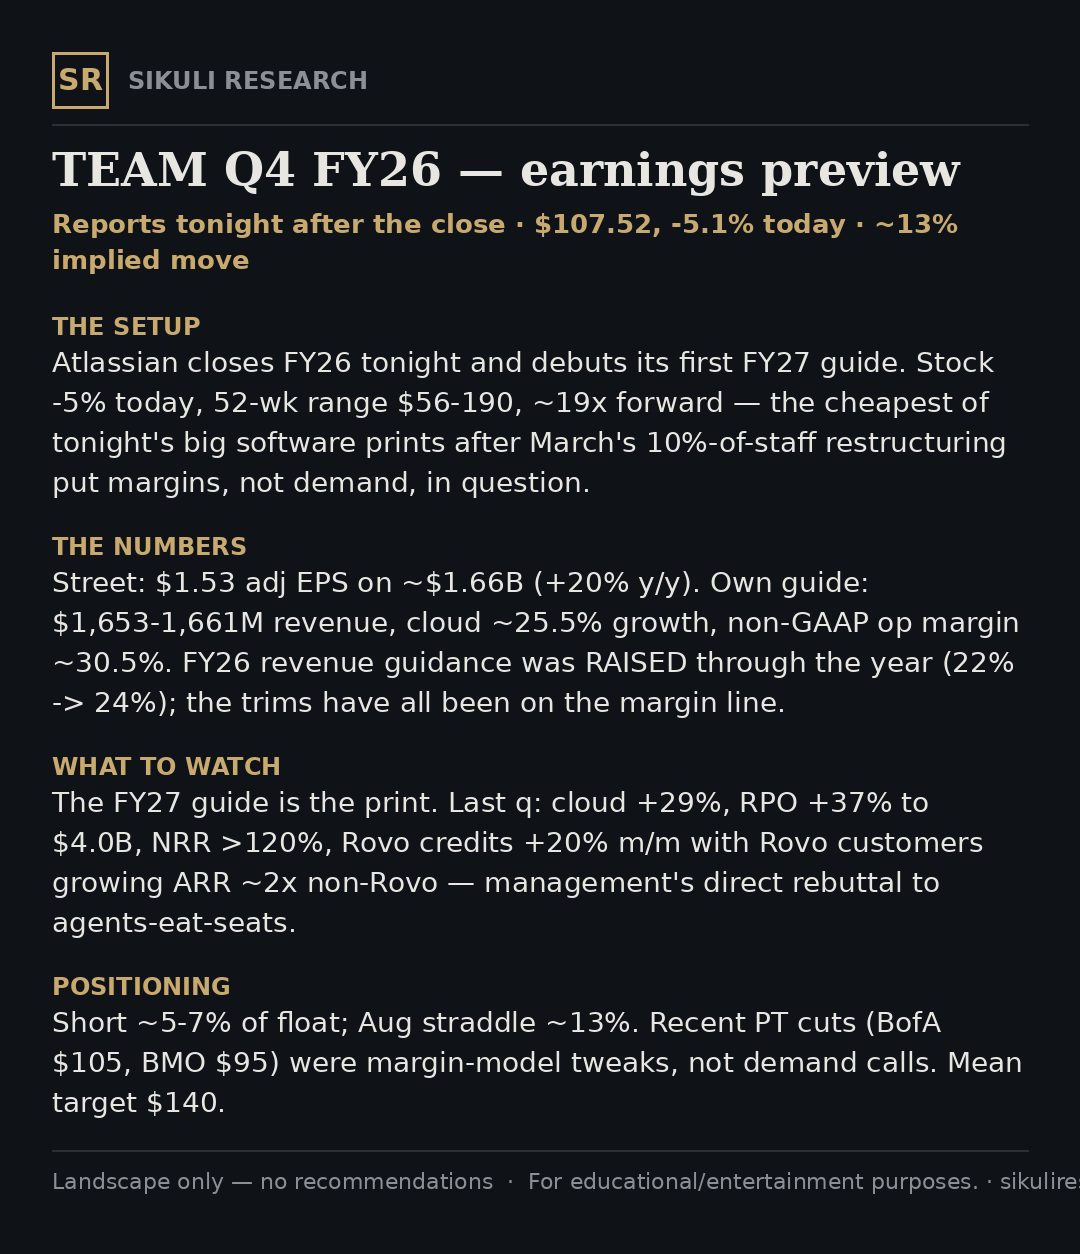
FY27 guide debuts. Street $1.53 / $1.66B (+20%); own guide $1,653-1,661M. NRR >120%, cloud +29% last q. Stock -5% today; ~13% implied move. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
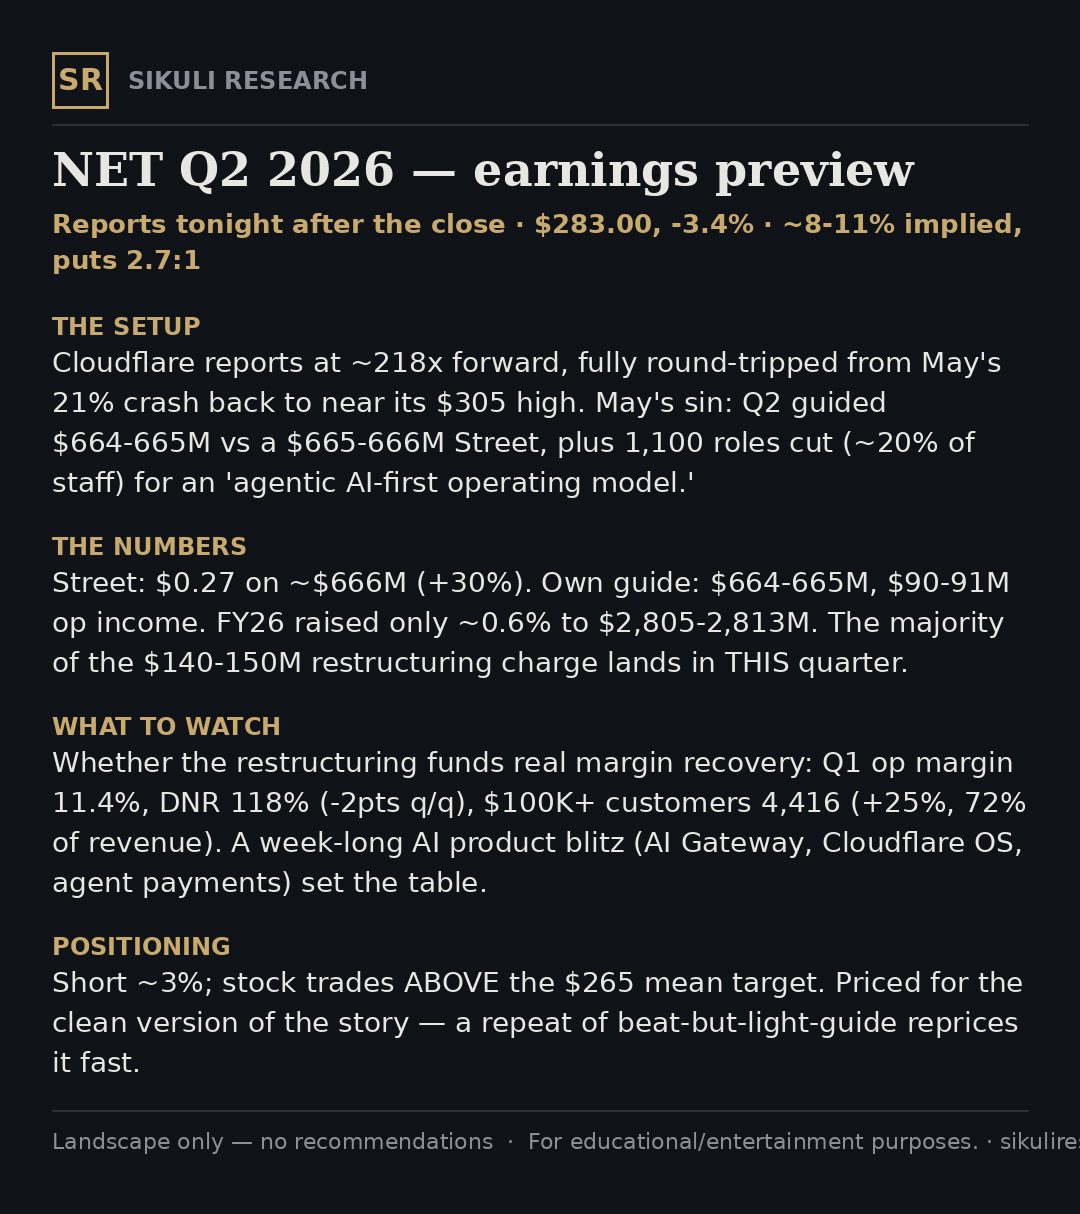
Street $0.27 / ~$666M vs own guide $664-665M. Bulk of the 1,100-role restructuring charge lands in this print. Near highs at ~218x fwd; ~8-11% implied, puts 2.7:1. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
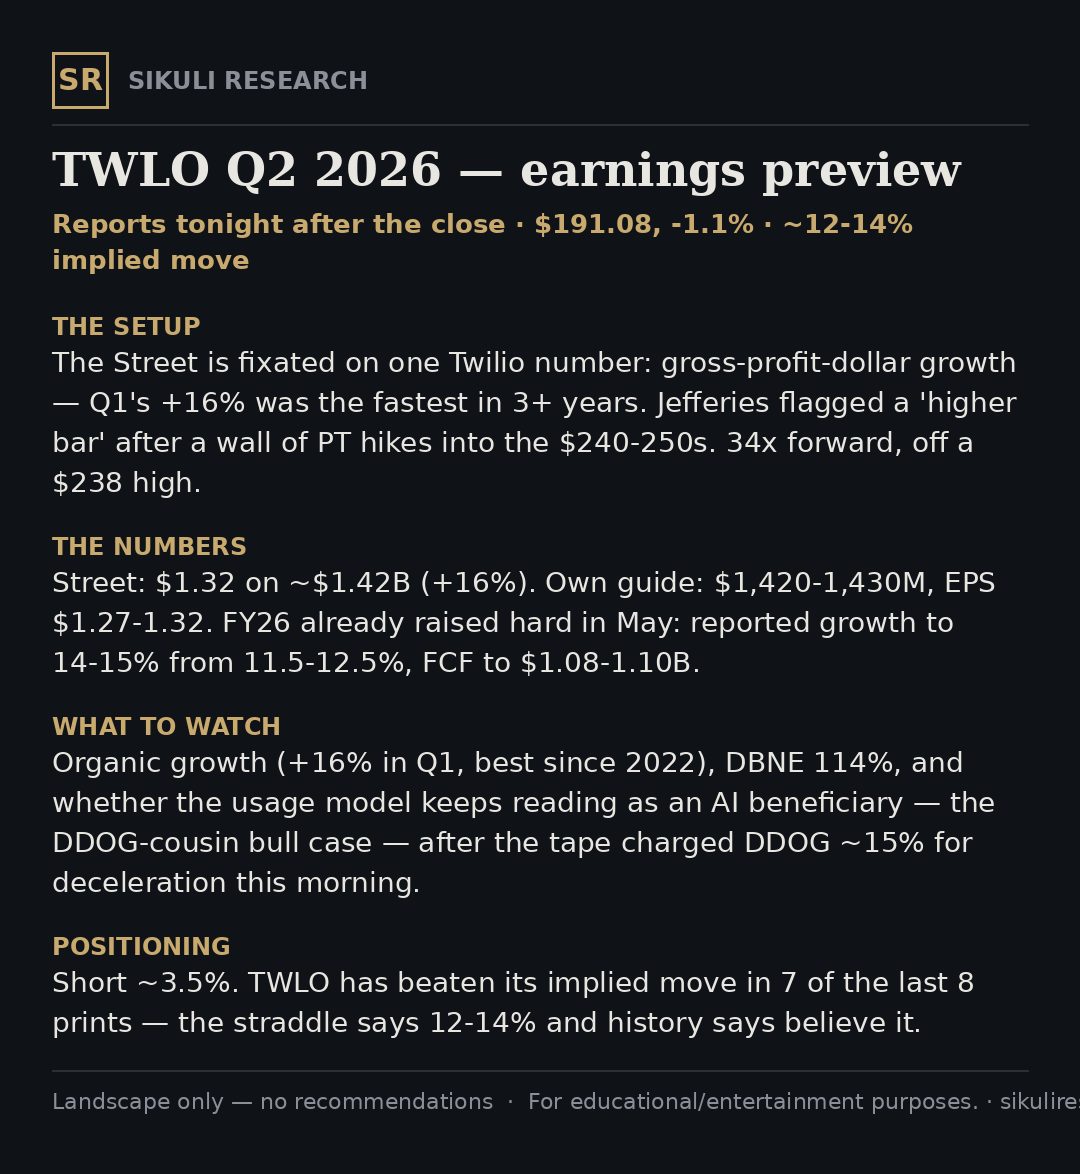
Street $1.32 / $1.42B (+16%). GP-dollar growth is the metric — fastest in 3+ yrs last q, FY already raised once. ~12-14% implied; beat the straddle 7 of last 8. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
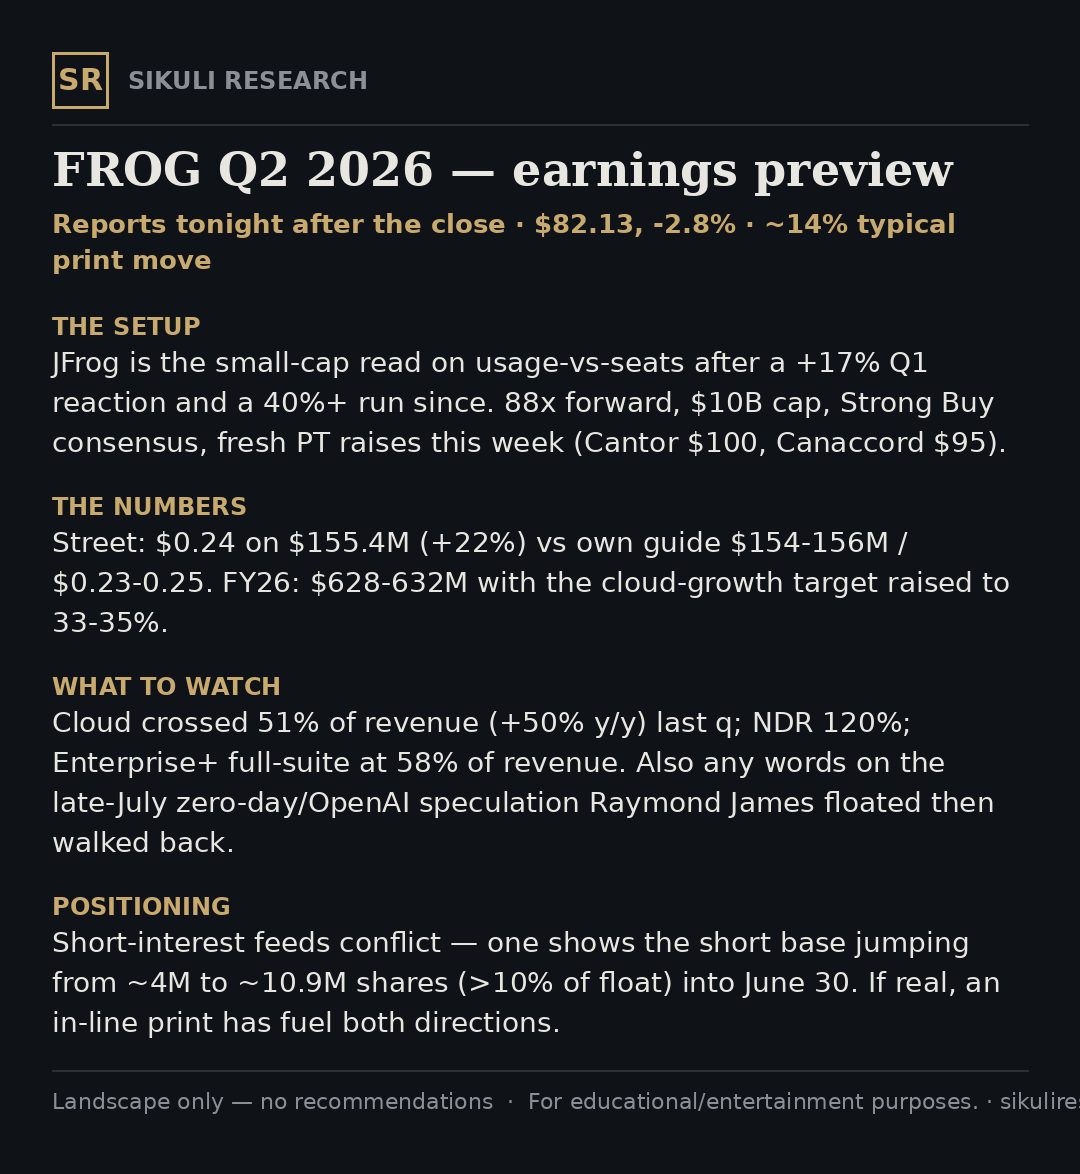
Street $0.24 / $155M (+22%) vs guide $154-156M. Cloud +50%, now >51% of revenue; NDR 120%. ~88x fwd, short base may have doubled into the print. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
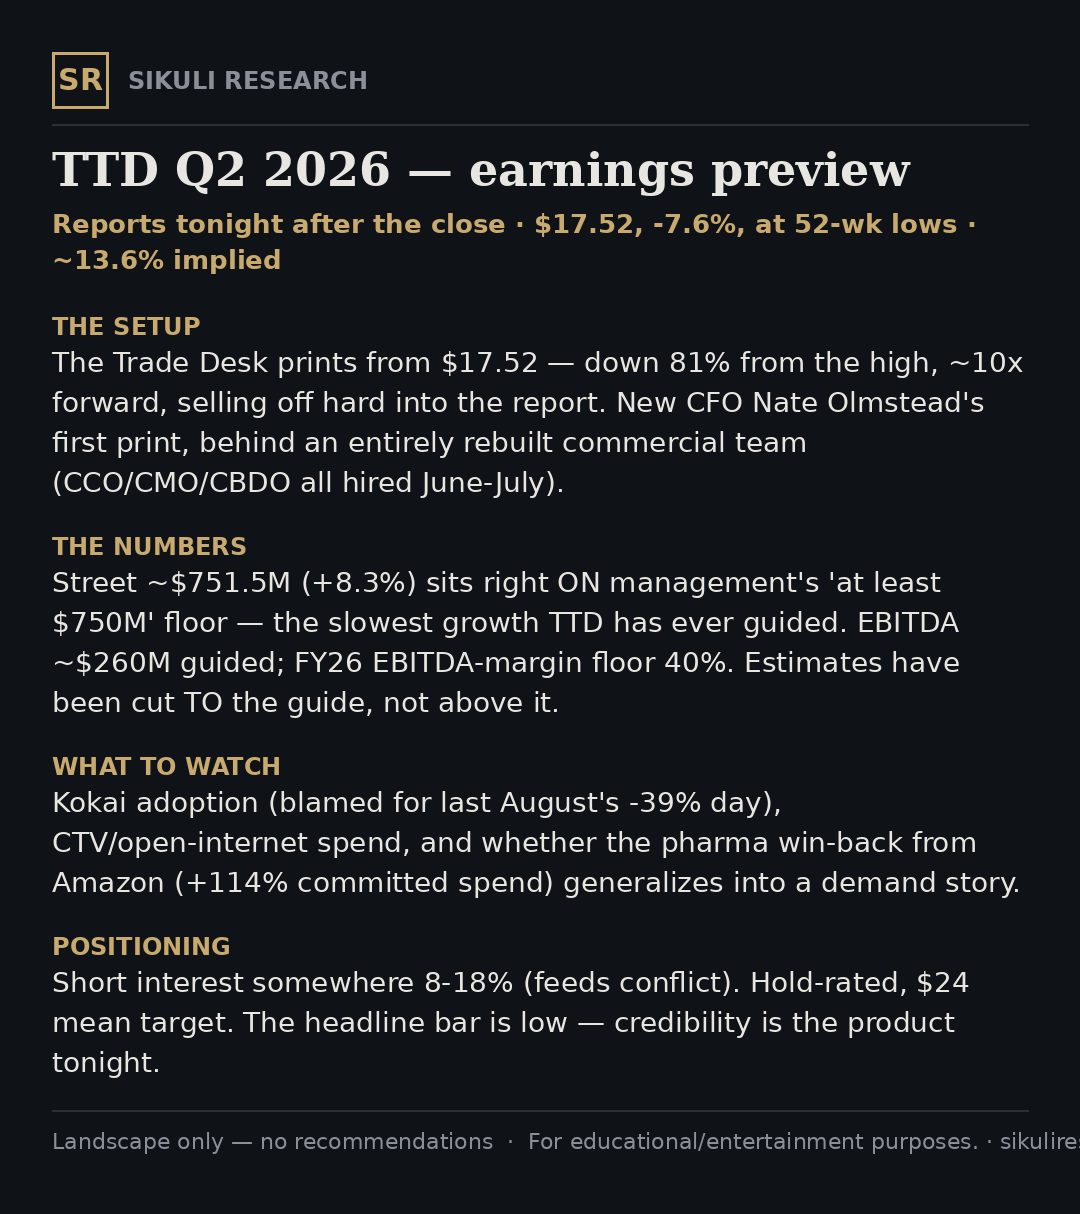
At 52-wk lows, -7.6% today. Street ~$751M sits right on the 'at least $750M' guide floor. New CFO's first print; pharma win-back +114%. ~13.6% implied. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
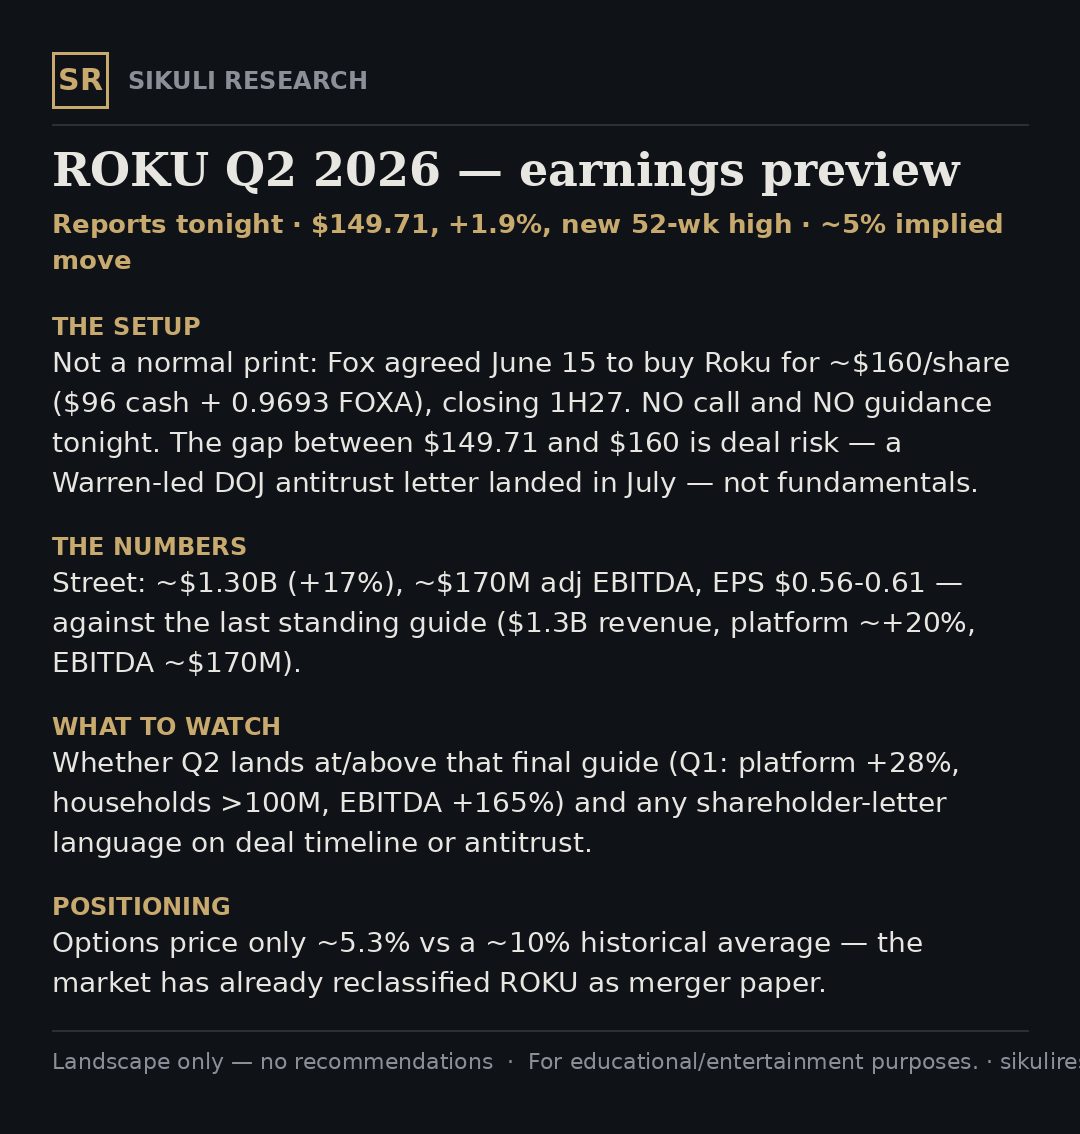
Not a normal print: Fox's ~$160/sh deal means no call, no guide. Street $1.30B (+17%), ~$170M EBITDA. At new highs, trading as merger paper — ~5% implied. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
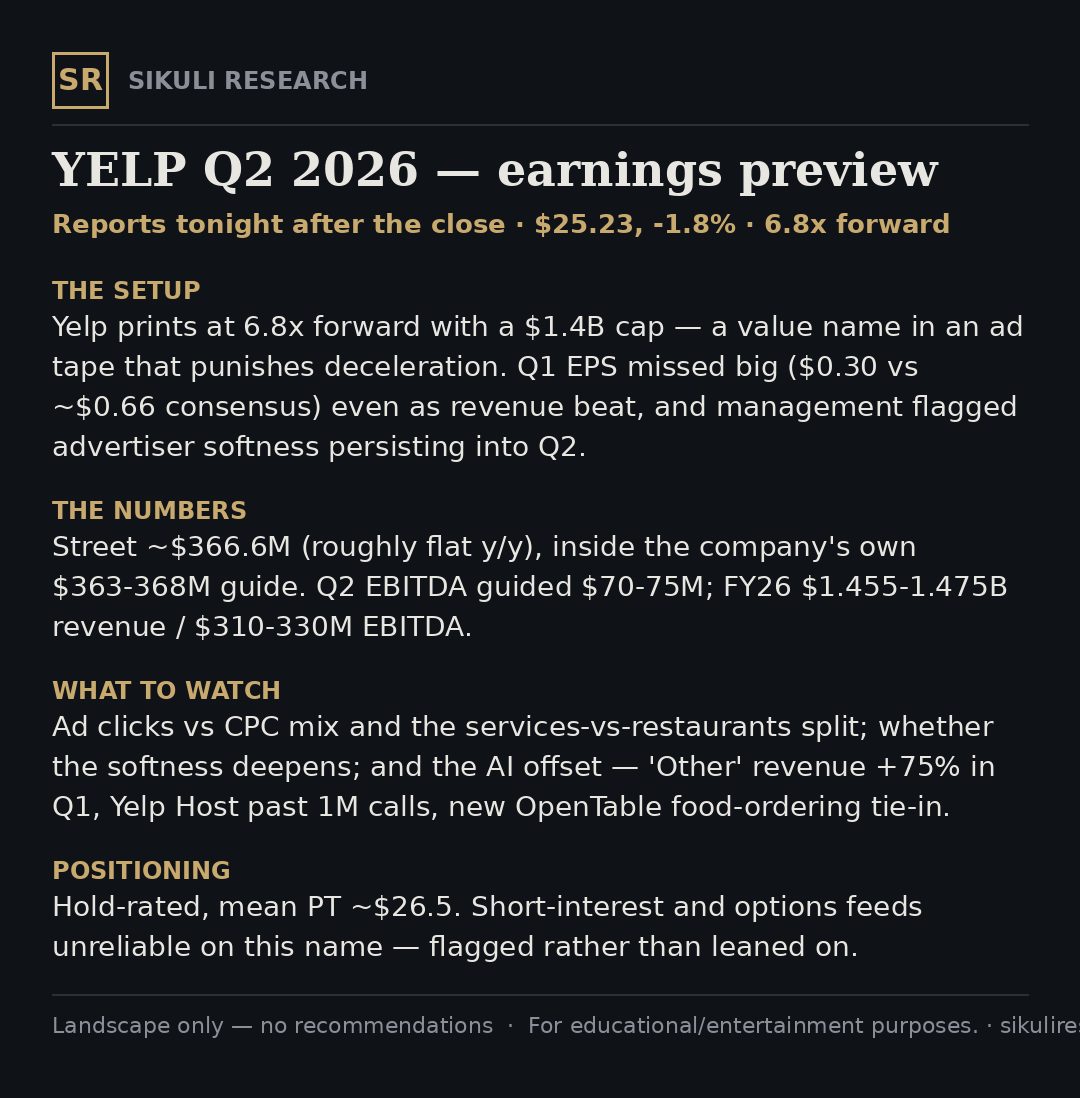
Street ~$367M (flat) inside the $363-368M guide. Ad softness vs the AI 'Other' line (+75%) is the tension. 6.8x fwd, $1.4B cap. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
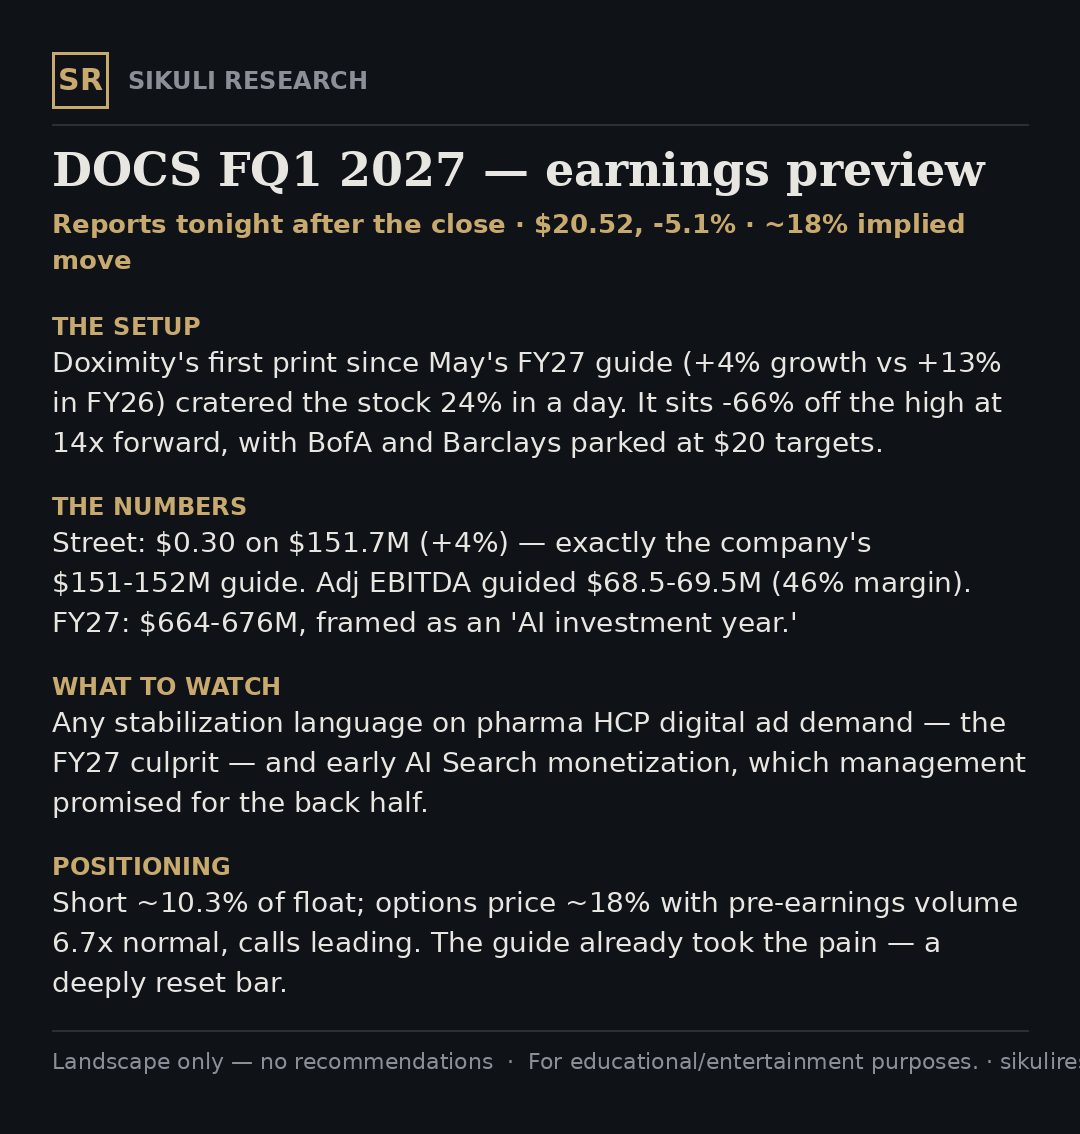
First print since May's -24% guide crash. Street $151.7M (+4%) = the guide. Pharma HCP ad demand + AI Search traction are the tells. ~18% implied, ~10% short. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
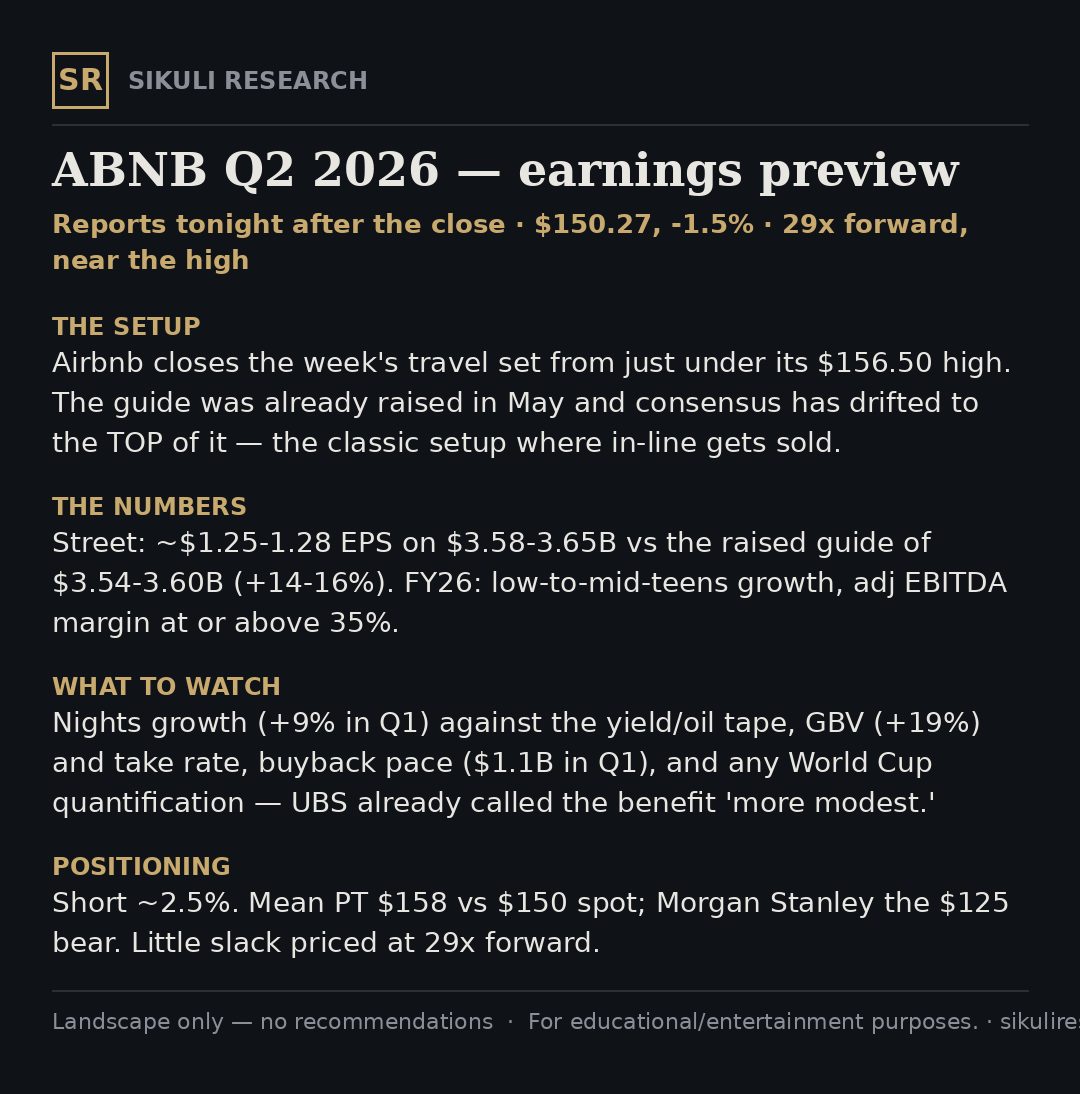
Street $3.6B sits at the TOP of the raised $3.54-3.60B guide. Nights +9%, 35%+ FY EBITDA-margin target, $1.1B/qtr buyback. 29x fwd near the high. Full preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
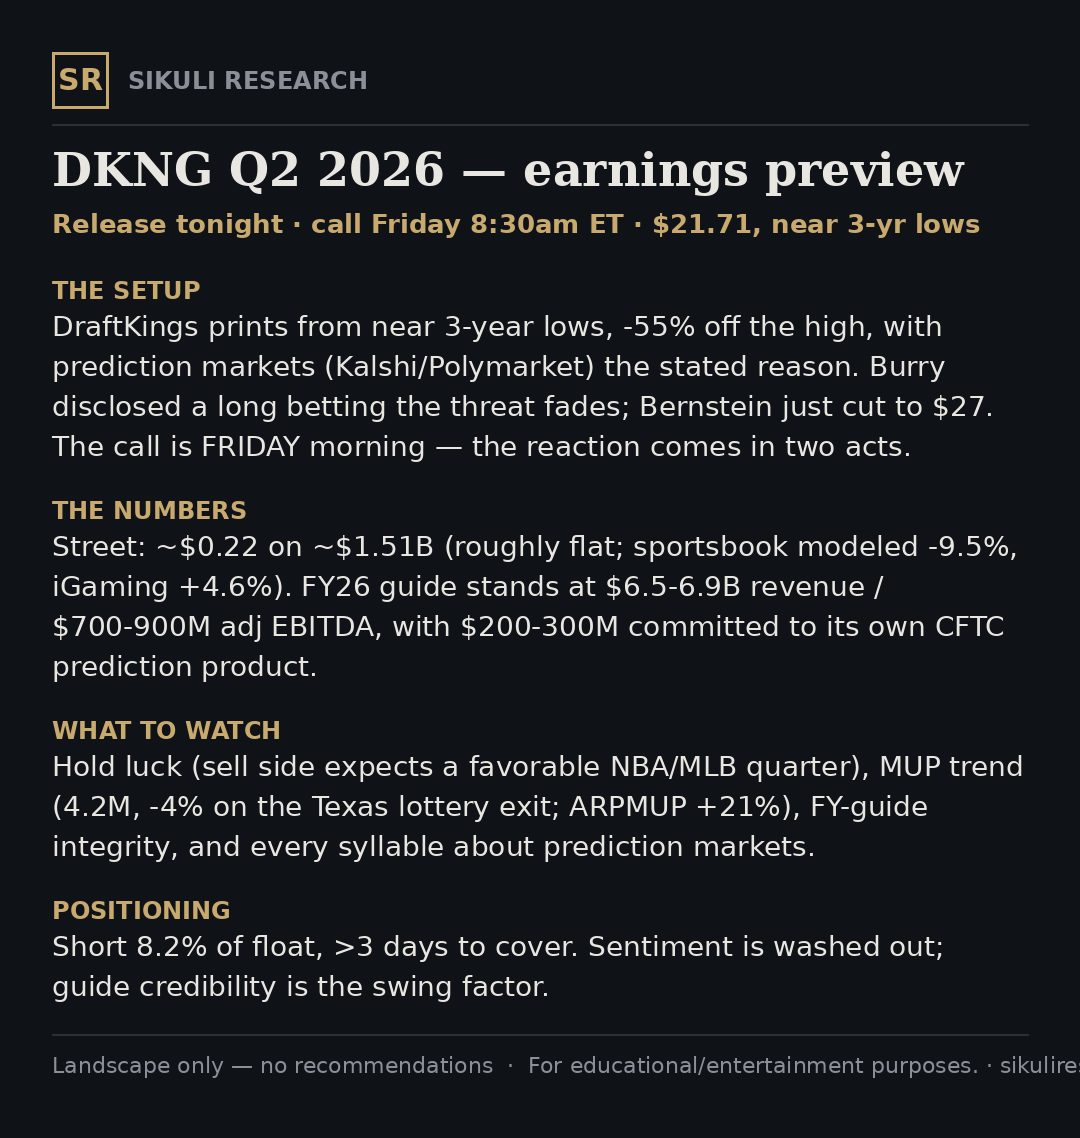
Street $0.22 / $1.51B. FY guide $6.5-6.9B / $700-900M EBITDA. Prediction-market fear has it near 3-yr lows; favorable NBA/MLB hold expected. 8% short. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
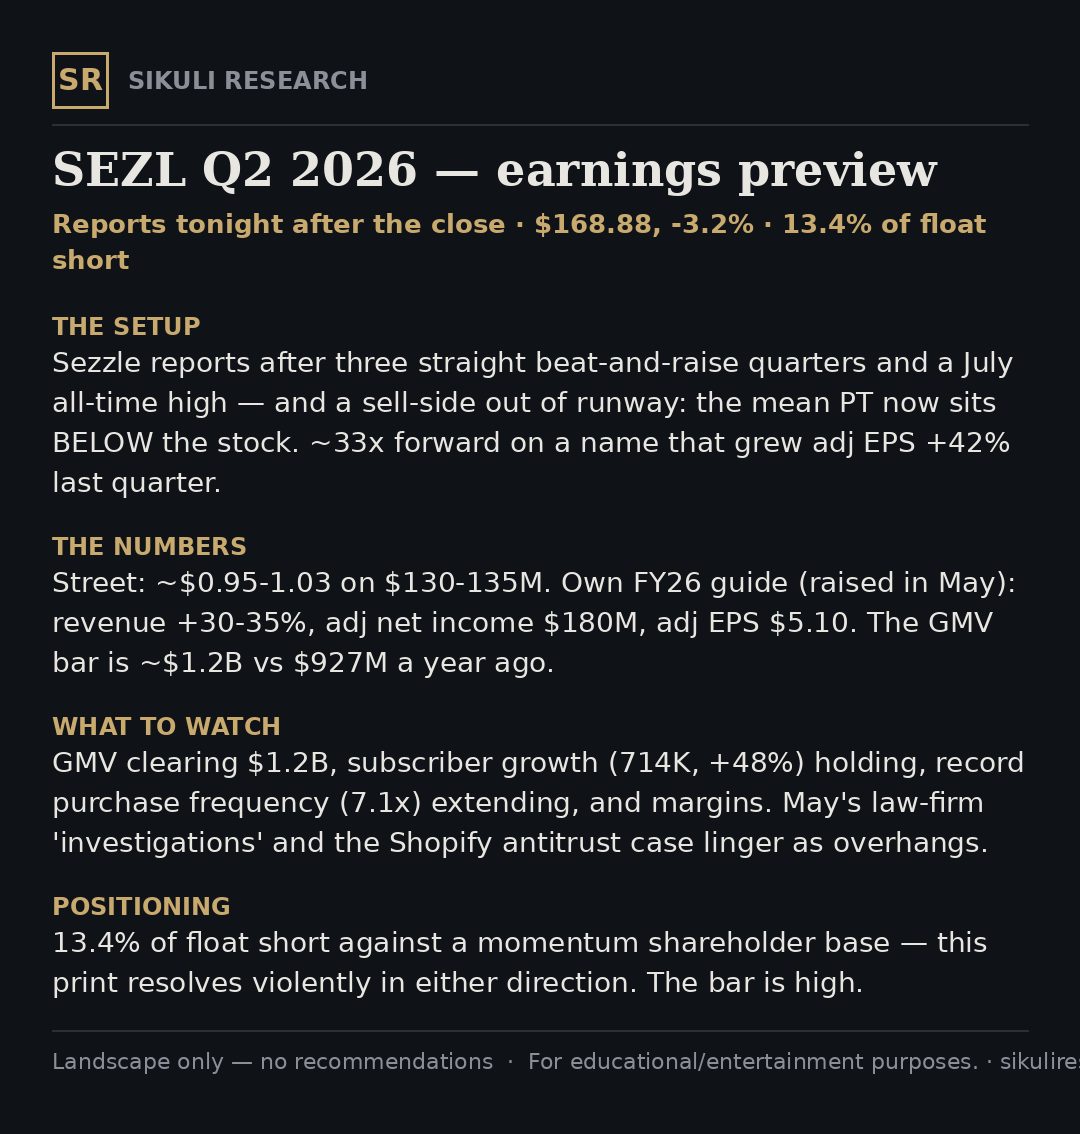
Street ~$1.00 / $130-135M; GMV bar ~$1.2B (+30%). Three straight beat-and-raises, 13% short, mean PT now BELOW the stock. Crowded both ways. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
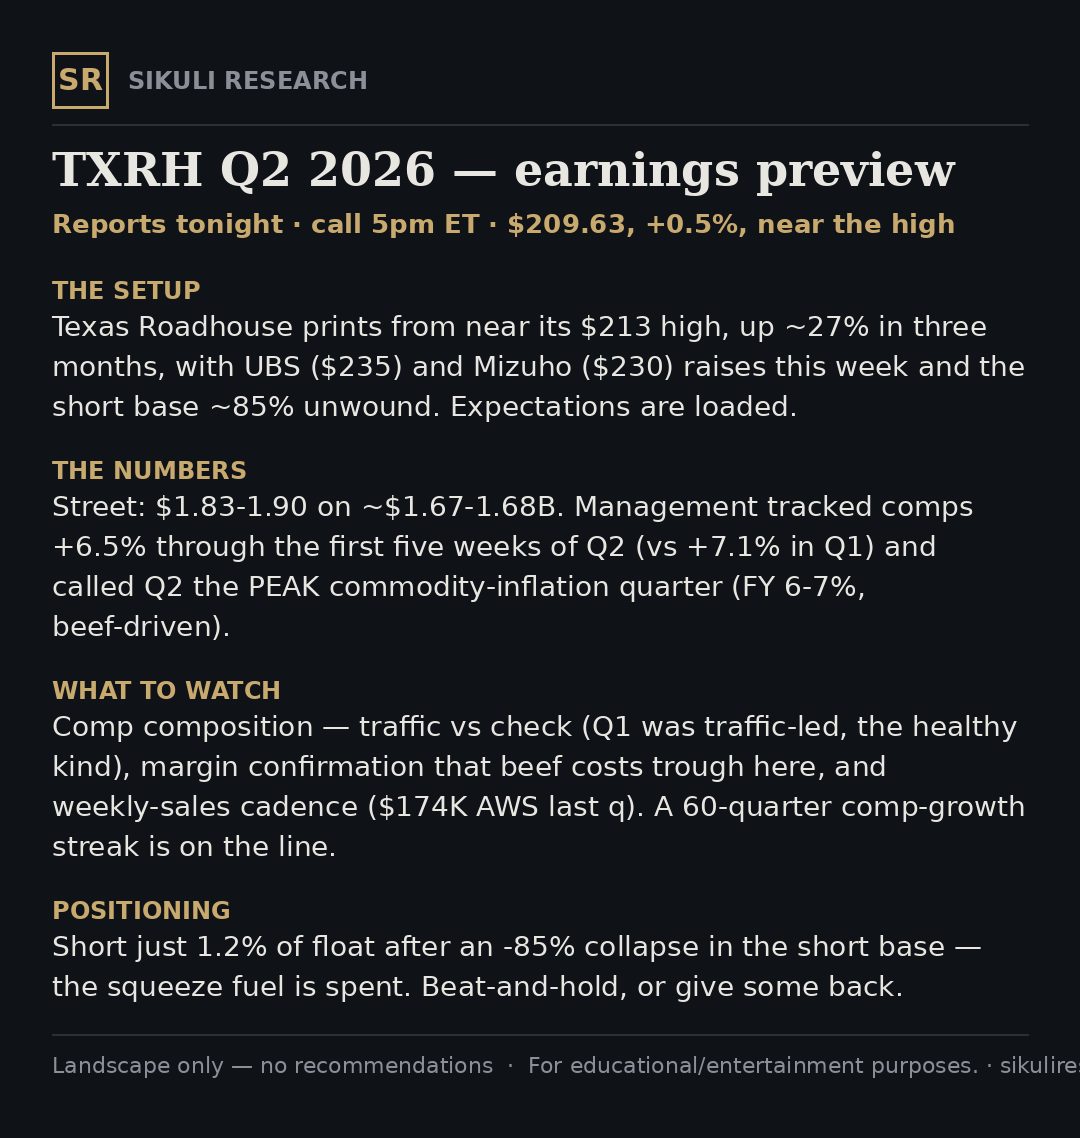
Street $1.83-1.90 / $1.67B. Comps tracking +6.5%; mgmt called Q2 the PEAK beef-inflation quarter. Near highs, 60-quarter comp streak on the line. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
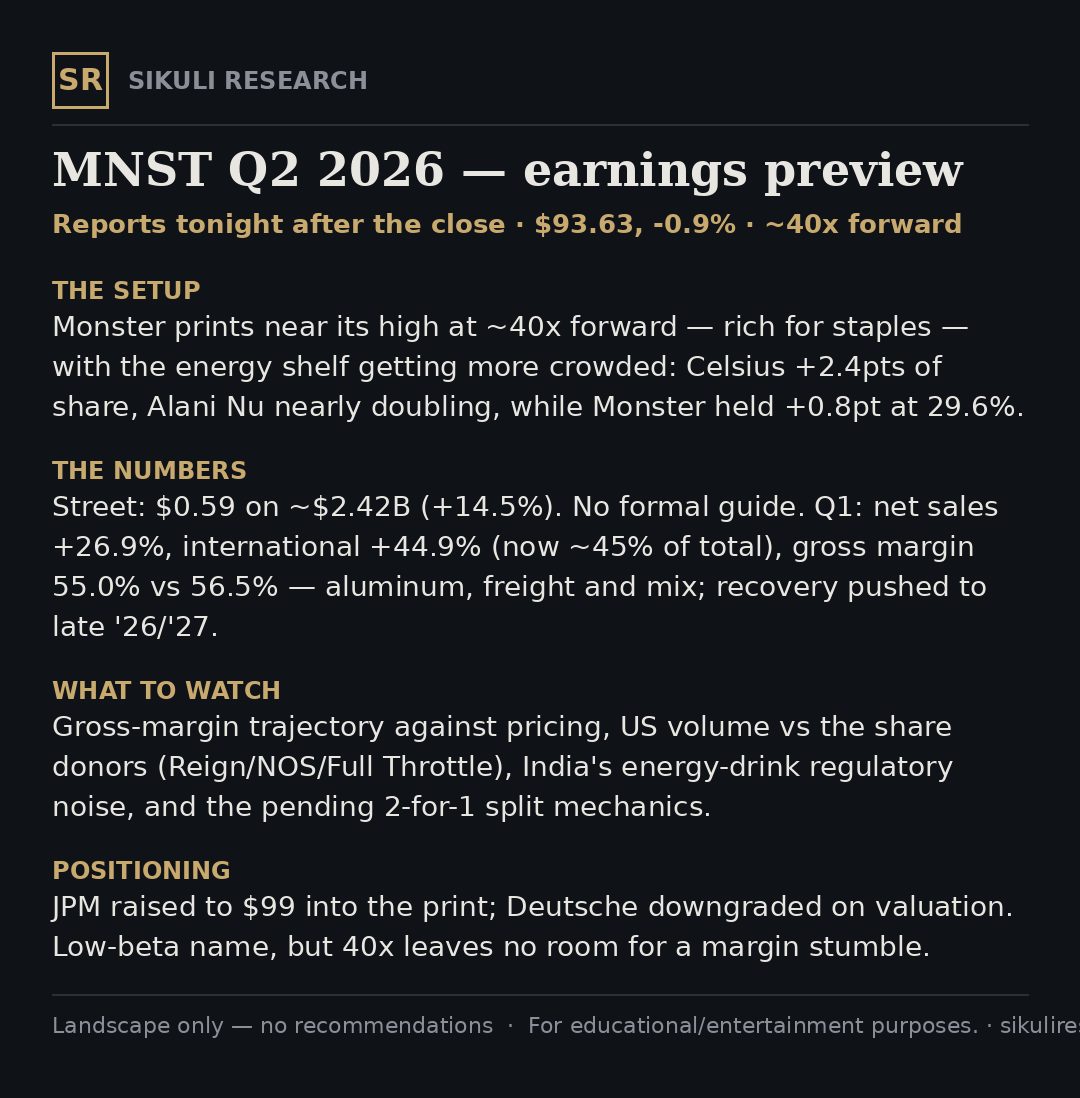
Street $0.59 / $2.42B (+14.5%). Margin recovery vs aluminum/freight and CELH/Alani share pressure are the swings. ~40x fwd near highs; split pending. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
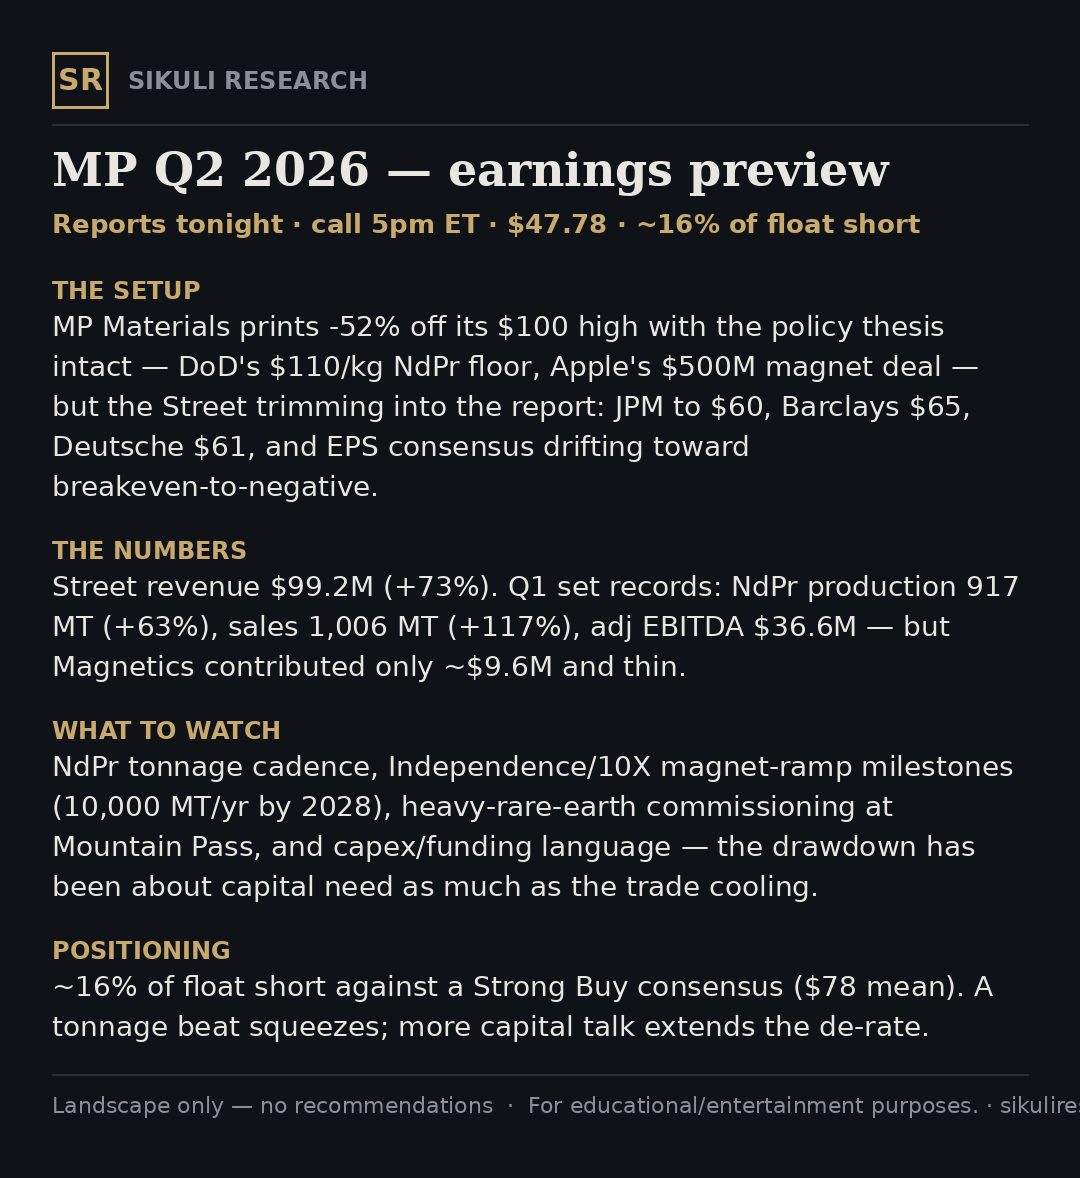
Street rev $99M (+73%); EPS consensus slipping to breakeven. NdPr tonnage + magnet ramp ARE the print. DoD floor intact, ~16% short, -52% off highs. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
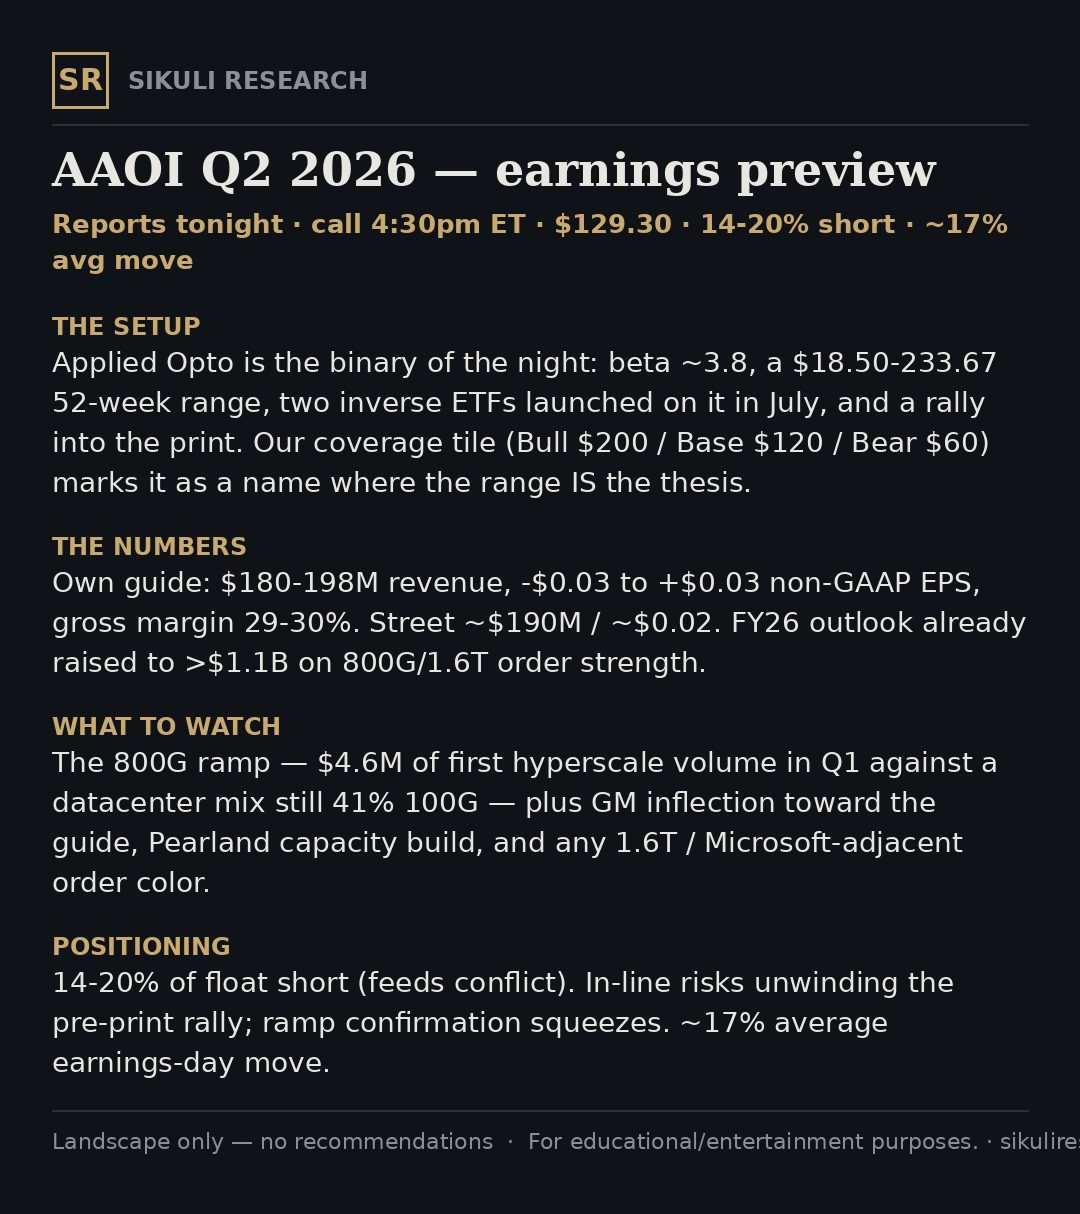
Guide $180-198M / -$0.03 to +$0.03; Street ~$190M. The 800G ramp ($4.6M first hyperscale volume in Q1) is the whole story. 14-20% short, ~17% avg print move — binary. Preview on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
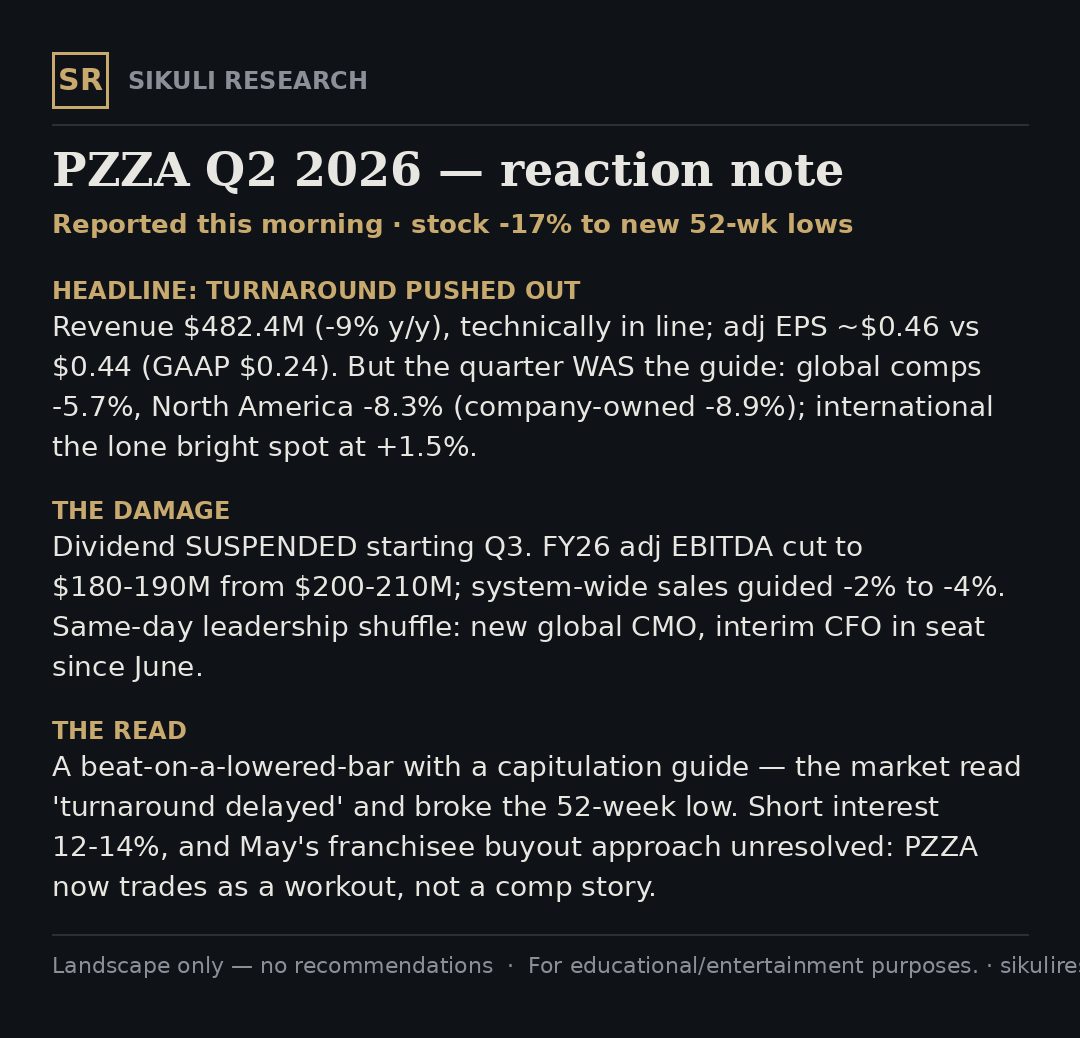
Guide-down quarter: NA comps -8.3%, dividend SUSPENDED, FY EBITDA cut to $180-190M from $200-210M. Stock -17% to new lows — trades as a workout now. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
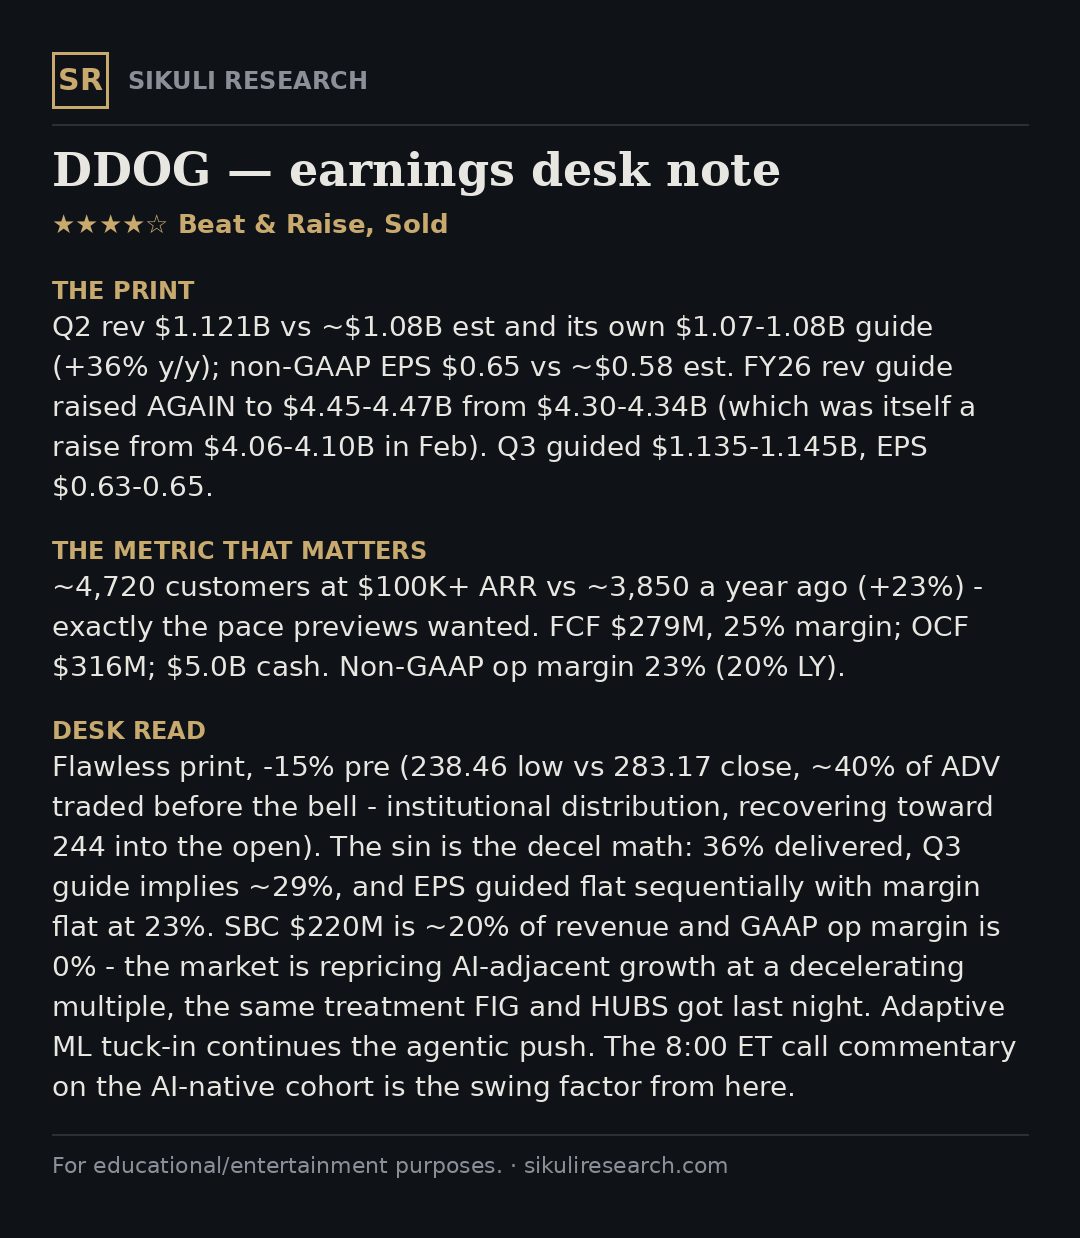
★★★★☆ Beat & Raise, Sold. Rev $1.12B +36% vs $1.08B est, EPS $0.65 vs $0.58, FY raised a 3rd time, 4,720 $100K+ customers — and it's -15% pre. 36%->~29% guided decel is the sin. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
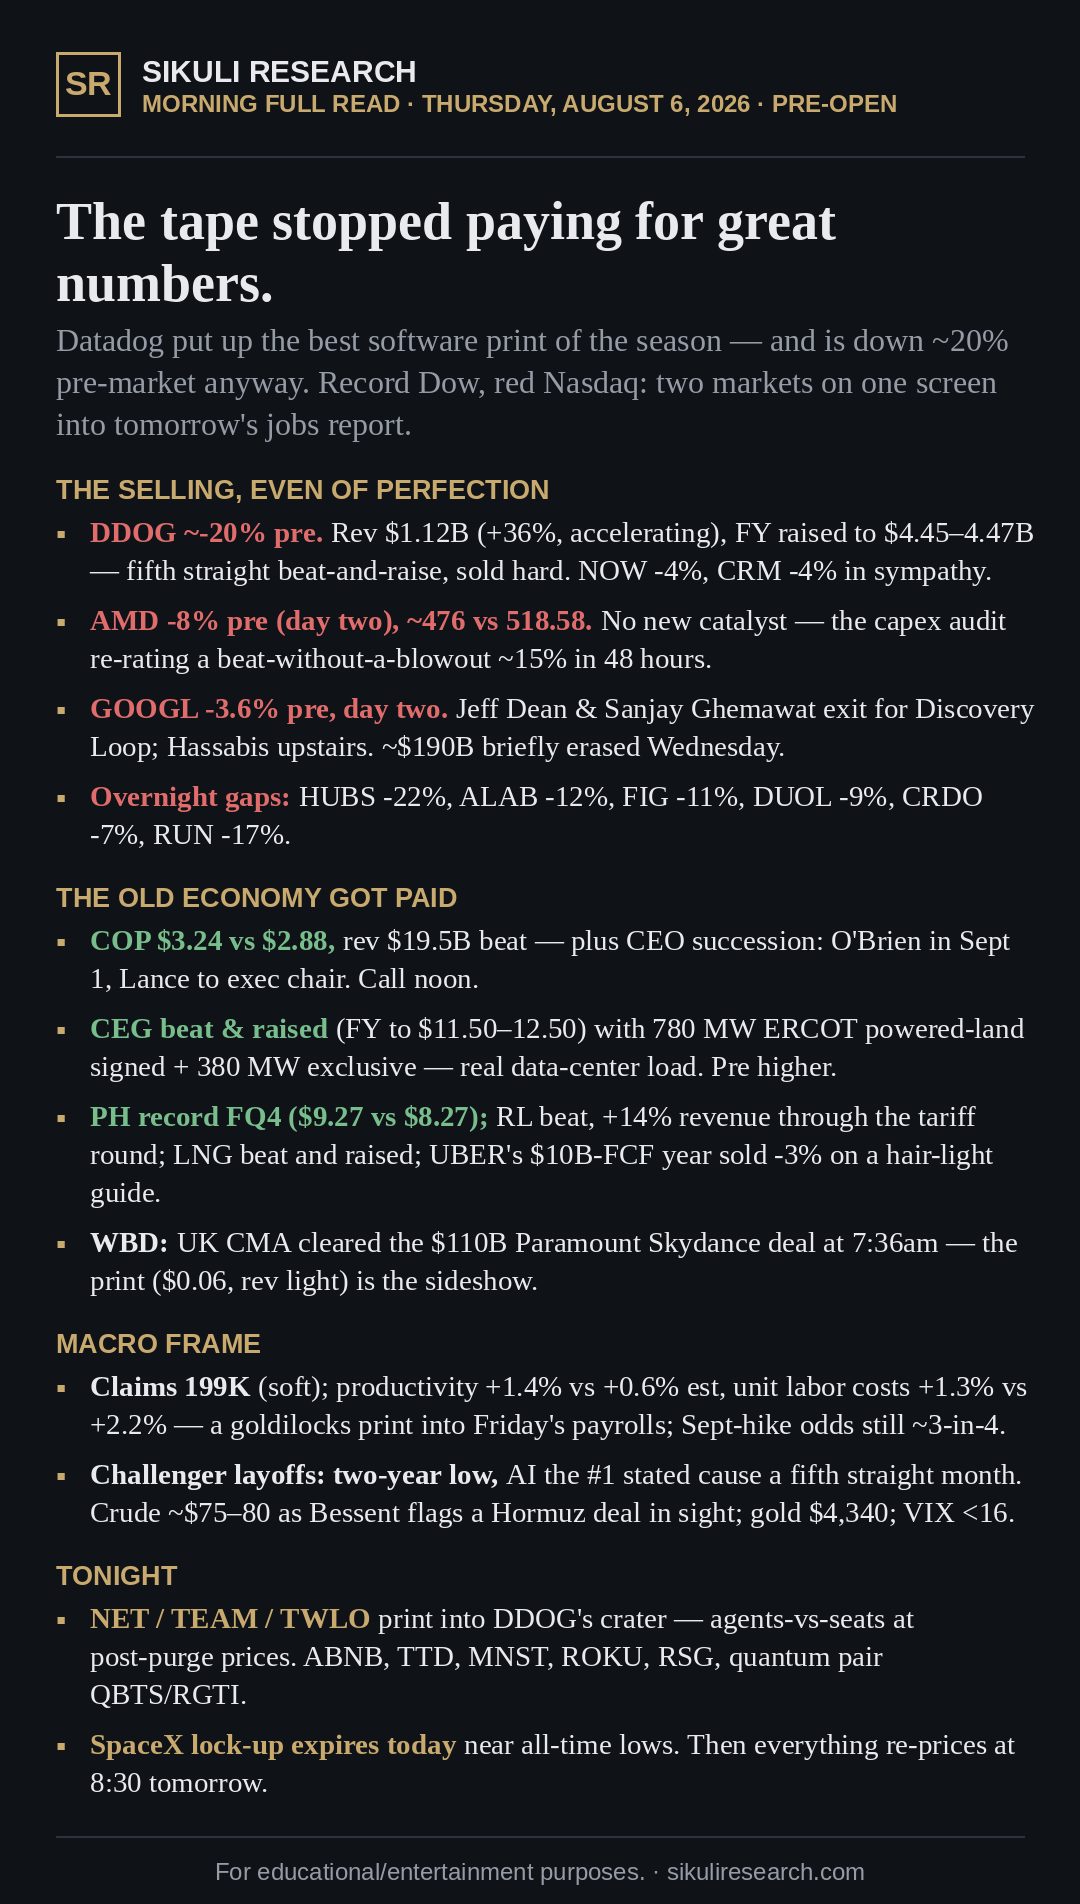
The tape stopped paying for great numbers: DDOG ~-20% pre on a flawless beat-and-raise, AMD day two, GOOGL's brain drain — while COP, CEG and the old economy print record Dow highs. Jobs report tomorrow. Full read at Sikuli Research (link in bio)
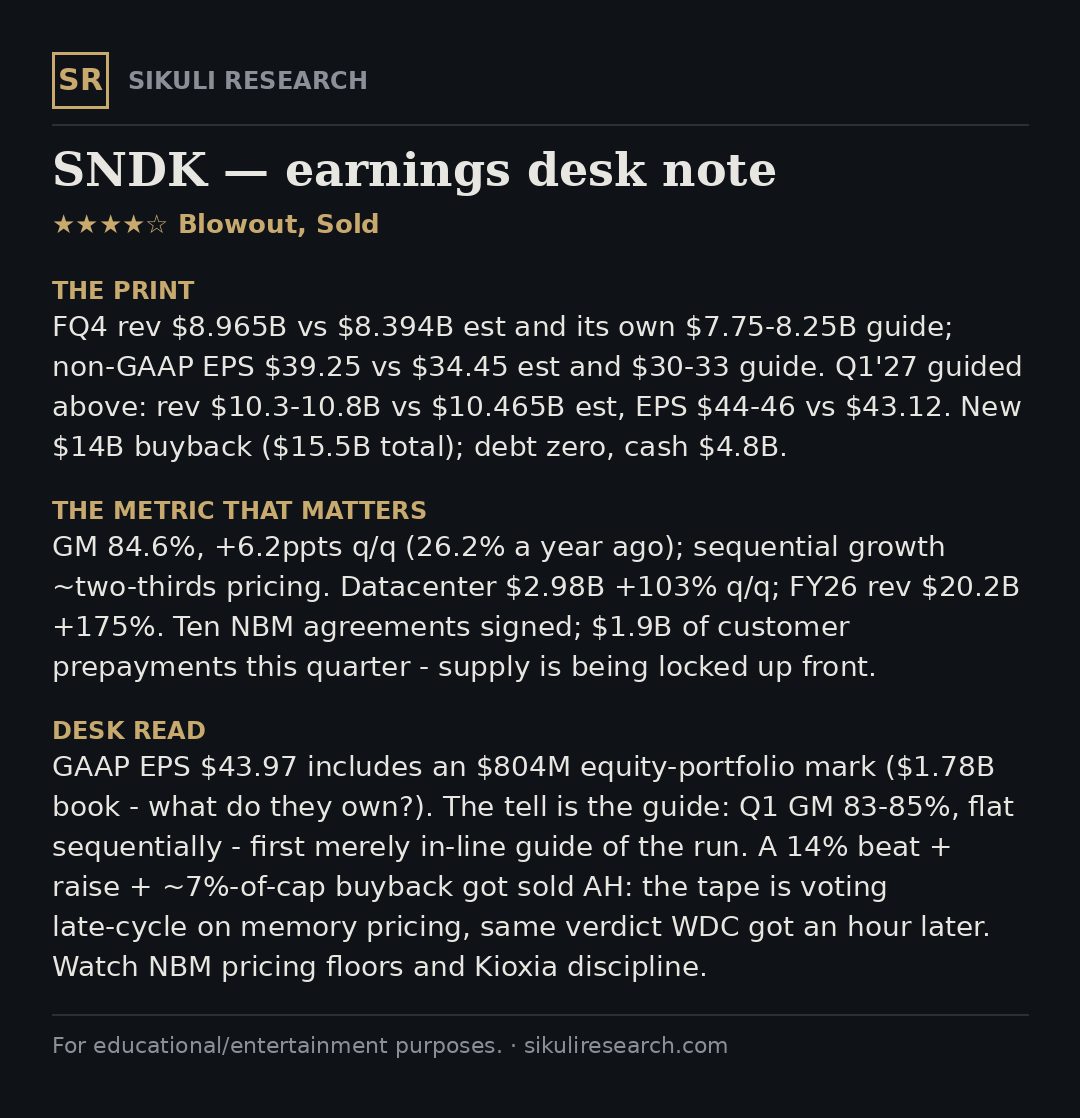
★★★★☆ Blowout, Sold. Rev $8.97B vs $8.39B est, EPS $39.25 vs $34.45, guided above, $14B new buyback — and it SOLD. Memory cycle-top vote, same as WDC. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
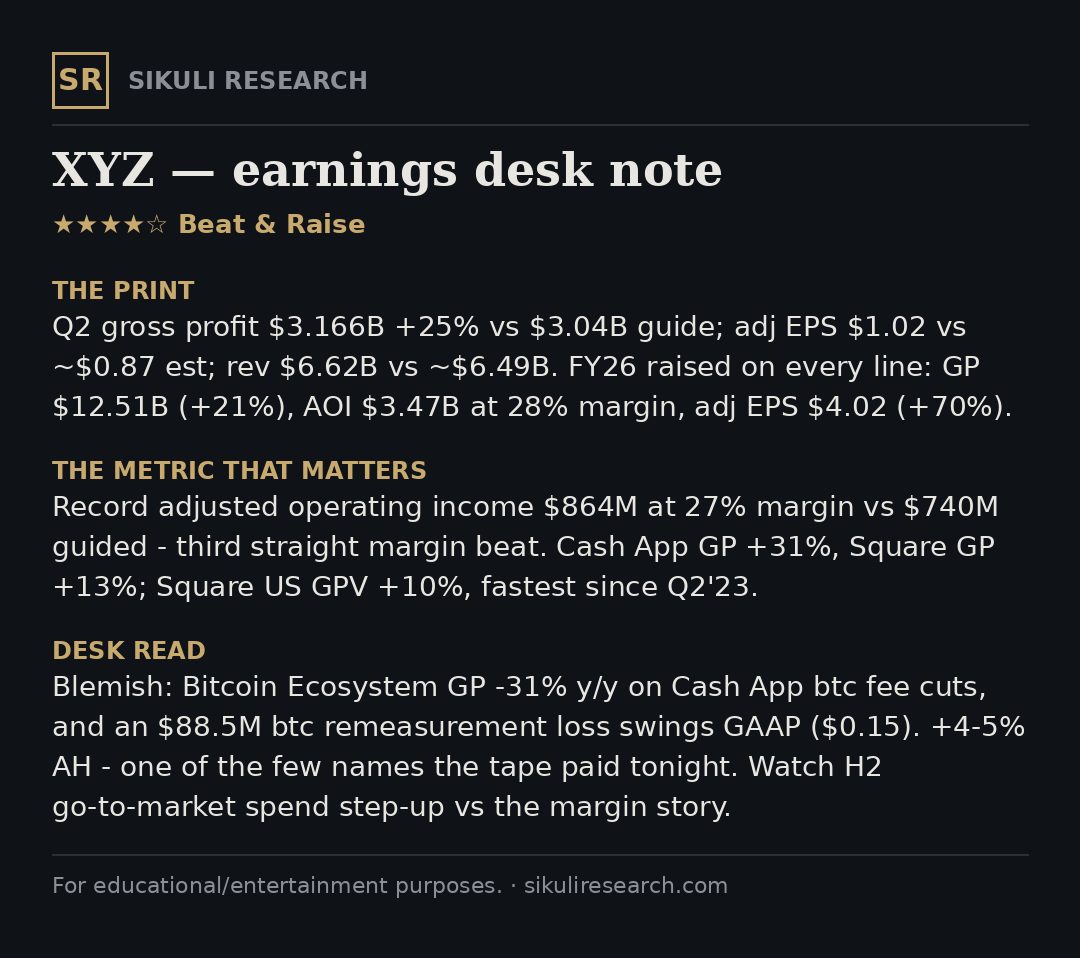
★★★★☆ Beat & Raise. Gross profit $3.17B +25%, adj EPS $1.02 vs $0.87, FY raised on every line, record 27% AOI margin. +4-5% AH. Bitcoin GP -31% the blemish. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
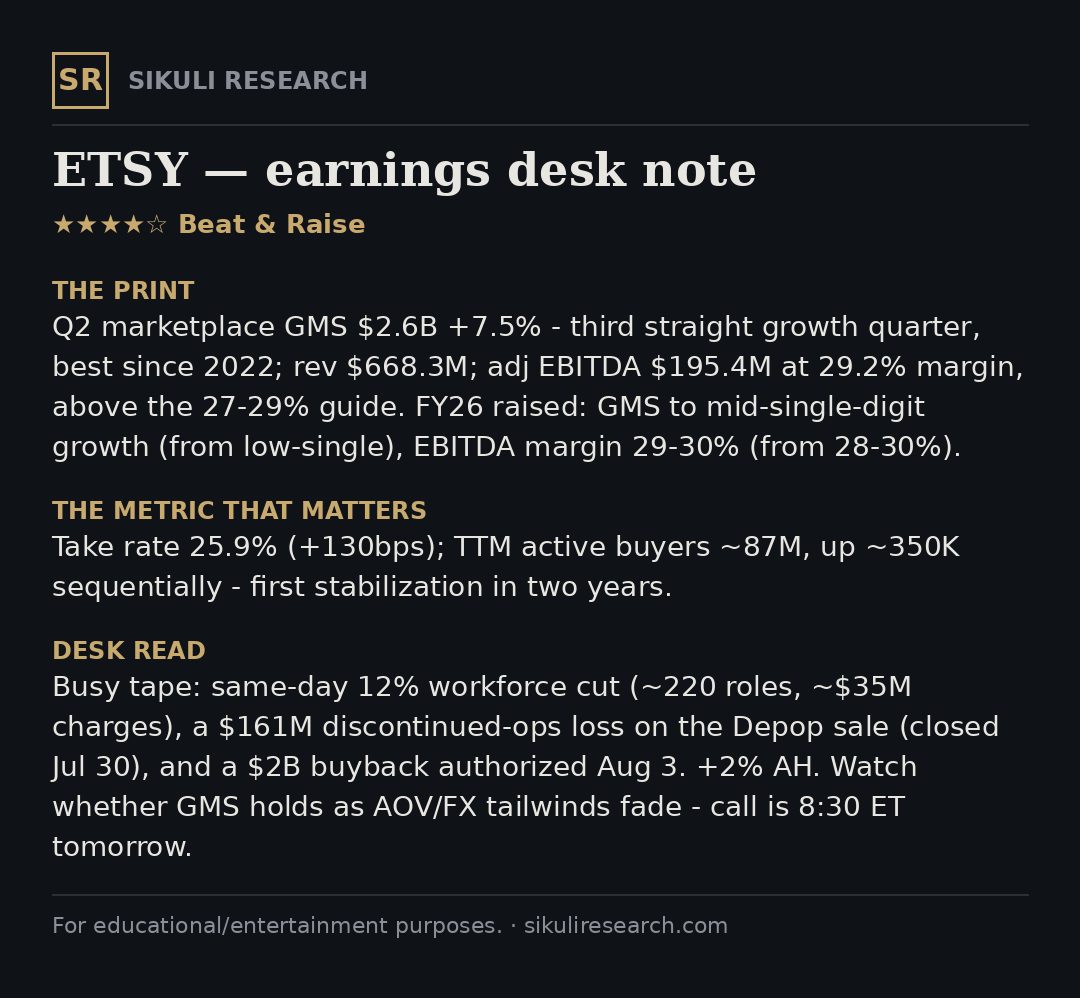
★★★★☆ Beat & Raise. GMS +7.5%, best since 2022; take rate 25.9%; buyers finally stabilized; FY raised. +2% AH. Also: 12% workforce cut and a $2B buyback. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
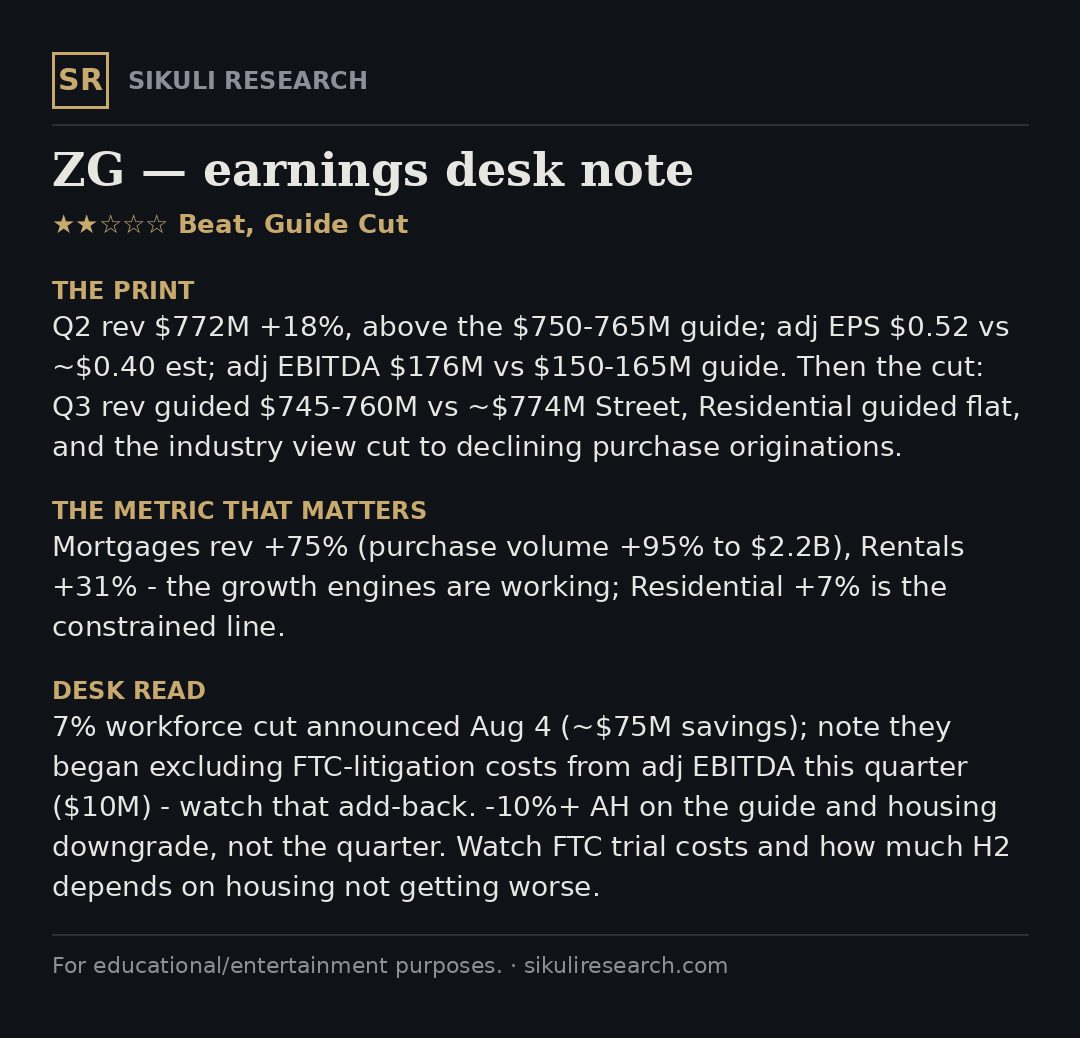
★★☆☆☆ Beat, Guide Cut. Q2 beat ($772M +18%, EBITDA above guide) but Q3 guided below Street, housing view cut to declining, 7% layoffs. -10%+ AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
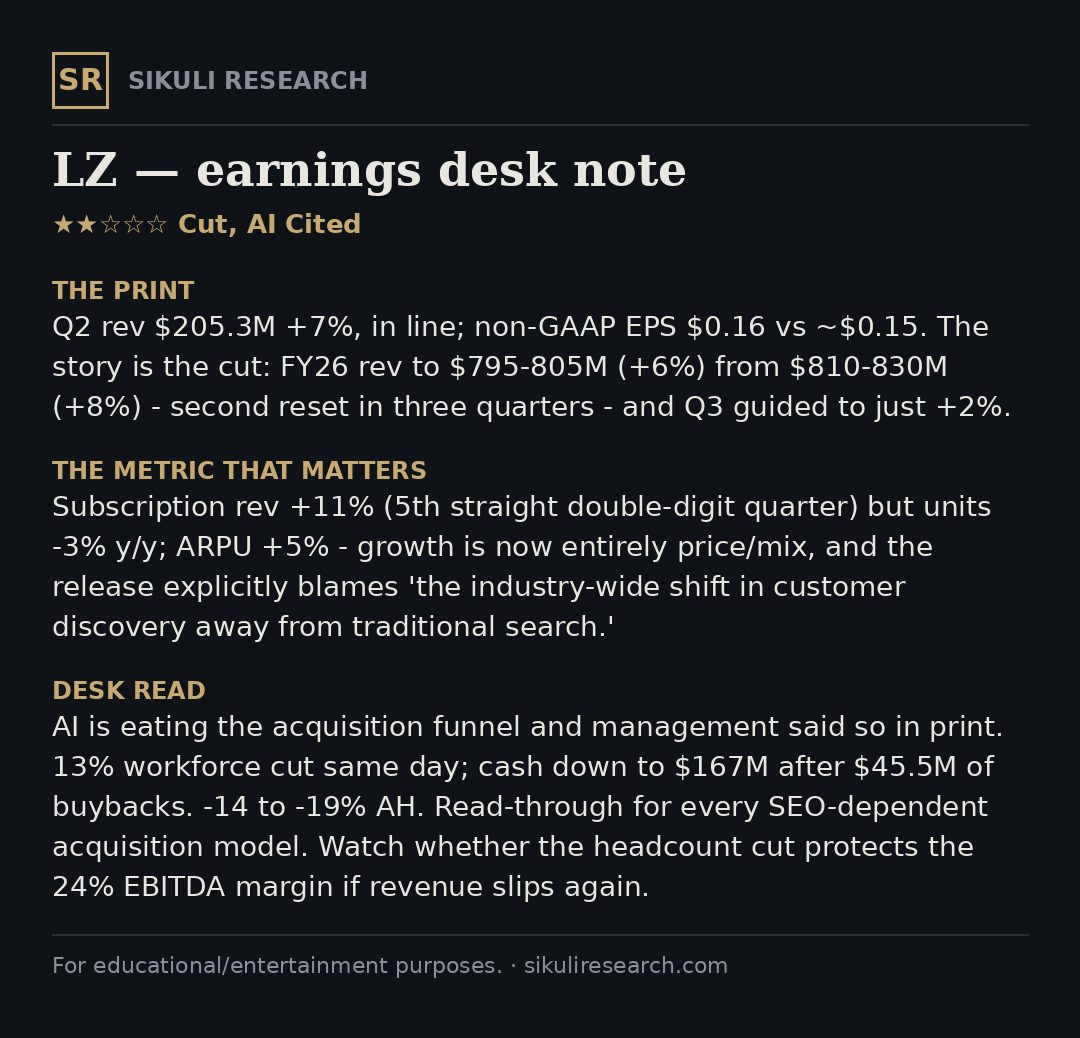
★★☆☆☆ Cut, AI Cited. In-line quarter, but FY cut again — and the release blames the shift in customer discovery away from traditional search. AI eating the funnel. ~-15% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
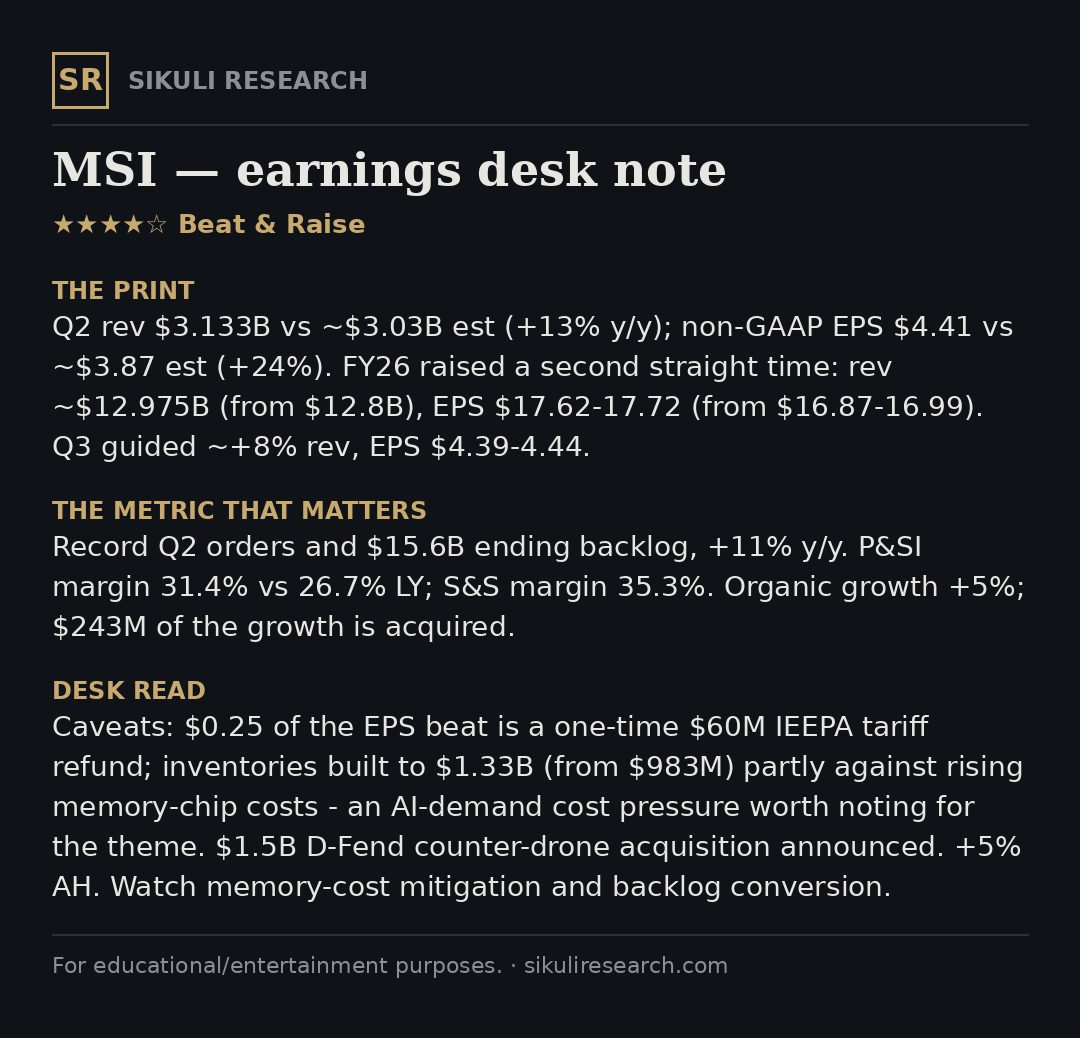
★★★★☆ Beat & Raise. Rev $3.13B vs $3.03B, EPS $4.41 vs $3.87, record $15.6B backlog, FY raised again. +5% AH. $0.25 of the beat is a one-time tariff refund. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
★★★☆☆ No consensus staged. Tronox swung to positive free cash flow of $60M but adjusted loss widened to -$0.51 from -$0.28 on weak margins despite strong volumes. #QQQ #SPX · Sikuli Research — educational, not advice.
★★★★☆ Guide Up (no consensus). Ralph Lauren beat on revenue and earnings, with adjusted EPS of $4.59 up 22% and revenue up 14% to $2.0B, led by Asia up 25% constant currency and China up over 40%. #QQQ #SPX · Sikuli Research — educational, not advice.
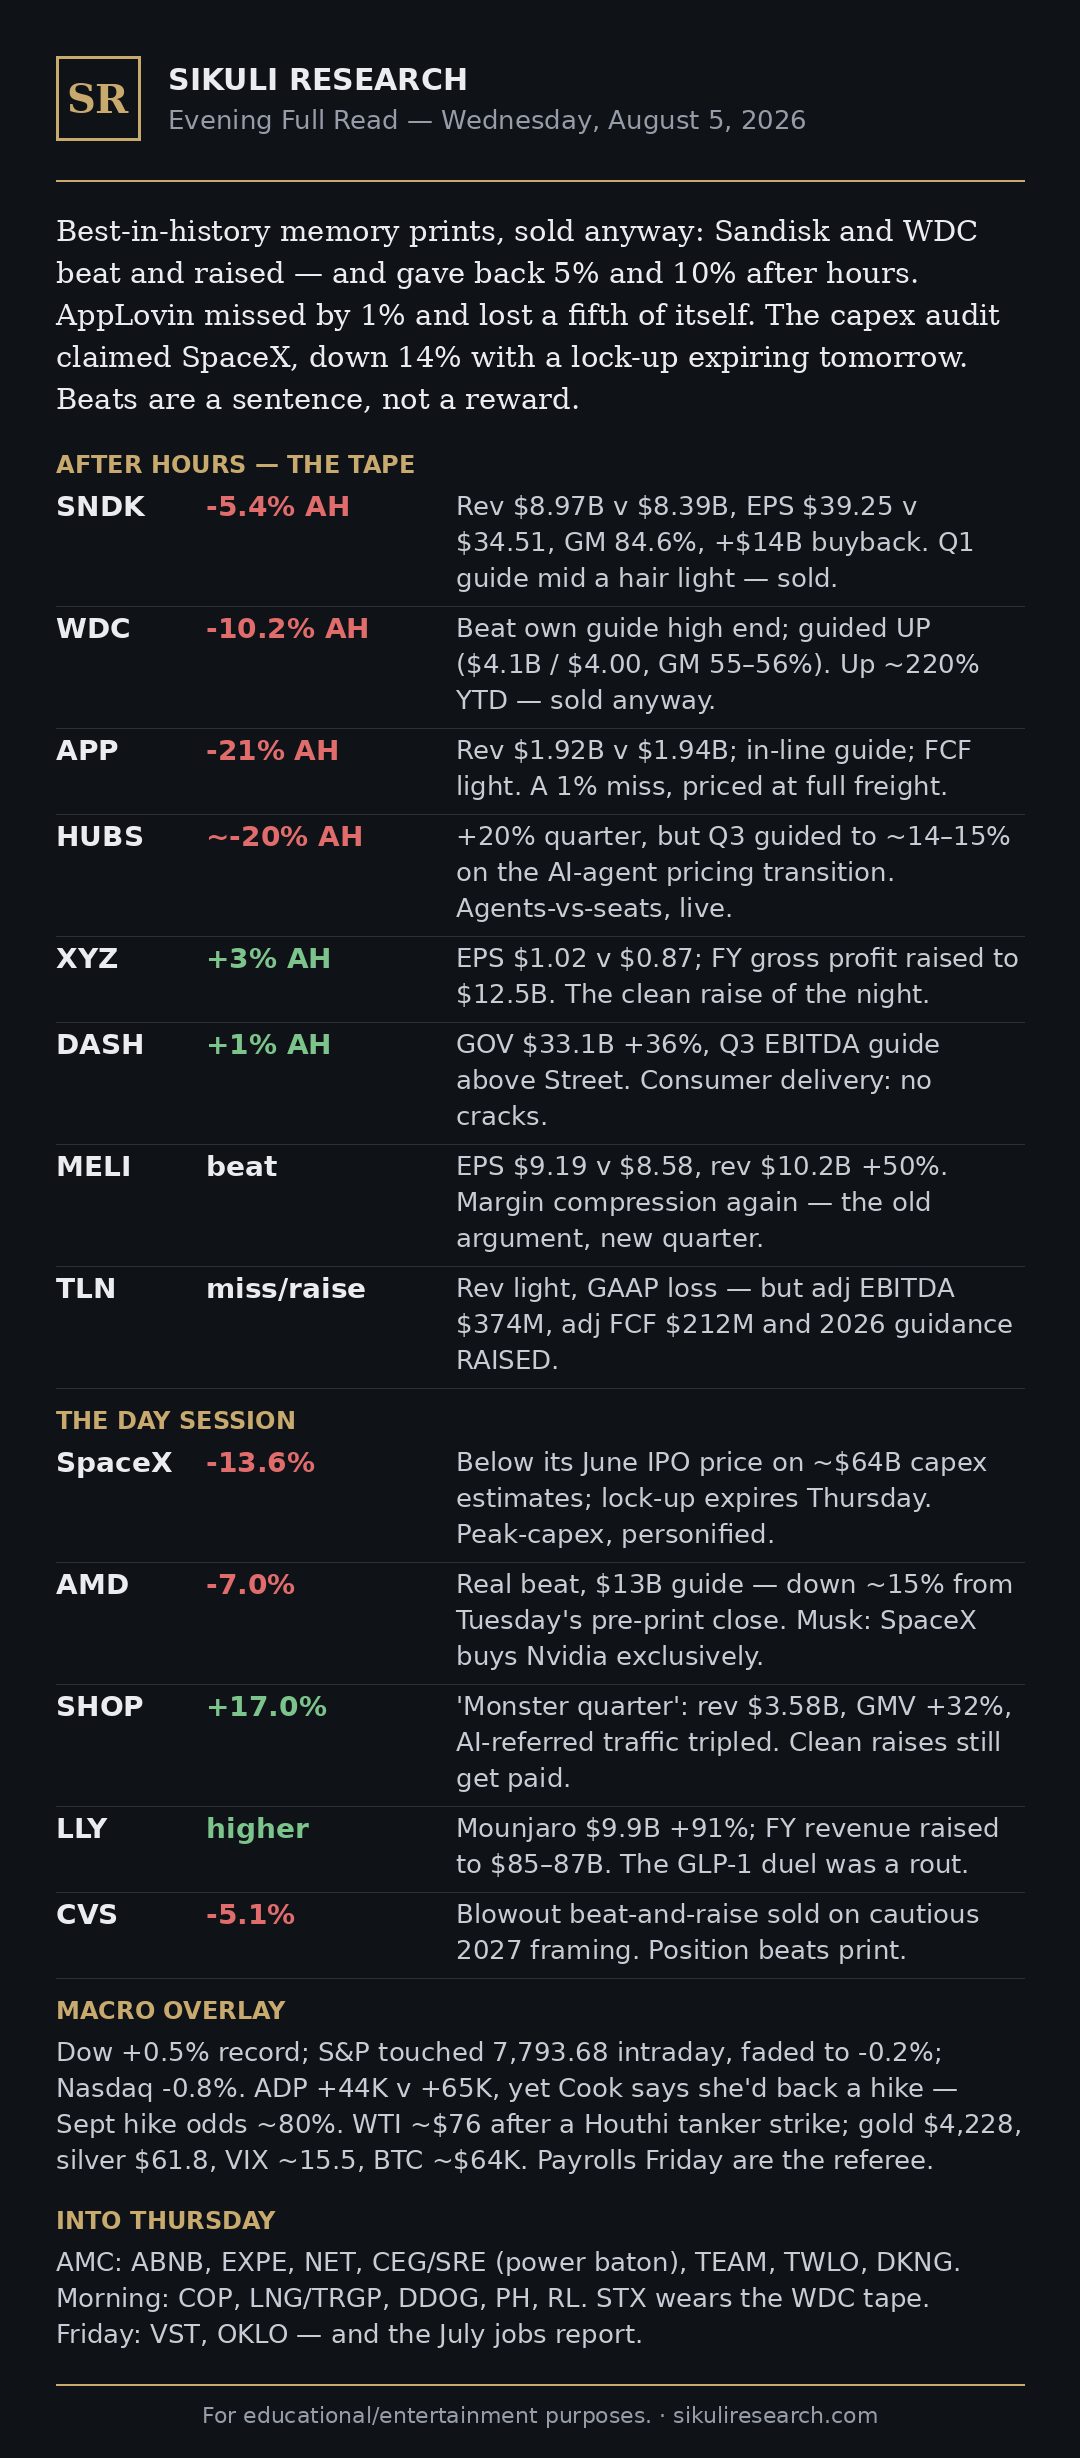
Memory's best-ever prints got sold: SNDK -5%, WDC -10% AH on beat-and-raises. APP -21% on a 1% miss; HUBS -20% repricing for AI agents. SpaceX -14%, lock-up tomorrow. Full read at Sikuli Research (link in bio)
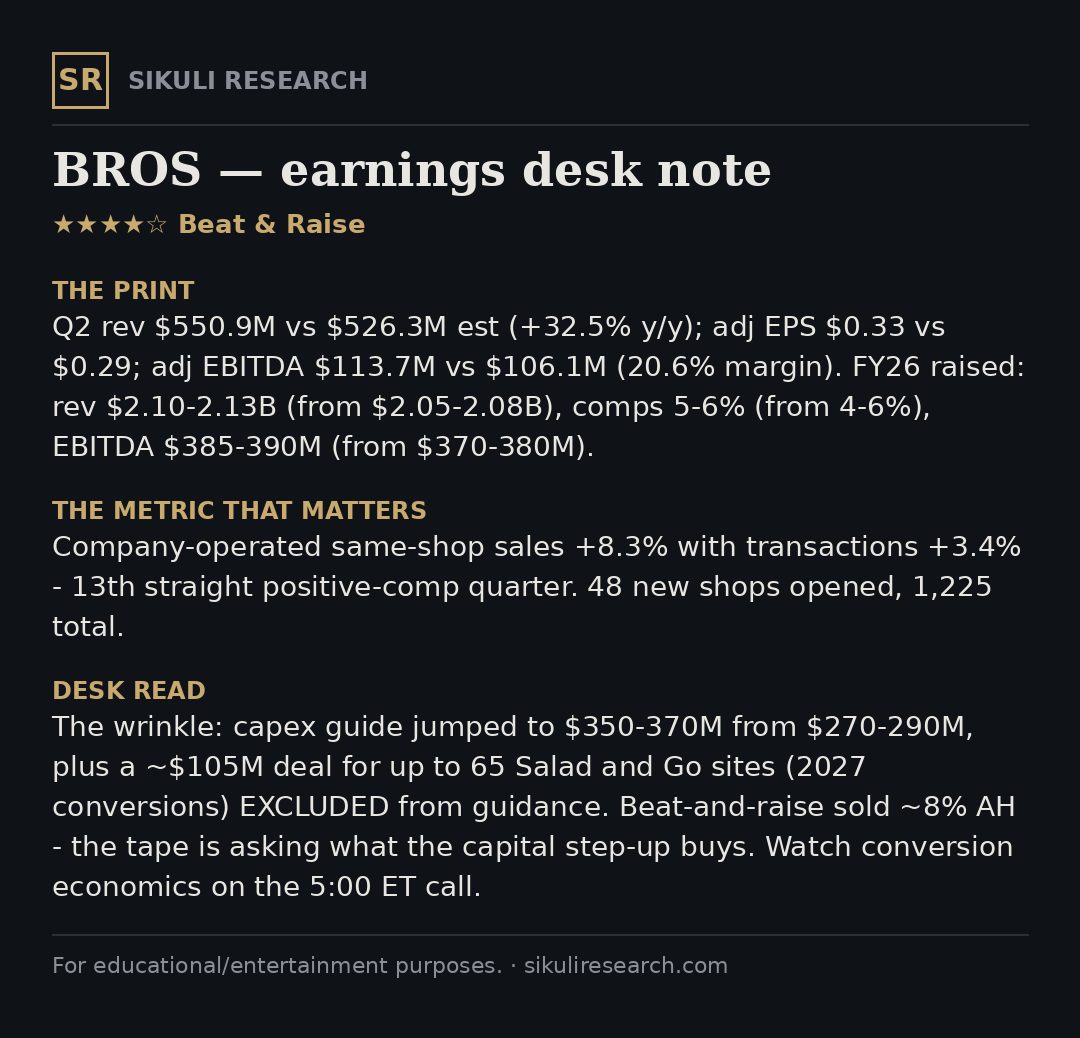
★★★★☆ Beat & Raise. Rev $550.9M vs $526M est, comps +5.8%, FY raised — but capex guide +$80M and a 65-site Salad & Go deal; sold ~8% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
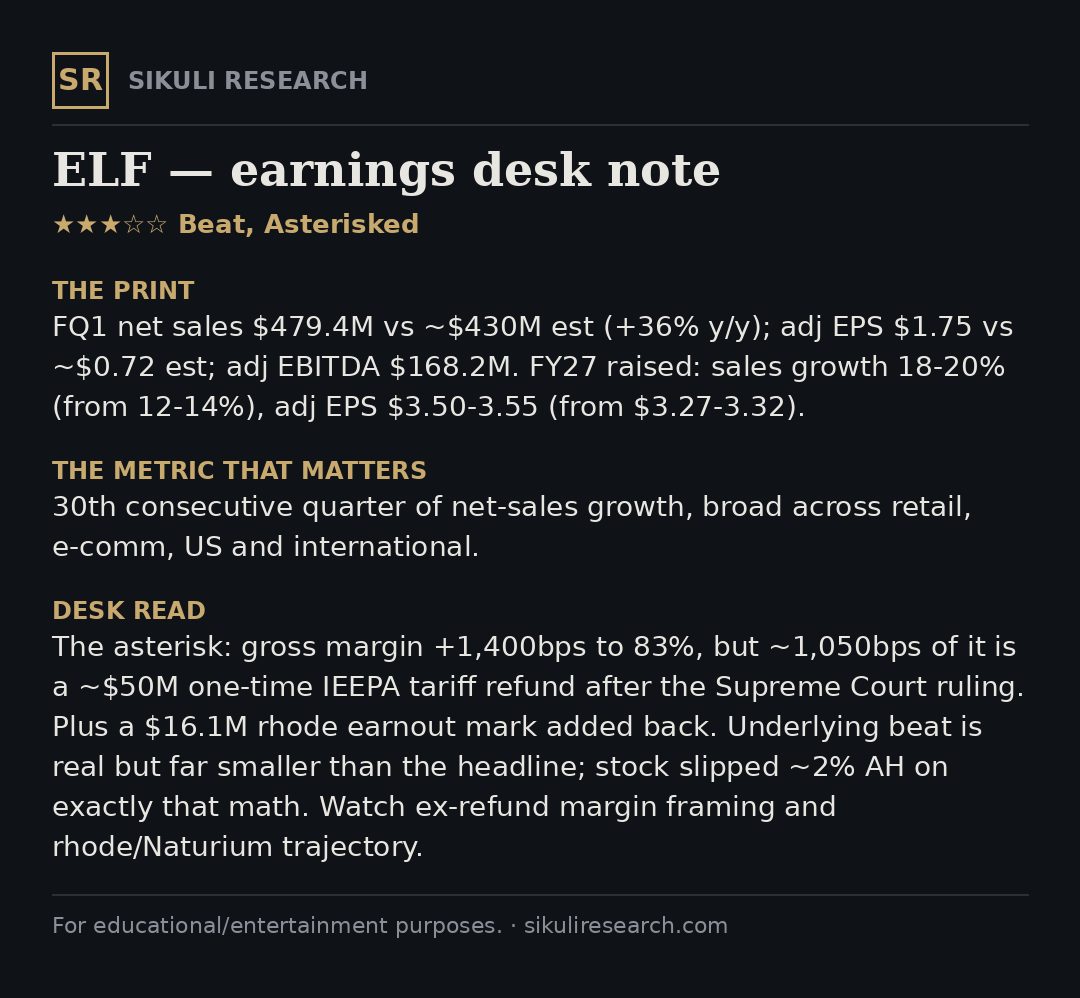
★★★☆☆ Beat, Asterisked. Sales $479M vs ~$430M est, FY raised to 18-20% growth — but a ~$50M one-time tariff refund drove the margin blowout. -2% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
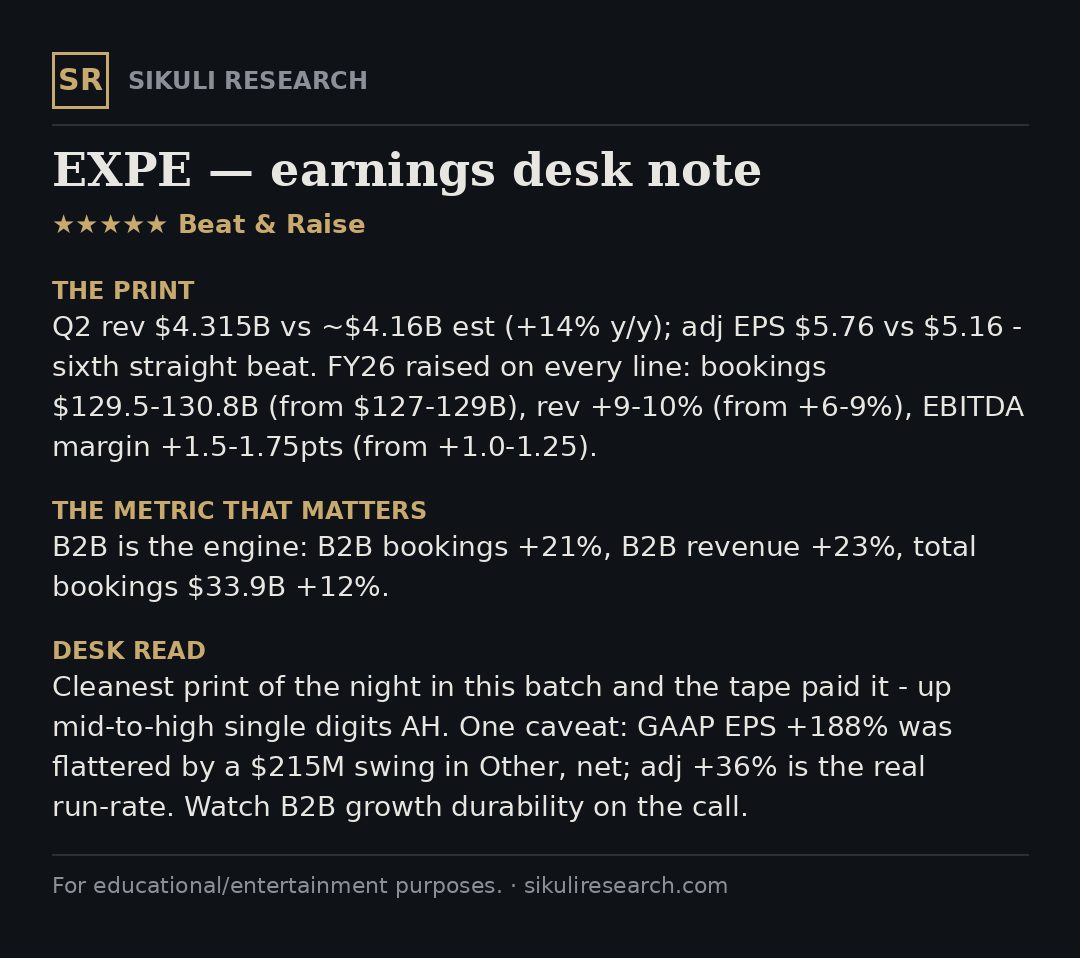
★★★★★ Beat & Raise. Rev $4.32B, adj EPS $5.76 vs $5.16, B2B bookings +21%, FY raised on every line. One of the few prints the tape paid tonight. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
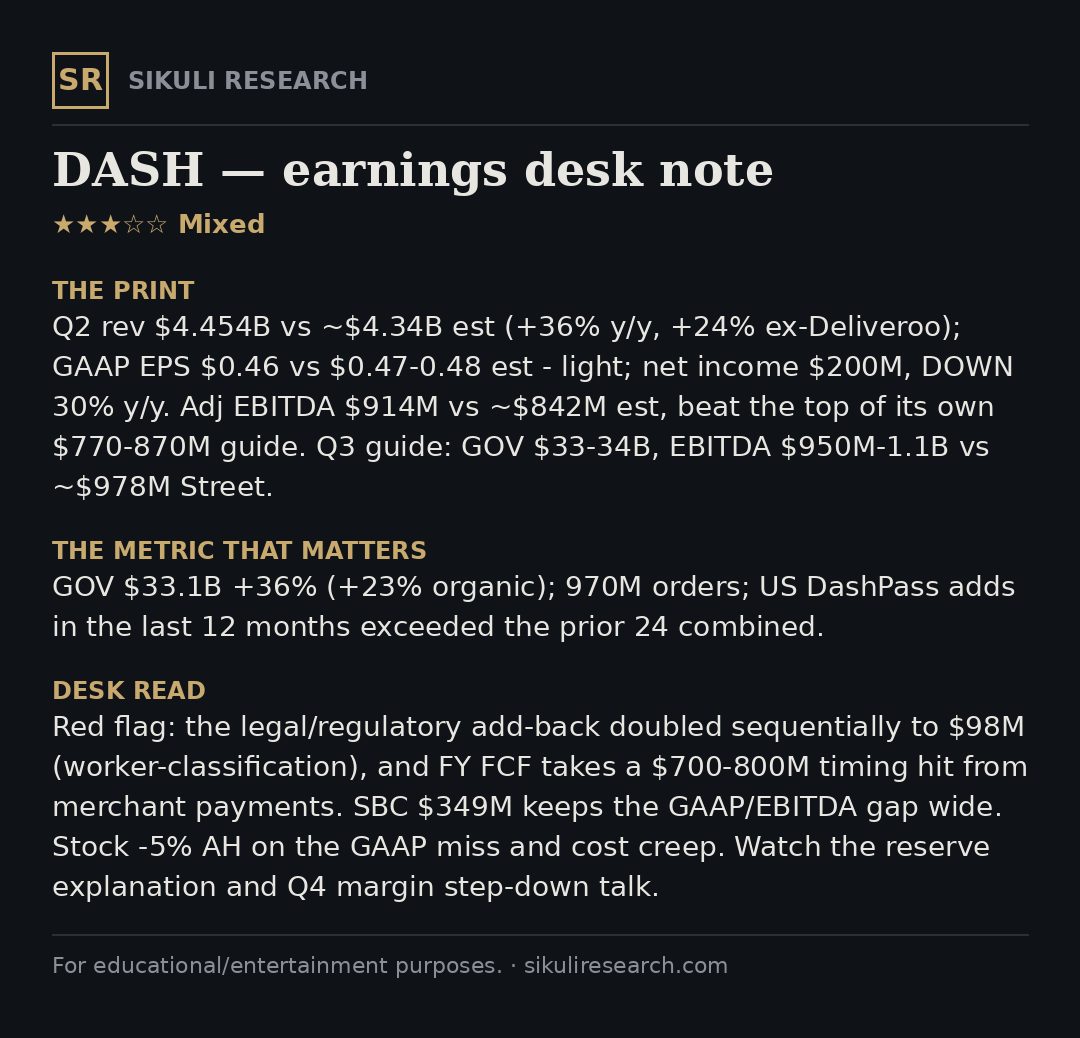
★★★☆☆ Mixed. GOV $33.1B +36%, EBITDA $914M beat, Q3 guided above Street — but GAAP missed and legal reserves doubled to $98M. -5% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
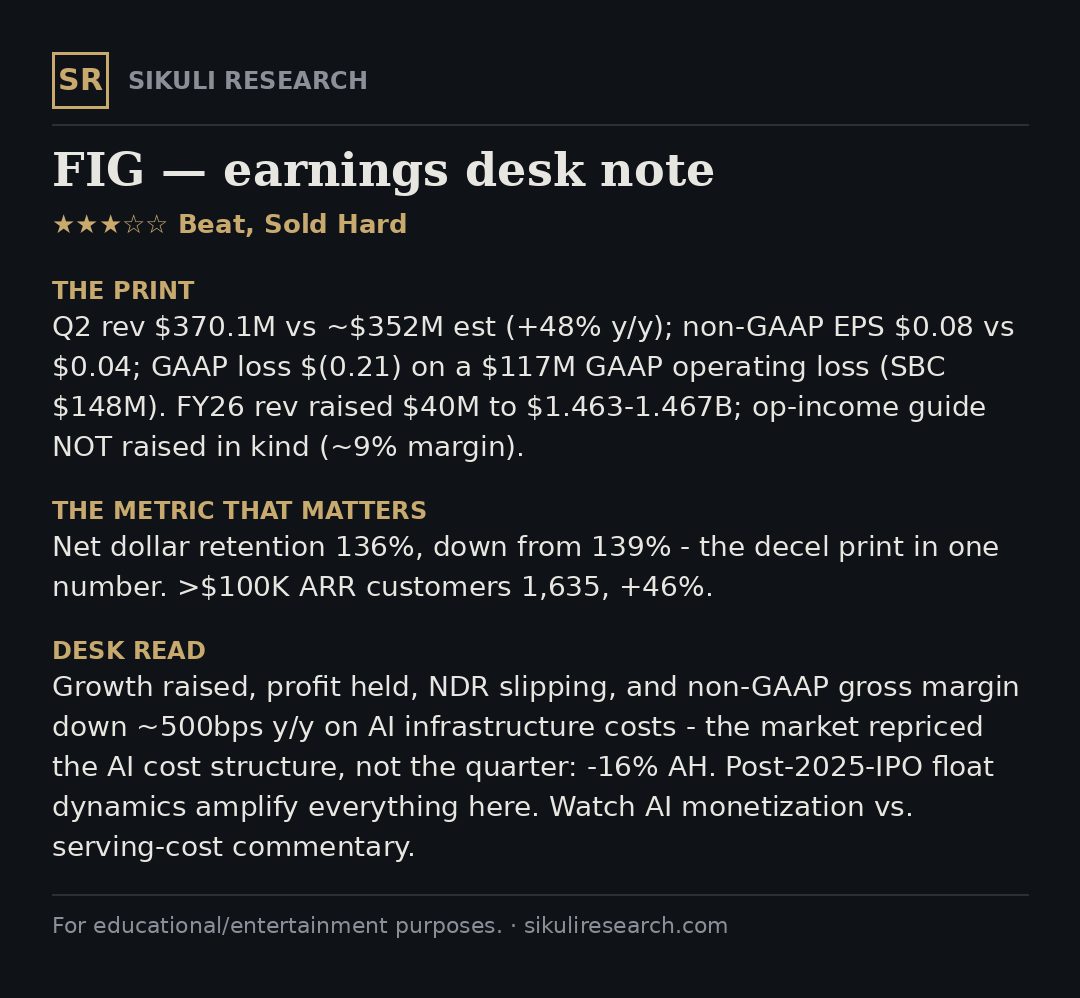
★★★☆☆ Beat, Sold Hard. Rev $370M +48% beat, FY raised $40M — but NDR 139%→136% and gross margin -500bps on AI compute. -16% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
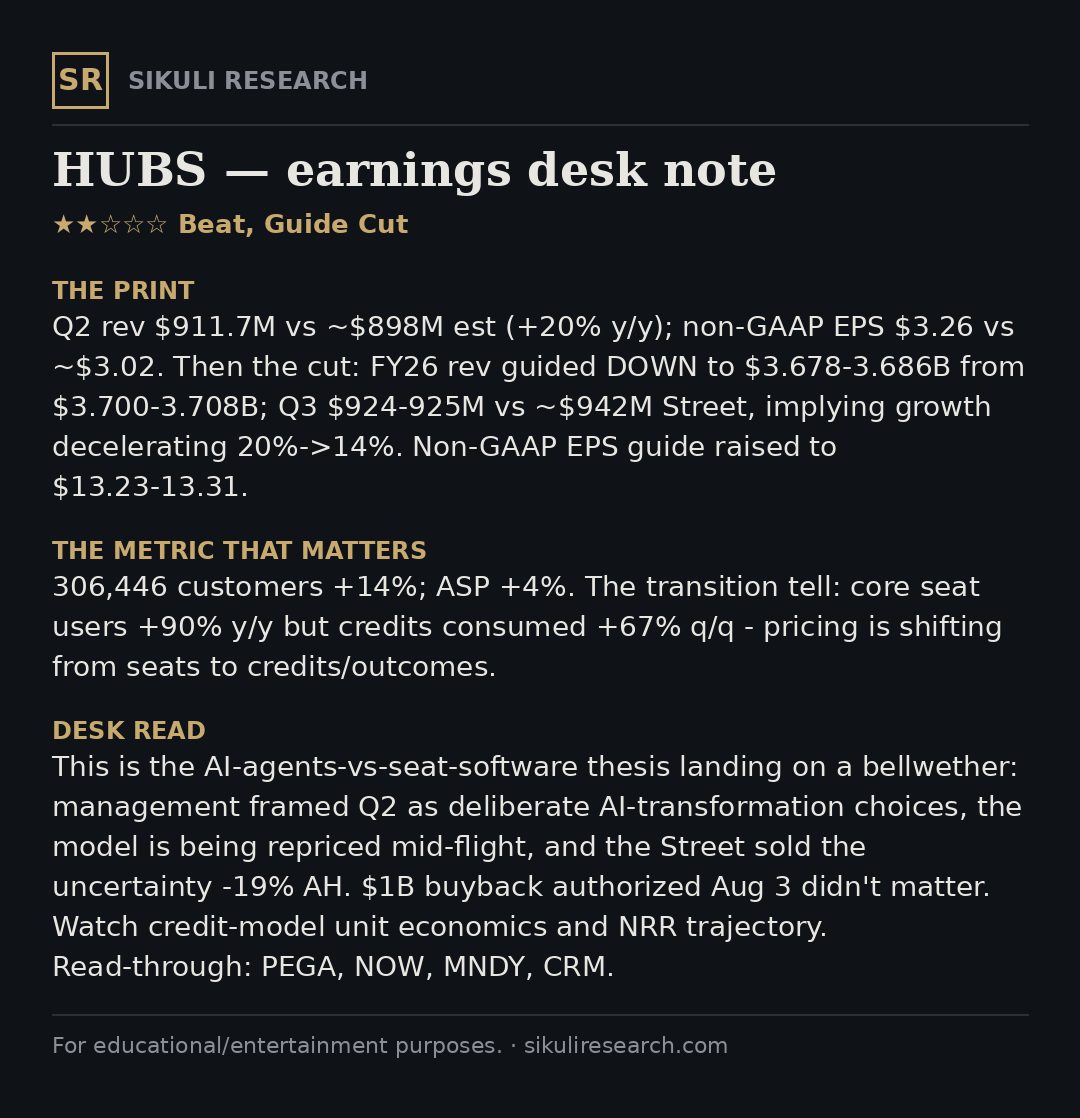
★★☆☆☆ Beat, Guide Cut. Q2 beat but FY revenue guide CUT; Q3 implies 14% growth as pricing shifts seats→credits. -19% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
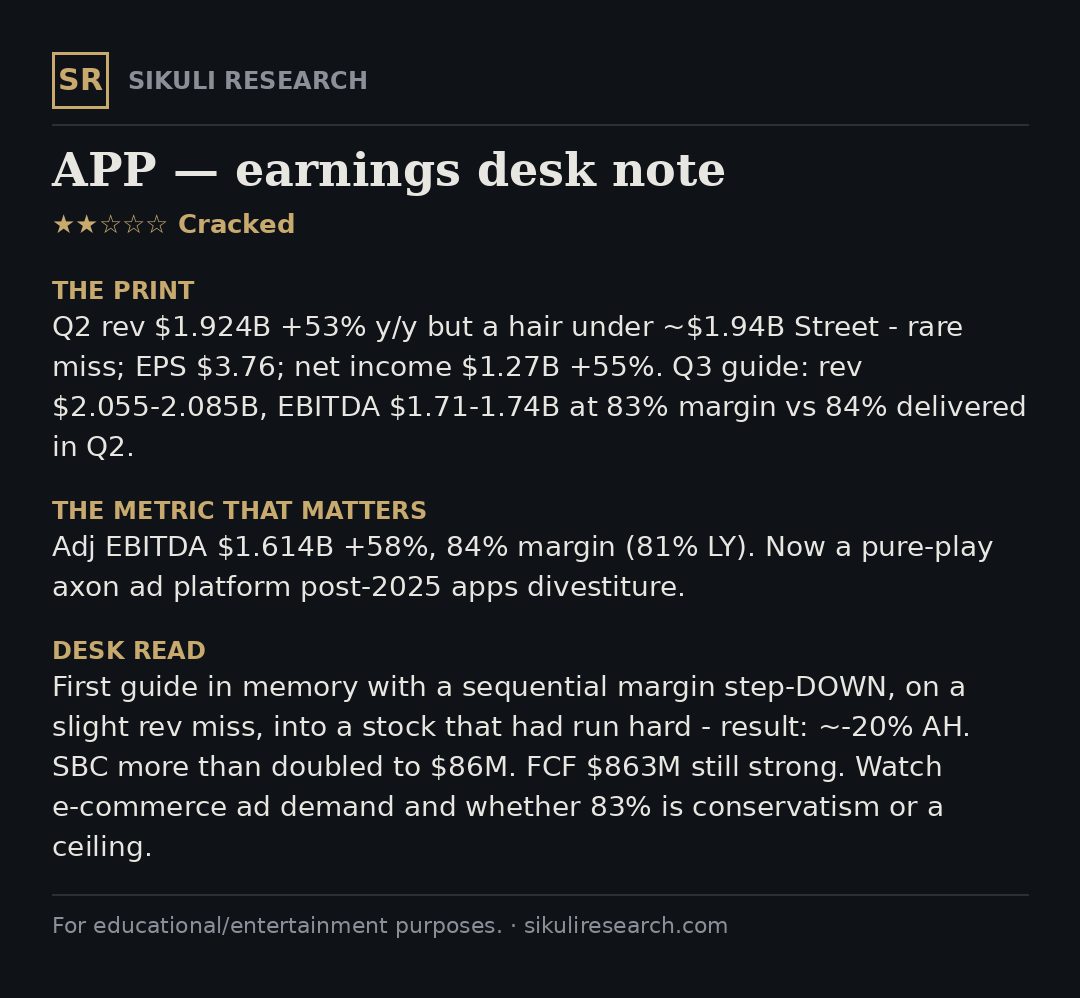
★★☆☆☆ Cracked. Rev $1.92B +53% but a hair light; Q3 EBITDA margin guided 83% vs 84% delivered — first decel signal. ~-20% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
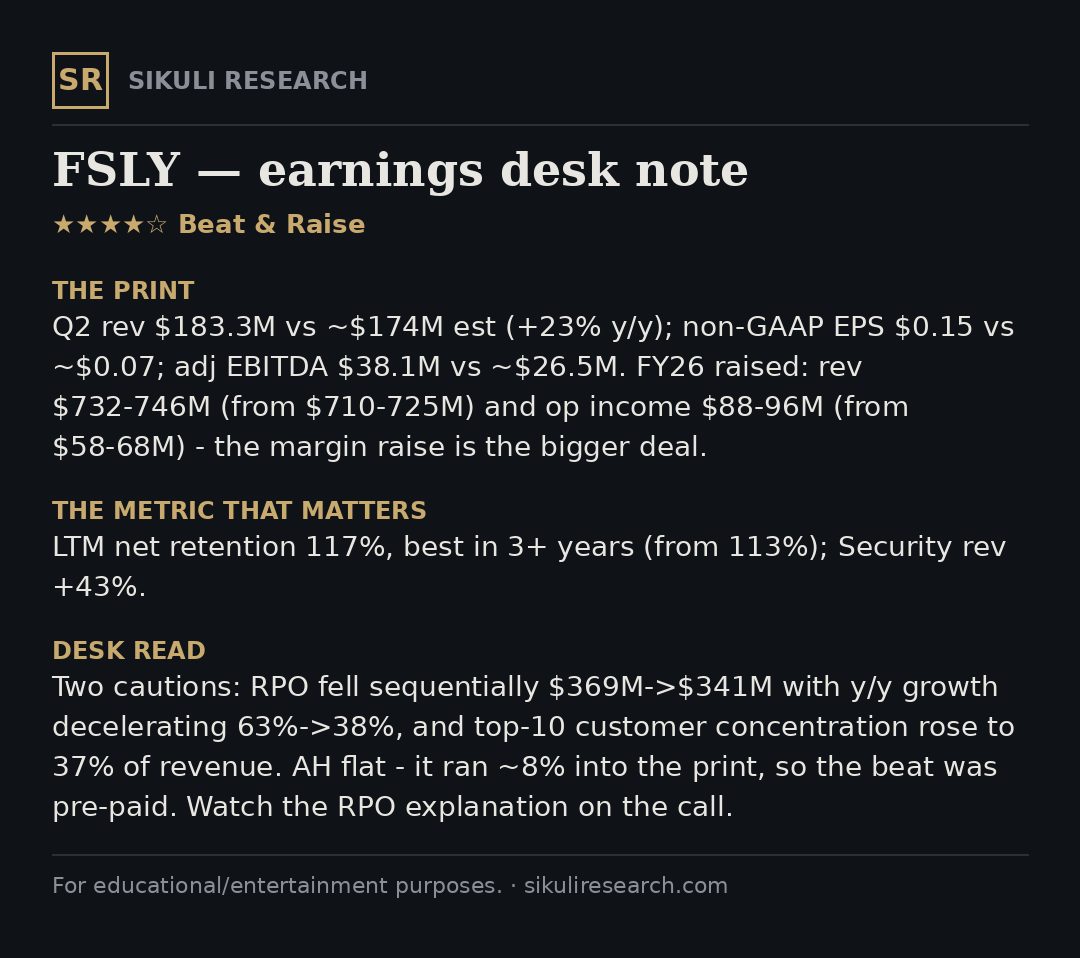
★★★★☆ Beat & Raise. Rev $183.3M +23% beat; FY op-income guide up ~50%; NRR 117%, 3-yr best. Flat AH after running 8% into the print. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
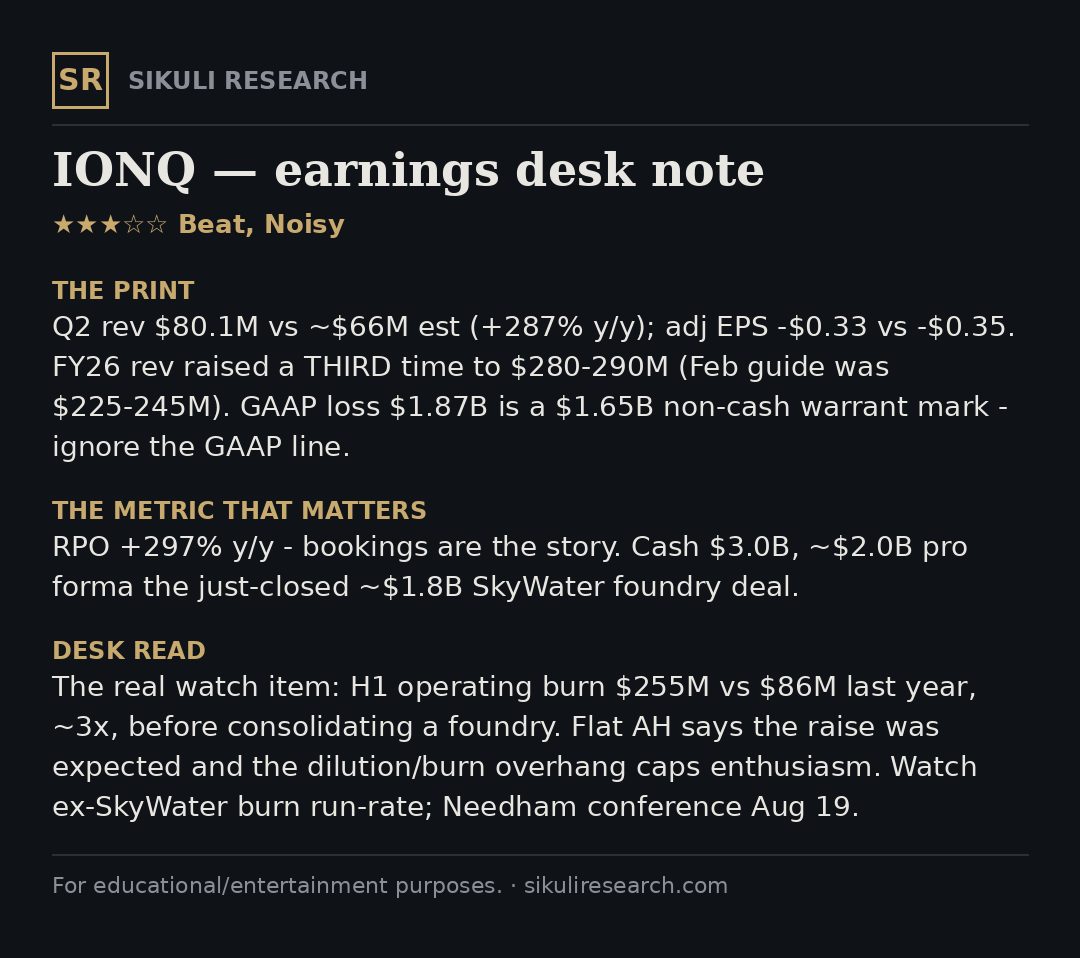
★★★☆☆ Beat, Noisy. Rev $80.1M vs ~$66M est; FY raised a 3rd time. GAAP -$1.87B is warrant noise; the real watch is burn 3x y/y. Flat AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
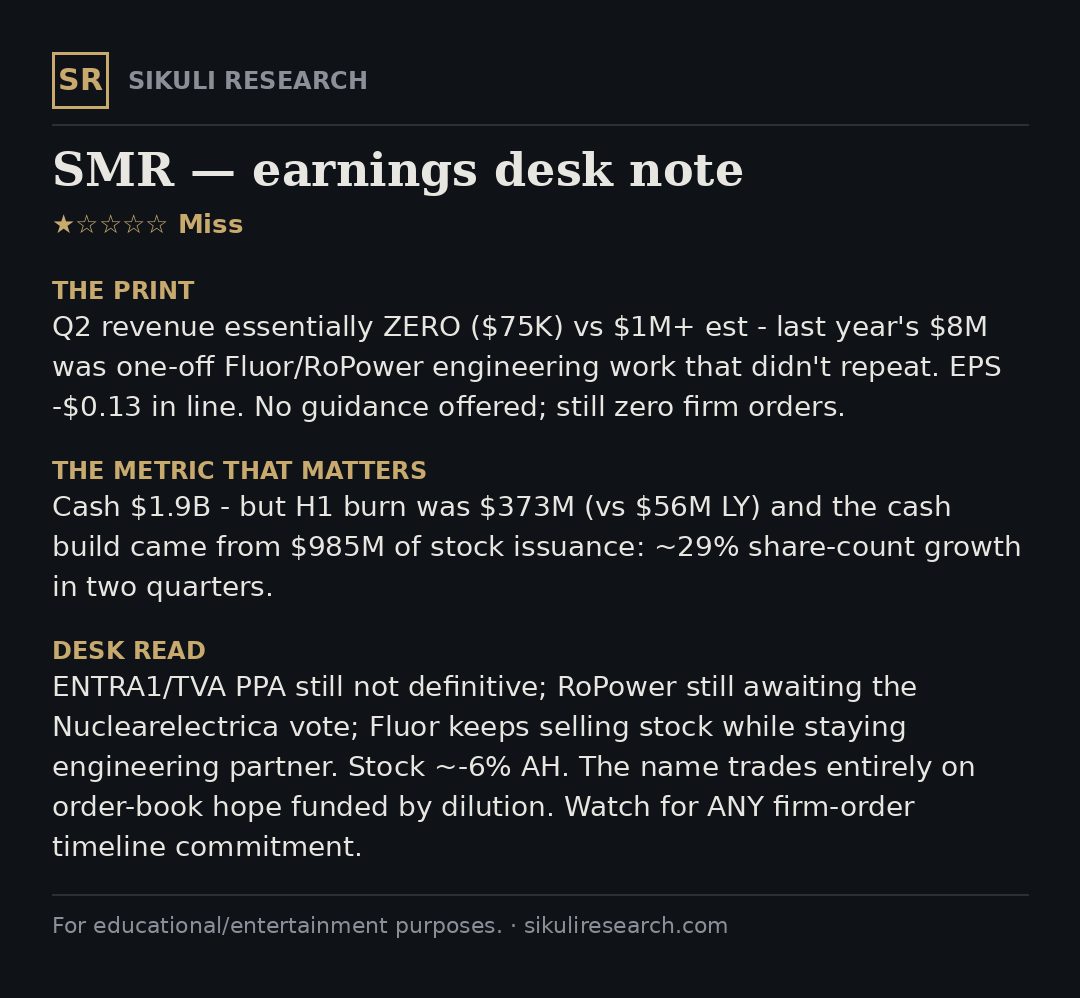
★☆☆☆☆ Miss. Revenue ~$0 vs $1M+ est. $1.9B cash, H1 burn $373M, ~29% dilution in two quarters, zero firm orders. ~-6% AH. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
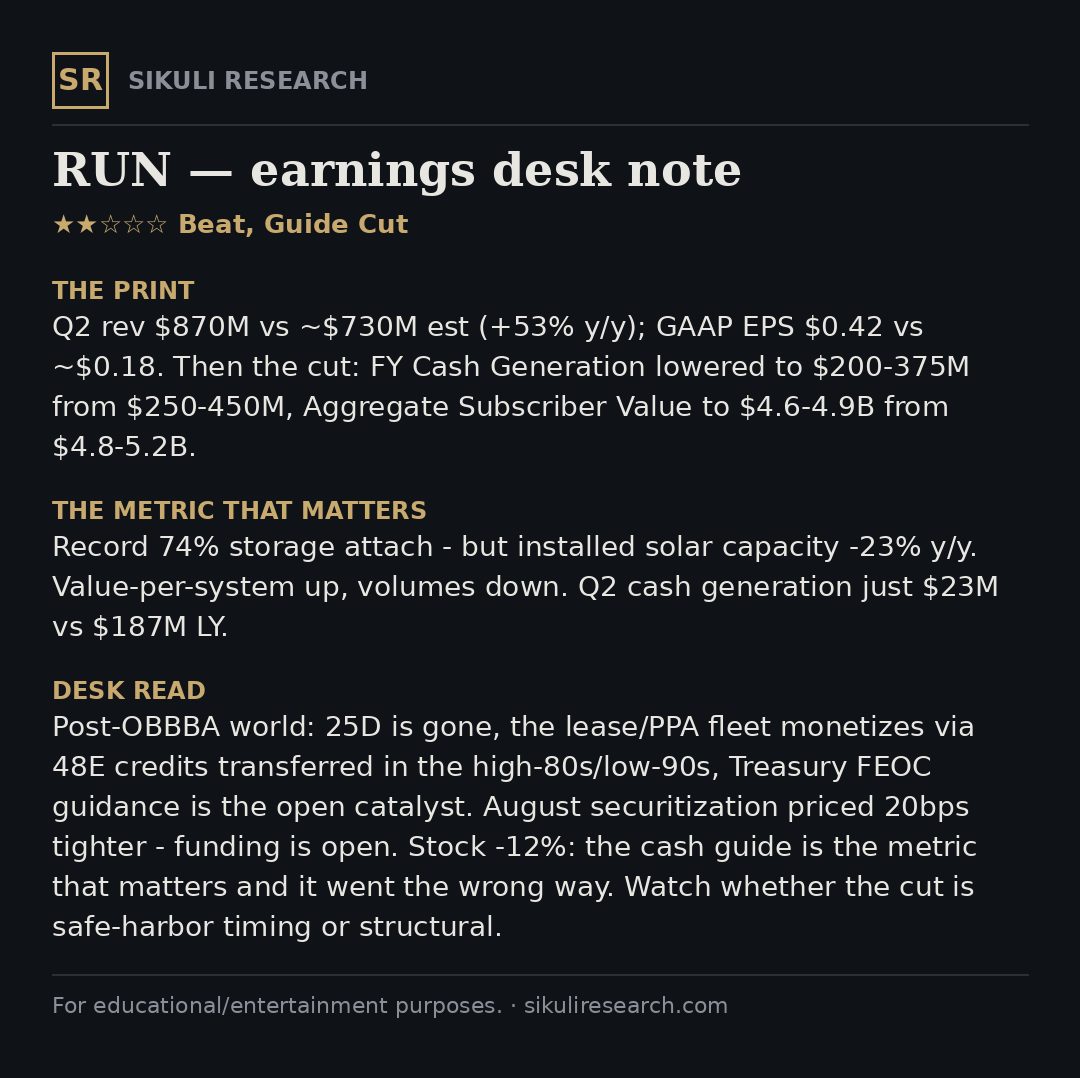
★★☆☆☆ Beat, Guide Cut. Rev $870M vs $730M est beat — but FY cash-generation guide CUT to $200-375M and volumes -23% y/y. -12%. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
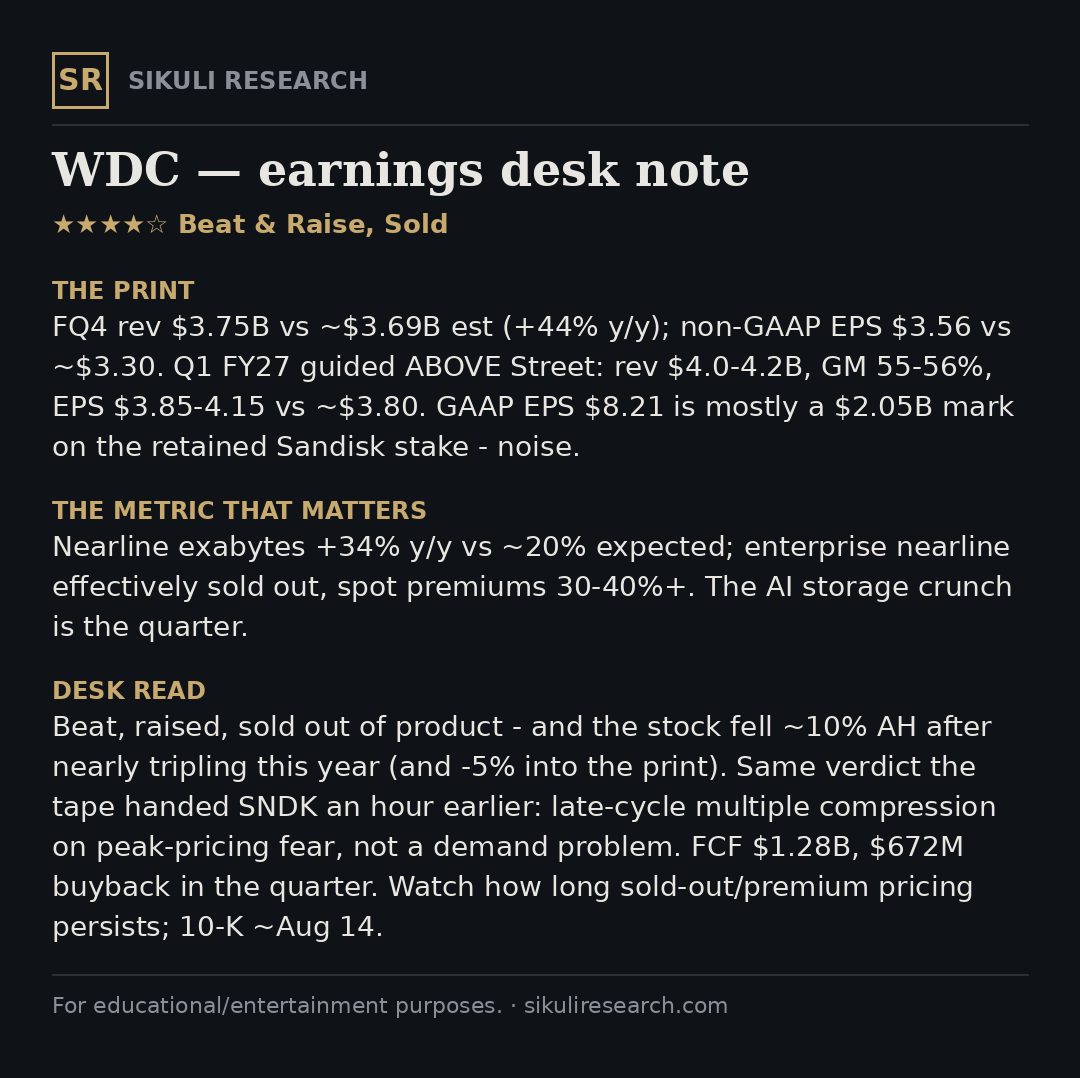
★★★★☆ Beat & Raise, Sold. Rev $3.75B, EPS $3.56 vs $3.30, nearline EBs +34%, guided above Street — sold ~10% AH anyway. Same cycle-top vote as SNDK. Full note on the card. #QQQ #SPX · Sikuli Research — educational, not advice.
★★★☆☆ No consensus staged. CF crushed the quarter with revenue up 18% and adjusted earnings up 92% year-on-year as pricing surged on Middle East supply disruptions. #QQQ #SPX · Sikuli Research — educational, not advice.
★★★☆☆ No consensus staged. CF crushed Q2 with adjusted EBITDA up 57% to $1.192B, driven by strong nitrogen pricing in a tight global market. #QQQ #SPX · Sikuli Research — educational, not advice.
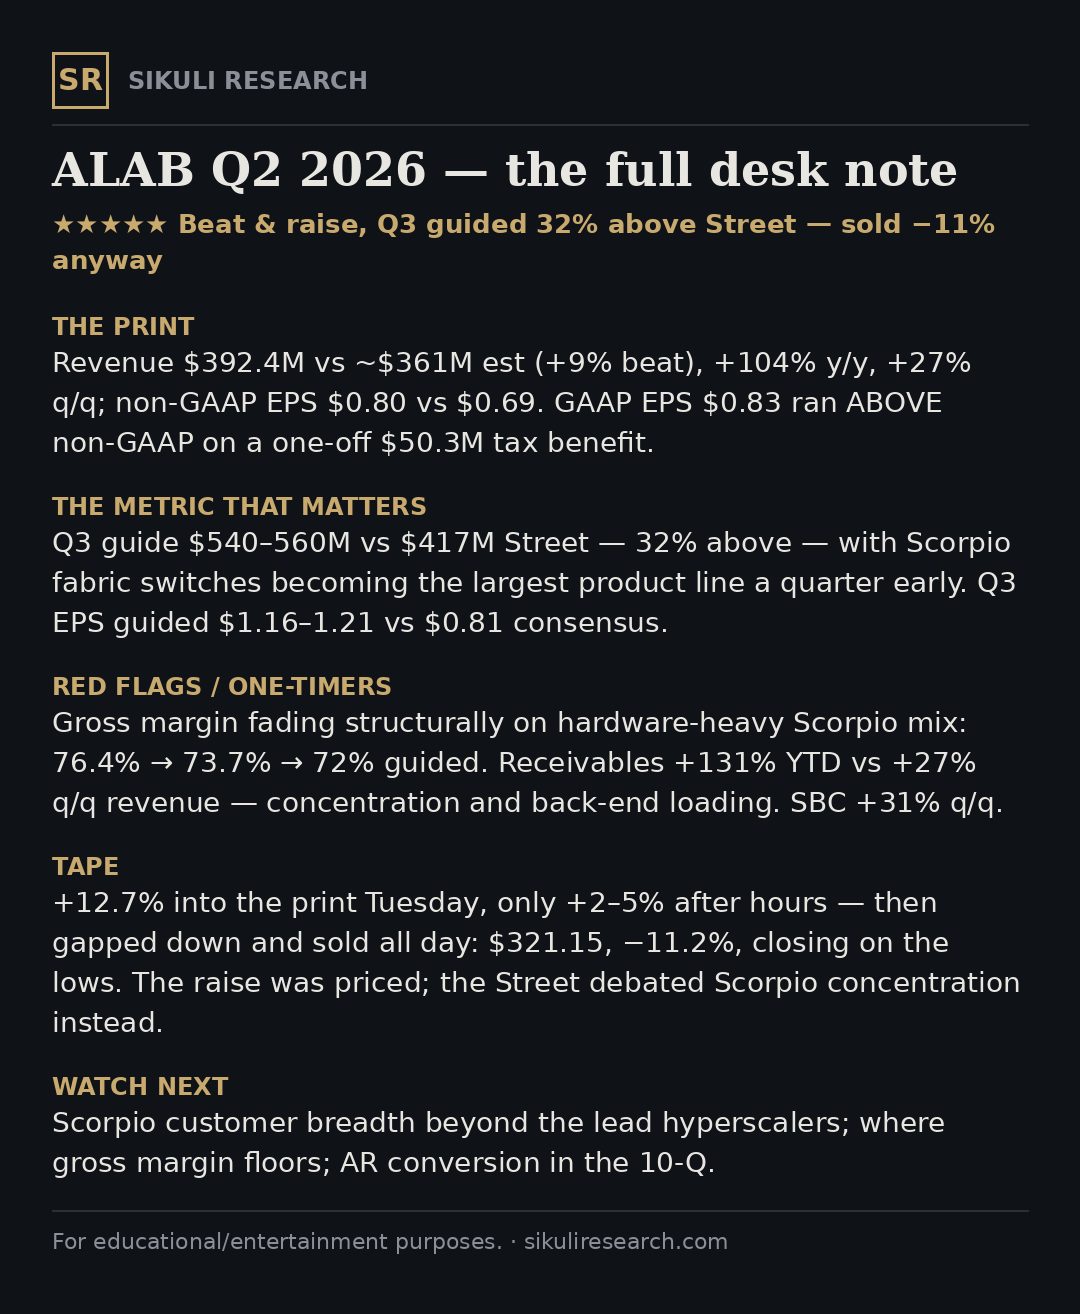
★★★★★ Beat & Raise. Revenue +104%, Q3 guided 32% above Street, Scorpio a quarter early — and it still sold −11%. What was priced, and the margin mix, on the card. #QQQ #SPX Sikuli Research — educational, not advice.
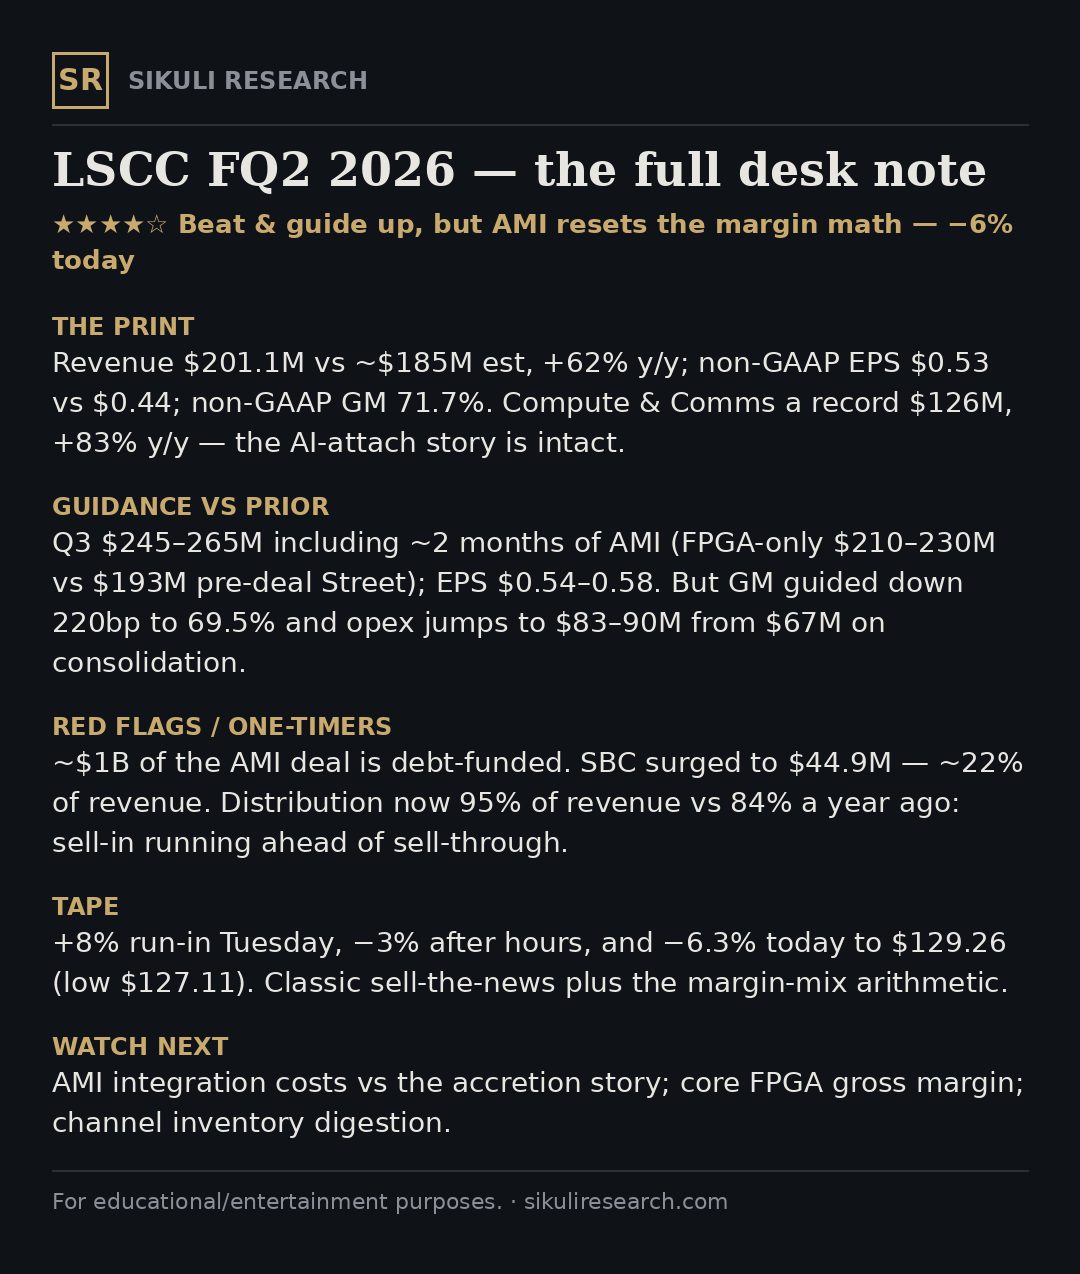
★★★★☆ Beat & Guide Up. Revenue +62%, record compute segment — but AMI drops the margin guide 220bp and lifts opex a third. −6% today. Full note on the card. #QQQ #SPX Sikuli Research — educational, not advice.
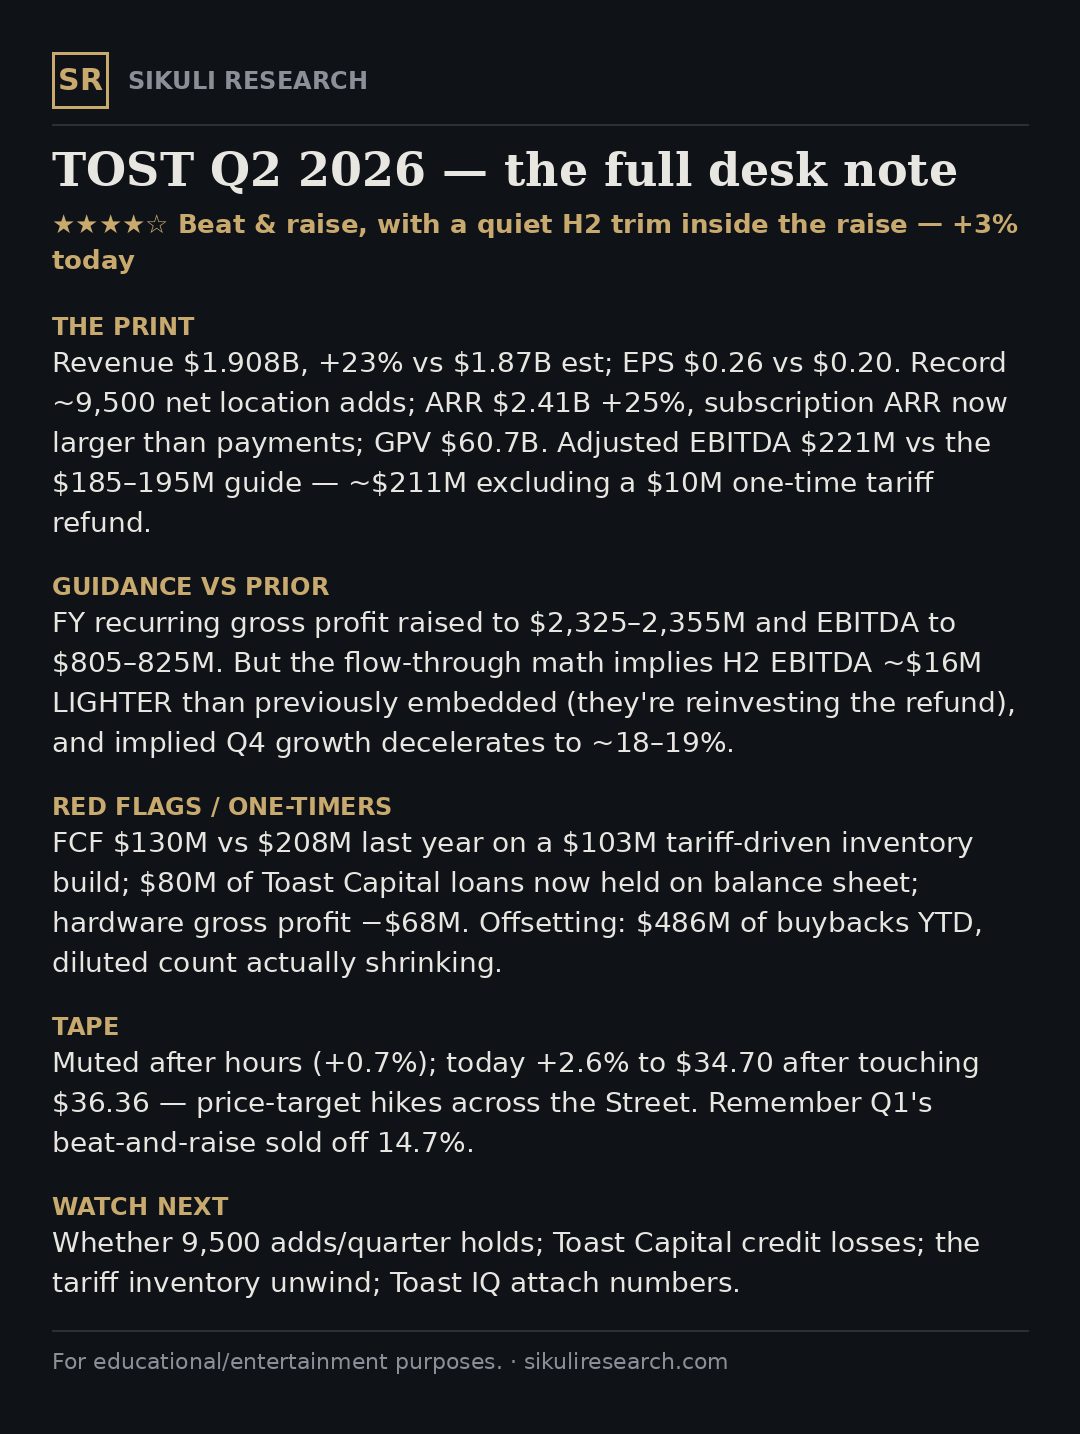
★★★★☆ Beat & Raise. Record 9,500 location adds, ARR +25%, EBITDA well above guide — and a quiet ~$16M H2 trim inside the raise. Card has the math. #QQQ #SPX Sikuli Research — educational, not advice.
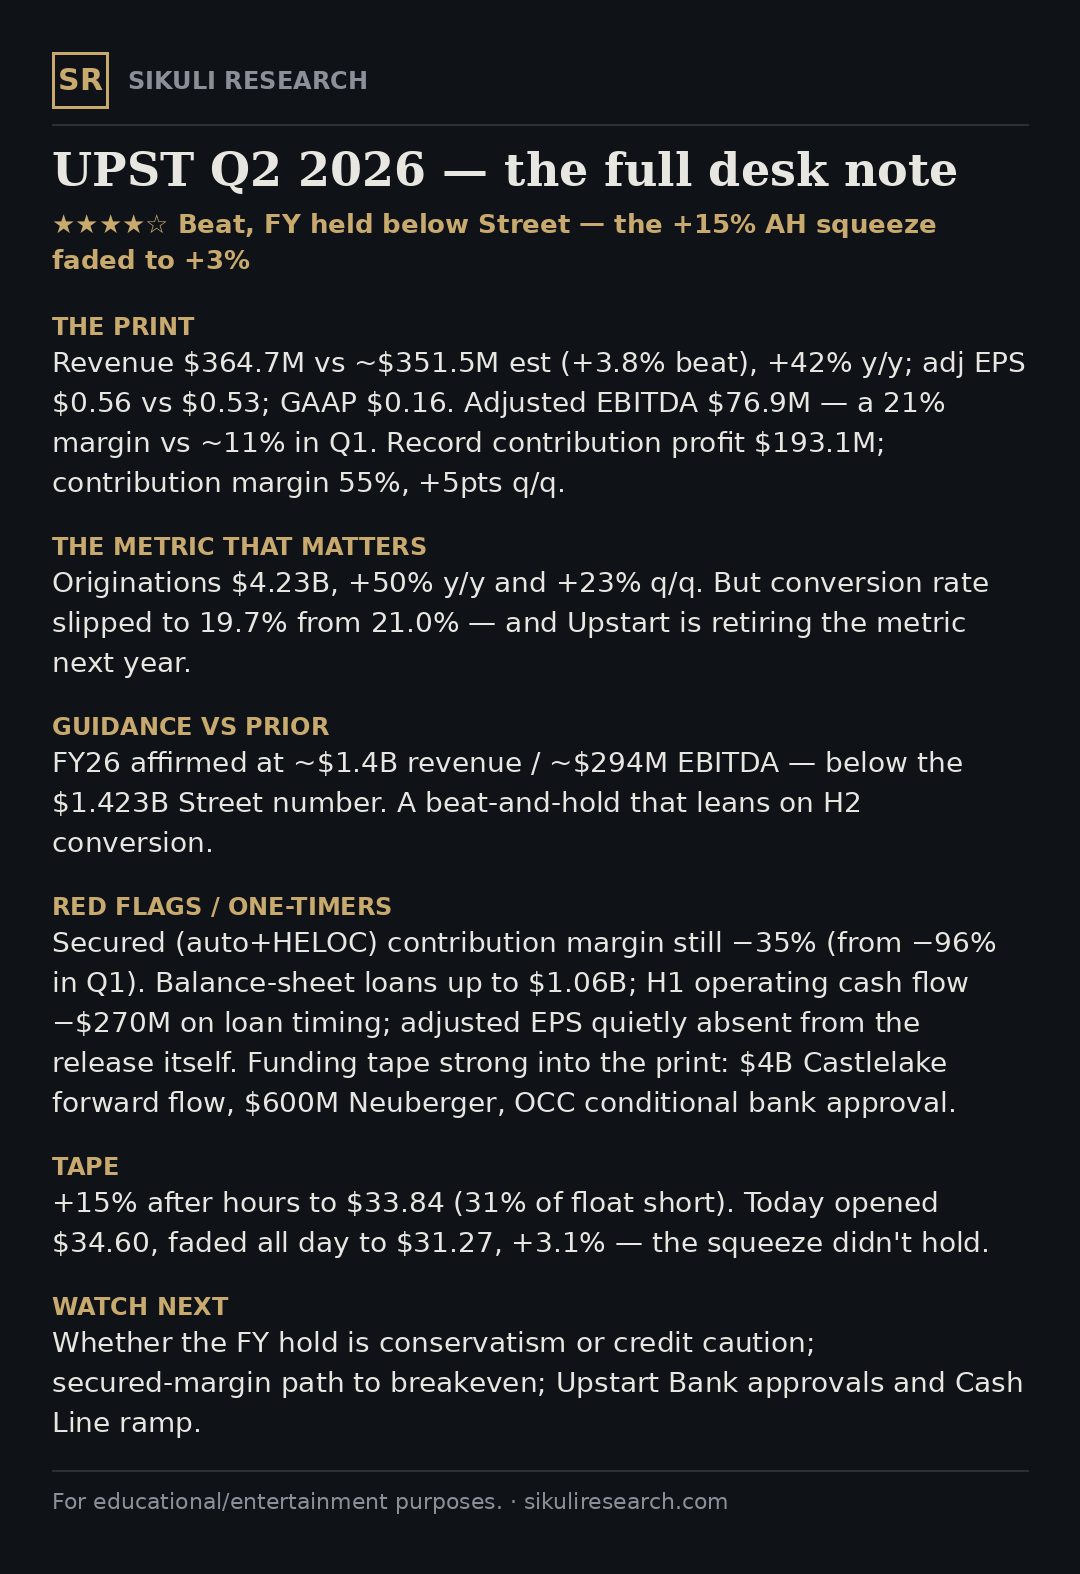
★★★★☆ Beat, Guide Held. $364.7M (+42%), EBITDA margin back to 21%, originations +50% — but the FY guide sits below Street. The +15% AH squeeze faded to +3% today. Full note on the card. #QQQ #SPX Sikuli Research — educational, not advice.
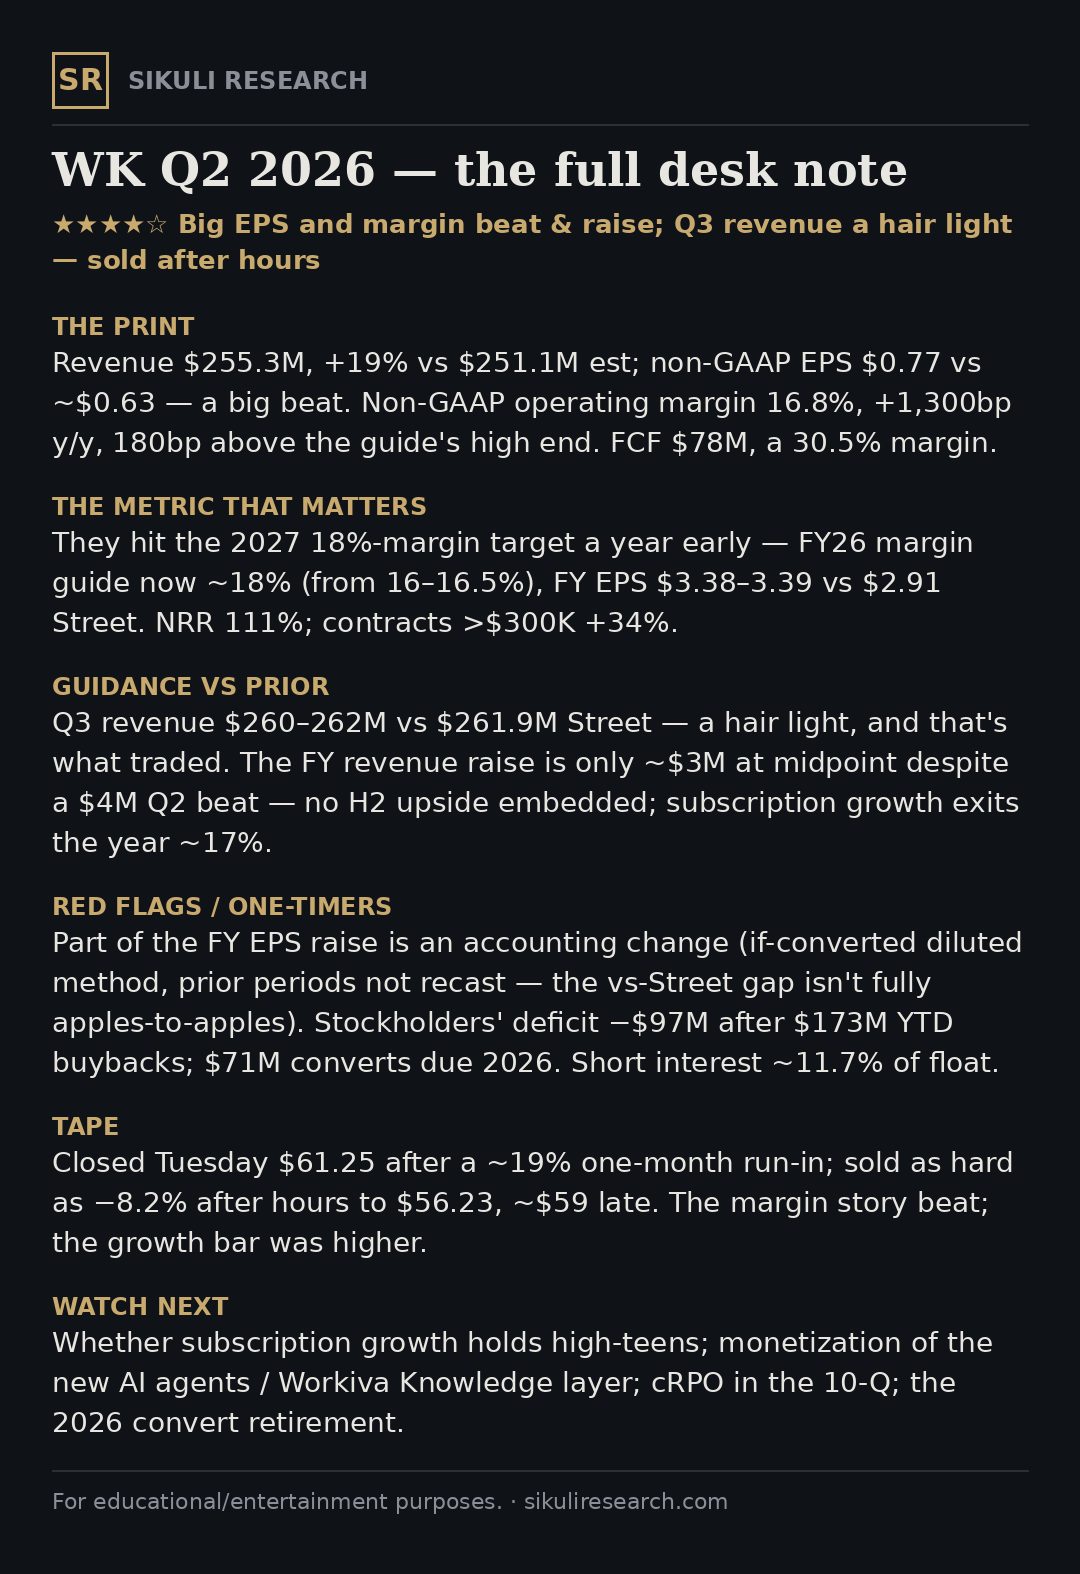
★★★★☆ Beat & Raise. Margin target hit a year early, FY EPS guide $3.38 vs $2.91 Street — sold anyway on a hair-light Q3 revenue guide after a 19% run-in. Full note on the card. #QQQ #SPX Sikuli Research — educational, not advice.
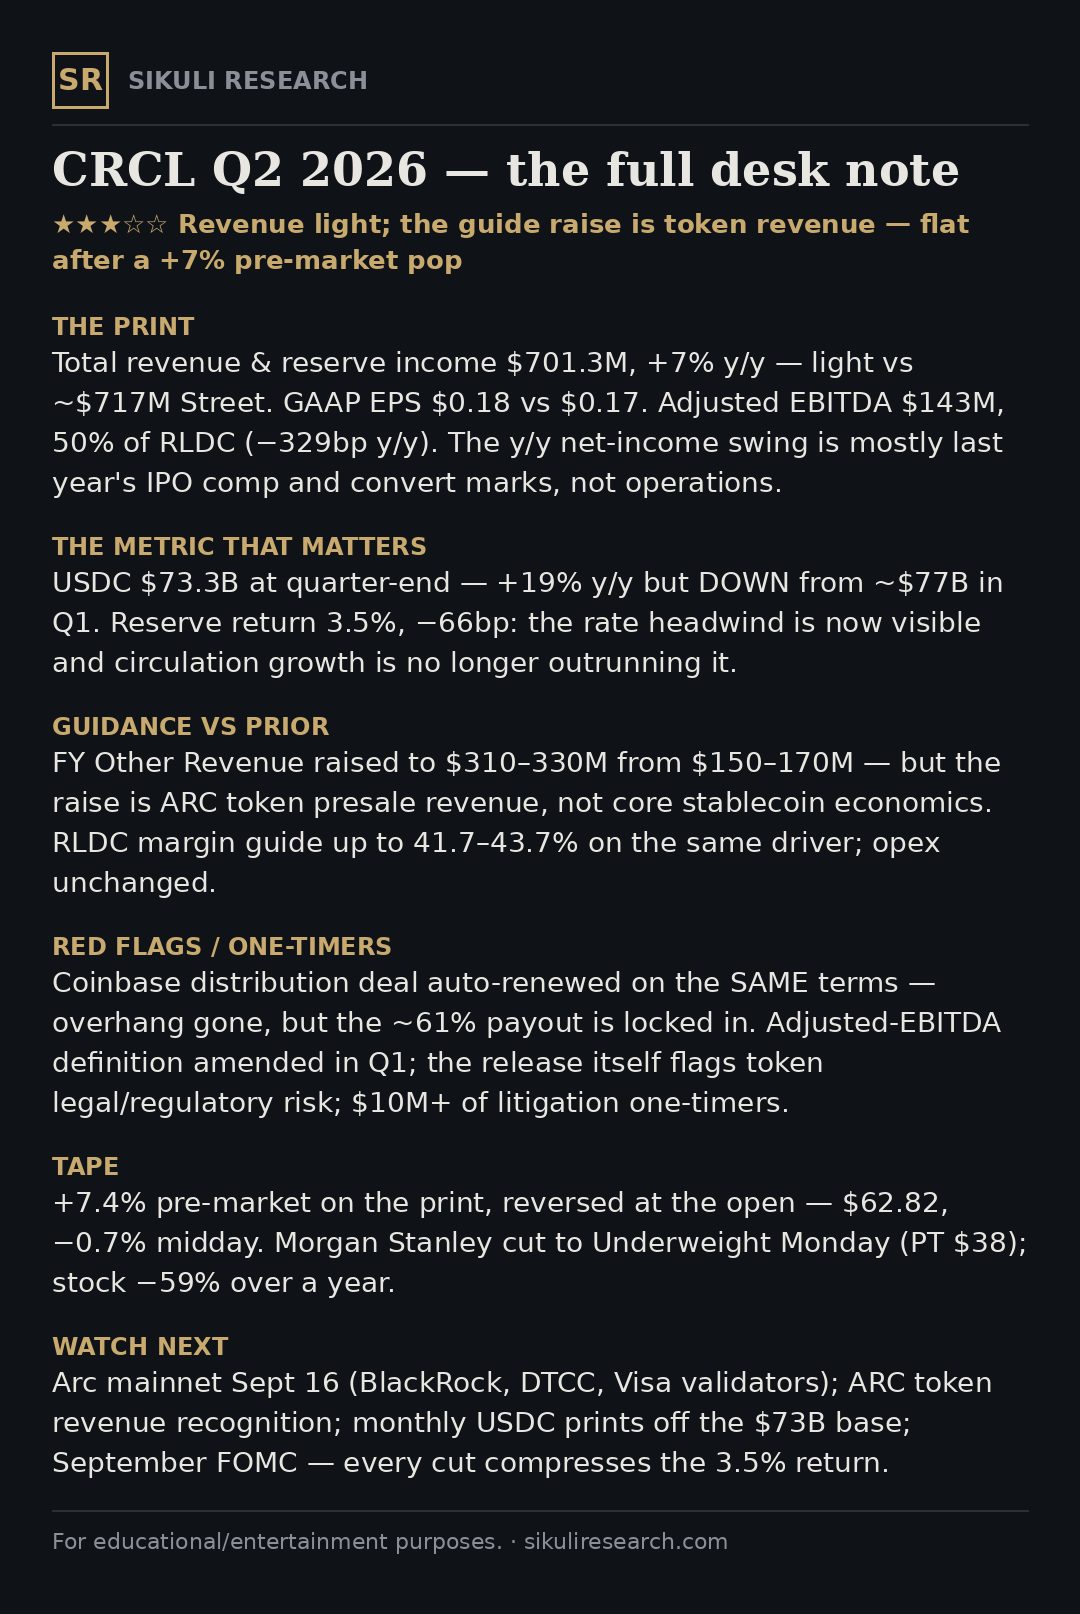
★★★☆☆ Mixed. Revenue light, USDC shrank q/q, and the big FY raise is ARC token revenue — not stablecoin economics. The +7% pre-market pop reversed by the open. Both sides on the card. #QQQ #SPX Sikuli Research — educational, not advice.
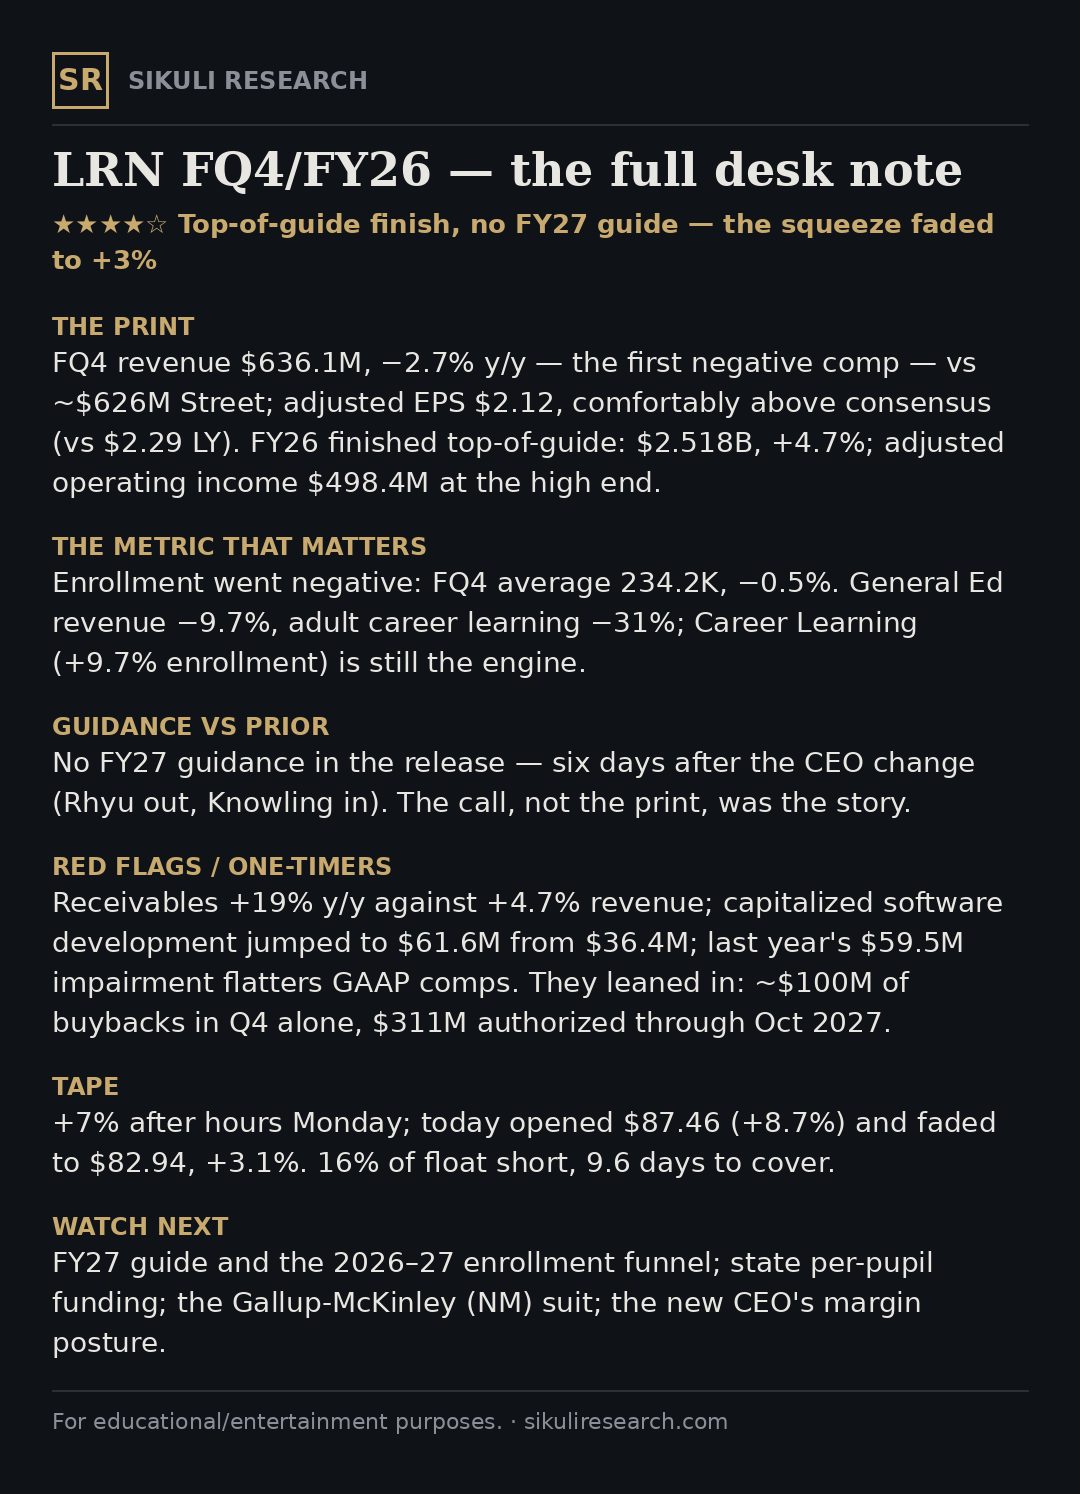
★★★★☆ Beat, no FY27 guide. A top-of-guide year, the first negative revenue comp, and a heavy buyback — the AH squeeze faded to +3% today. Full note on the card. #QQQ #SPX Sikuli Research — educational, not advice.
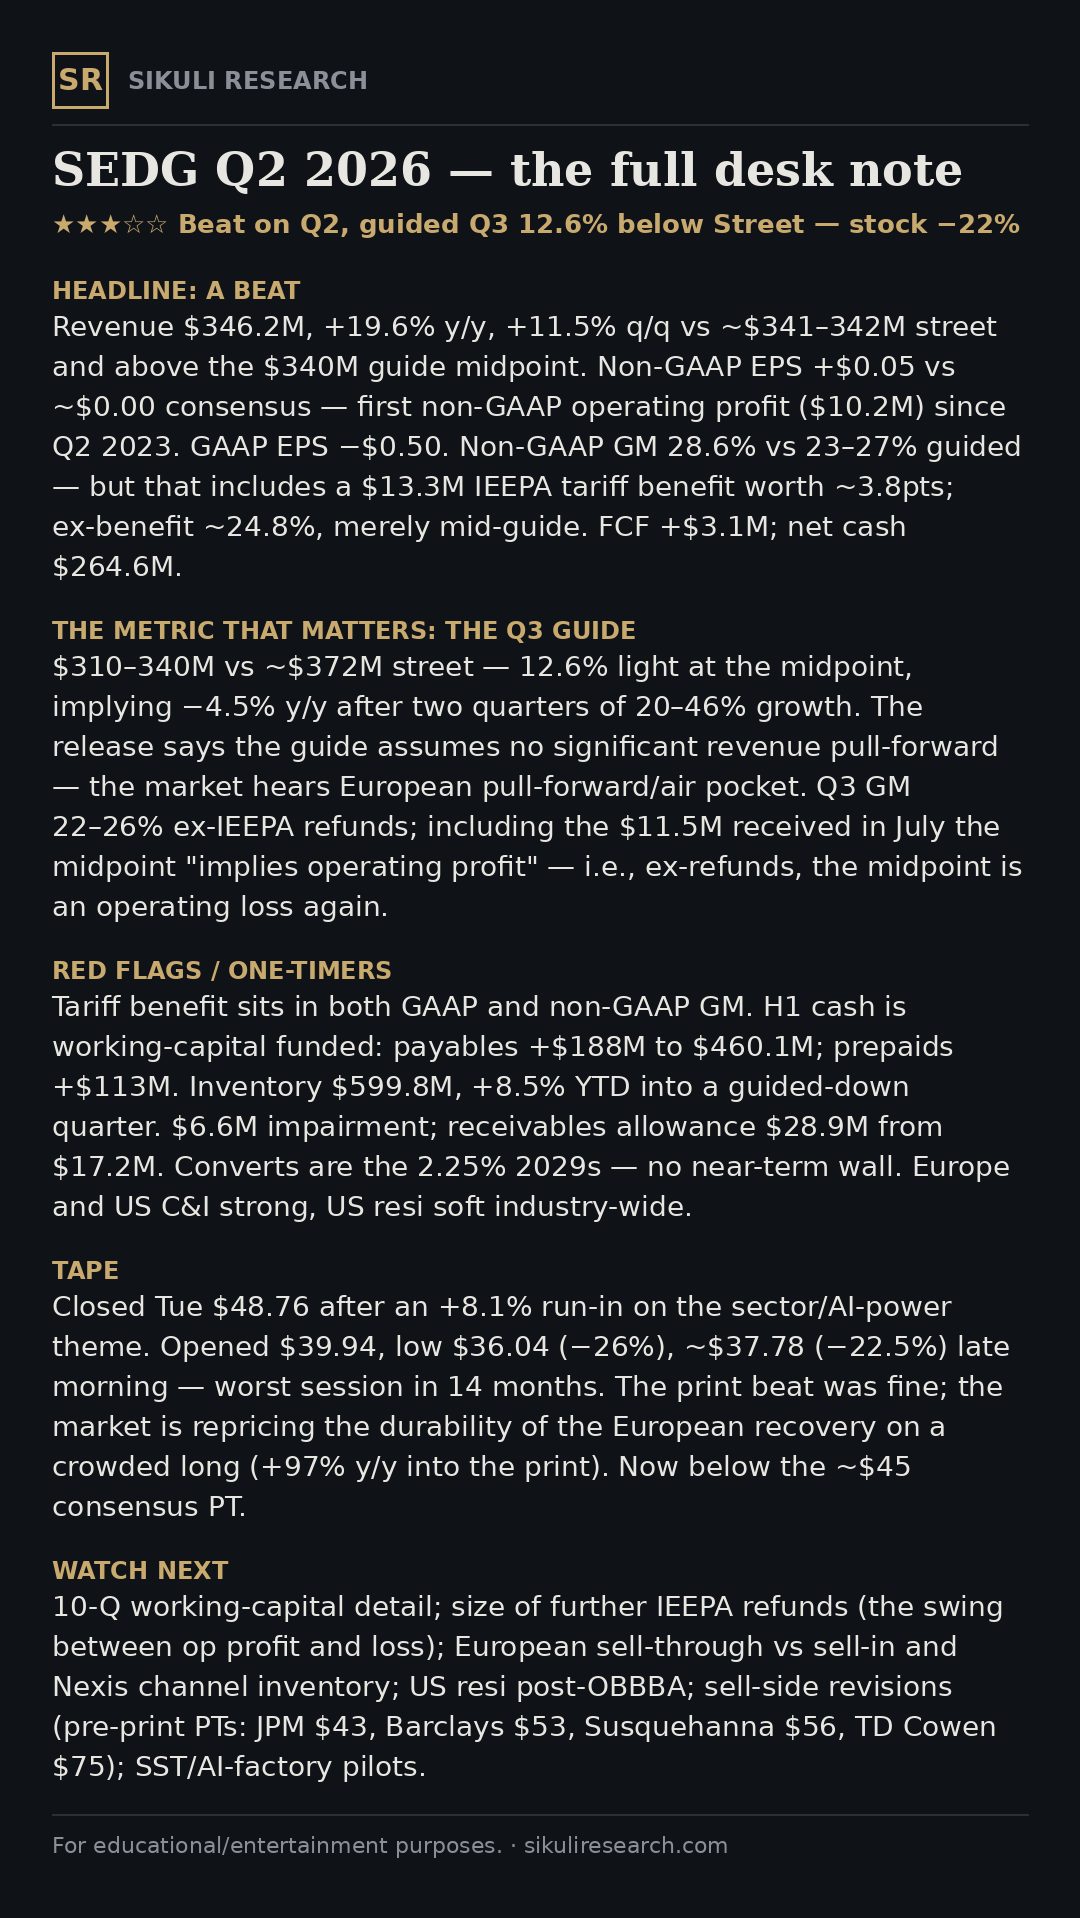
The Q2 beat was real; the Q3 guide did the damage. Details on the card — margins, the tariff-refund swing factor, and what to watch in the 10-Q. Sikuli Research — educational, not advice.
★★★☆☆ Mixed print. Q2 beat — $346.2M (+20% y/y) and the first non-GAAP op profit since 2023 — but Q3 guided 12.6% below Street; stock -22%. Sikuli Research — educational, not advice.
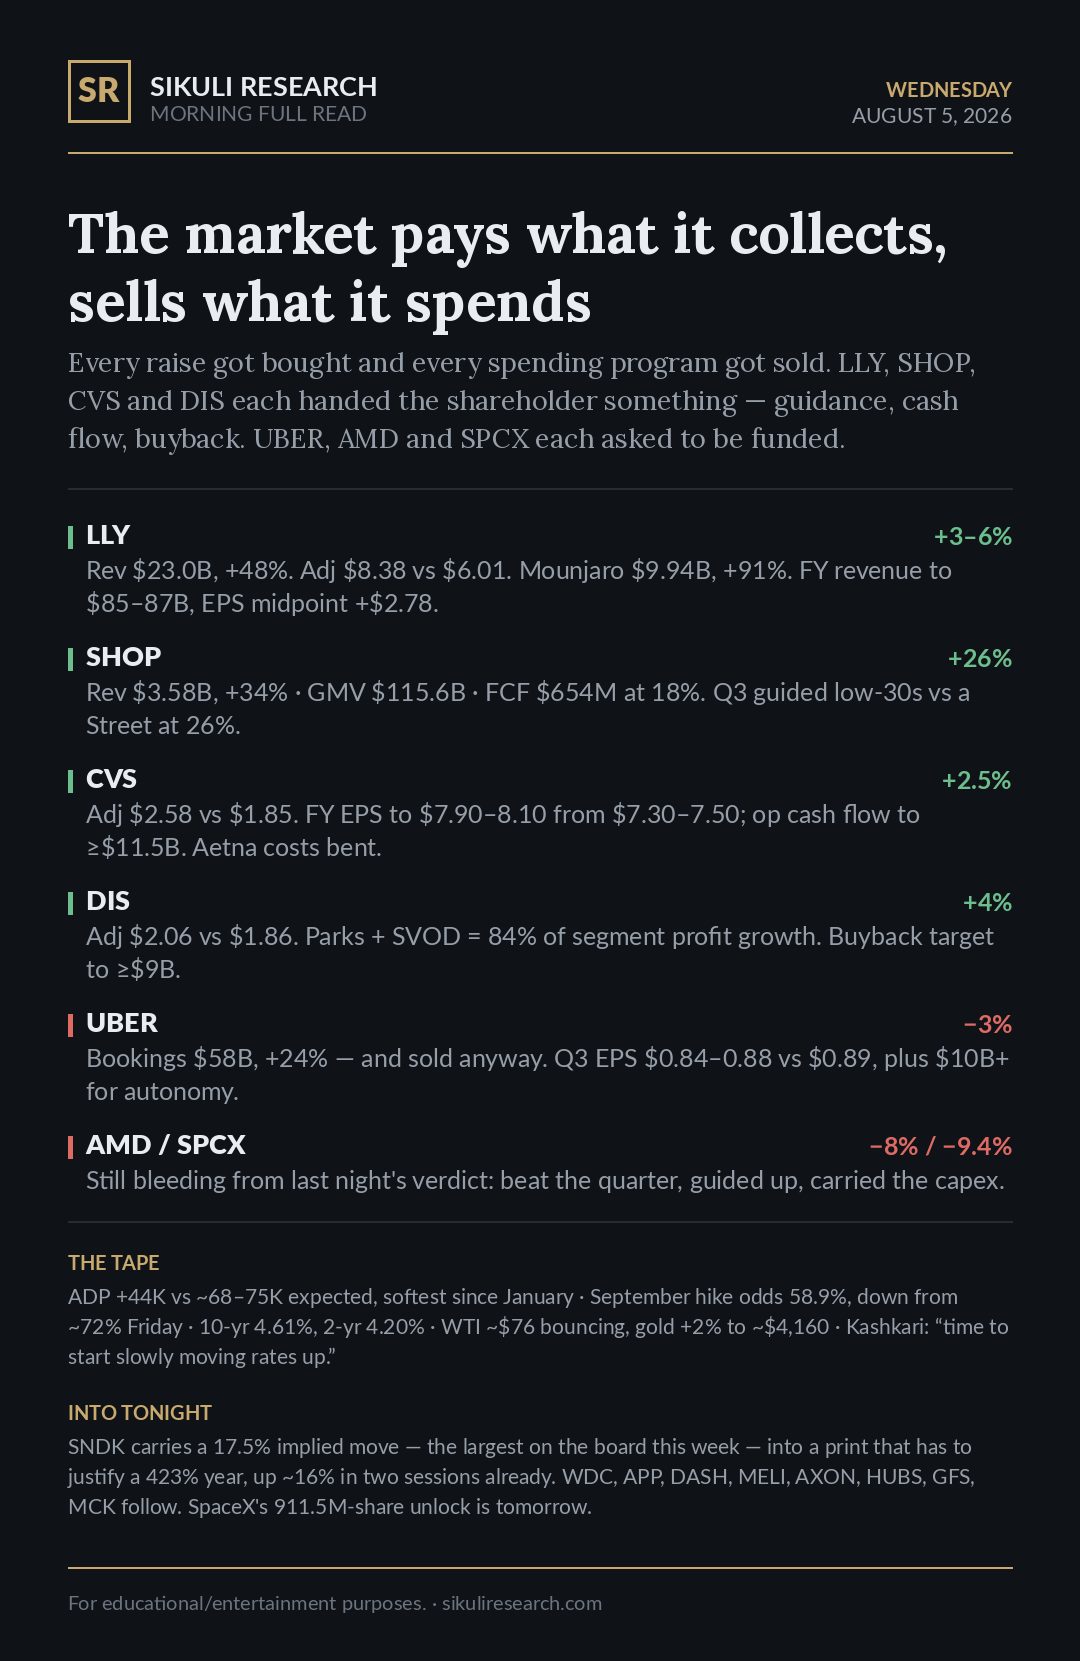
Every raise got bought, every spending program got sold. LLY +48% revenue and a raised year; SHOP indicated +26%. UBER grew bookings 24% and still fell — $10B for autonomy. Full read at Sikuli Research (link in bio)
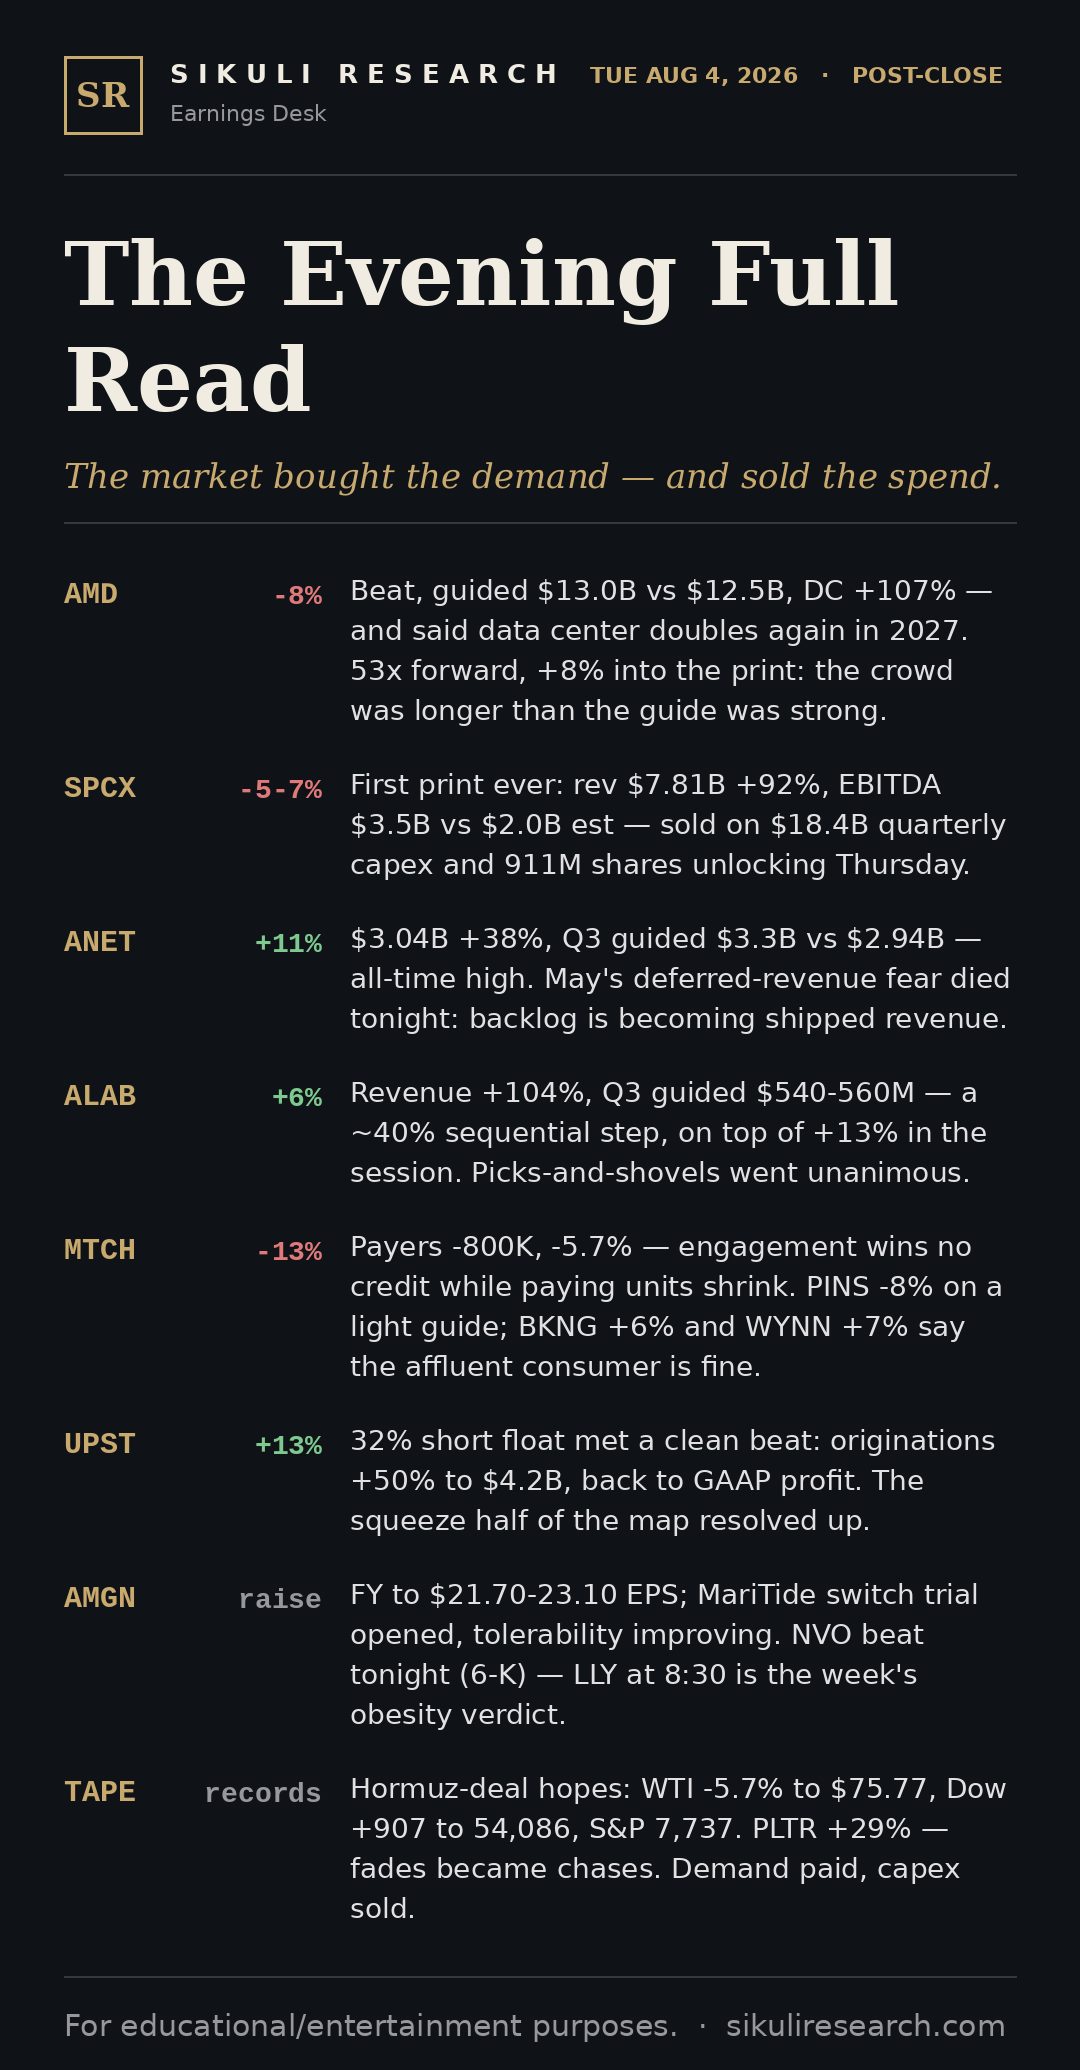
The night split the AI trade down the middle: AMD beat and guided above — sold 8%. SpaceX grew 92% — sold on $18.4B capex. ANET to all-time highs. The market bought recognized revenue and sold capex. Full read at Sikuli Research (link in bio)
New earnings reaction: Coinbase (COIN). Dated Jul 2026.
New earnings reaction: Fair Isaac (FICO). Dated Jul 2026.
New earnings reaction: First Solar (FSLR). Dated Jul 2026.
New earnings reaction: Strategy (MSTR). Dated Jul 2026.
New research note: Applied Optoelectronics (AAOI). Dated Jun 2026.
New earnings reaction: Adobe (ADBE). Dated Jun 2026.
New valuation snapshot: Credo Technology (CRDO). Dated Jun 2026.
New valuation snapshot: Marriott Intl (MAR). Dated Jun 2026.
New earnings reaction: Micron (MU). Dated Jun 2026.
New valuation snapshot: SolarEdge (SEDG). Dated Jun 2026.
New valuation snapshot: Astera Labs (ALAB). Dated May 2026.
New valuation snapshot: Circle Internet (CRCL). Dated May 2026.
New valuation snapshot: Salesforce (CRM). Dated May 2026.
New valuation snapshot: Everspin (MRAM). Dated May 2026.
New valuation snapshot: On Holding (ONON). Dated May 2026.
New valuation snapshot: Powerus (PUSA). Dated May 2026.
New valuation snapshot: Upstart (UPST). Dated May 2026.
New valuation snapshot: US Physical Therapy (USPH). Dated May 2026.
New valuation snapshot: Zillow Group (ZG). Dated May 2026.